Litigation

After a US$750 million acquisition, the parties ran the usual post-closing true-up that adjusts the price based on the target’s actual financials at closing. It turned out the seller had misapplied a revenue-recognition accounting standard in its pre-closing books, and once the standard was applied correctly the buyer owed roughly US$38.3 million more. The buyer paid, then sued separately for indemnification, arguing the seller had promised its financial statements complied with accounting standards and that promise was false. The Delaware Court agreed and let the buyer recover the extra payment.
The Court rejected the seller’s arguments that the buyer should have caught the error in due diligence, that the claim belonged in the earlier case, or that a contract clause barring double recovery blocked it. Diligence is not an audit, the claim was not ripe until the true-up concluded, and the anti-duplication clause was meant to prevent collecting twice, not to eliminate indemnity claims. The Court determined that a price true-up fixes the number, but does not by itself decide who bears the cost of an inaccurate representation.
Several U.S. treaty partner jurisdictions have recently become aggressive in extending their taxation rights to cross-border acquisition transactions and the movement of assets, such as intellectual property. As a result, multinational companies should consider seeking advance unilateral or bilateral advance pricing agreements (also referred to as “APAs”) to resolve potential disagreements with foreign tax authorities and avoid lengthy and expansive audits and litigation proceedings.
What are “APAs”?
Commonly, following an acquisition of a foreign company by a U.S.-based multinational company, certain IP assets of the foreign target may need to be integrated with such company’s other operating assets to better align the ownership of IP assets with such company group’s operating structure, functions, other assets, and risks. Such an alignment of assets could involve the license, sale, or transfer of IP to the U.S. parent company or to another member of the multinational company group located in a jurisdiction different than that of the target. A cross-border transfer of assets could result in income recognition based on the value of the assets being transferred.
An APA is an agreement between a multinational company and a taxing authority or authorities regarding the transfer pricing methodology, valuation, and pricing of assets and certain transactions. A bilateral or multilateral APA (which involves the multinational company and two or several tax authorities, respectively) provides a non-adversarial alternative to resolving potential cross-border transfer pricing disputes, among many other benefits. Furthermore, the IRS is expected to be more likely to support valuation methodologies and adjustments that are based on acceptable international tax principles and valuation methodologies. The IRS’s support of a company’s valuation methodology in an APA process could be helpful in a dispute or litigation with a treaty partner jurisdiction in support of a company’s position. As a result, a bilateral or multilateral APA process provides an opportunity to set the stage and level the playing field with the treaty partner country(ies). A bilateral or multilateral APA may be a viable alternative to consider for both treaty partners (including Canada, Germany, India, Israel, Japan, Korea, Switzerland, and others) and other jurisdictions.
As a primary benefit, a bilateral or multilateral APA could eliminate the need for uncertain tax position reporting and provide for penalty protection. It would also help parties avoid repetitive tax and transfer pricing audits; limit tax authorities’ ability to change transfer prices retroactively; allow parties to manage transfer pricing real-time (rather than responding to audits years later); and mitigate the risk, cost, and burden of an audit or potentially harmful tax litigation in the U.S. and in the treaty partner jurisdiction. Other benefits may include the suspension of current tax audits or assessments relating to the transactions covered by the bilateral or multilateral APA negotiations until the APA process has been concluded, which could take several years.
For instance, recently at least one tax jurisdiction has gone so far as to argue on several occasions that the value of a target company’s IP could be higher than the entire purchase price paid to acquire such target company. The argument has been that, surely the buyer has taken into account the tax cost associated with moving the IP following the acquisition and, thus, discounted the purchase price paid for the target company and all of its assets, including its IP. Such a result, in the absence of an APA, can have a significant effect on deal structure, outcome, and consideration if not addressed in advance.
While the taxing authorities and the multinational company are not obligated to reach an agreement, they are generally required to try to reach a mutual agreement pursuant to the applicable income tax treaty, including relevant provisions for the relief from double taxation and mutual agreement procedure.
In a welcome development in the U.S., the IRS released additional guidelines on the IRS’s Advance Pricing and Mutual Agreement Program (APMA), a program that looks to identify multinational companies and matters early in the process that are more likely to successfully reach an APA resolution based on the facts at issue. Multinational companies can contact APMA for a pre-submission review and receive a preliminary opinion on whether to proceed with the APA process within just a few weeks of submitting a pre-filing memo and providing additionally requested information.
APMA considers a number of factors, including: the significance of the transaction; the probability that transfer pricing compliance will be significantly enhanced by engaging with the treaty partner; the scope, materiality, and complexity of the company group-covered transactions in the U.S.; whether there is an actual or potential transfer pricing dispute that would be most efficiently resolved through a bilateral or multilateral APA based on the APMA’s experience; country-specific strategy considerations; and the input of the treaty jurisdiction regarding the APA.
In addition to transactions involving IP assets, a bilateral or multilateral APA can cover the provision of services by a non-U.S. entity, the provision of services by a U.S. entity, sale of tangible property into and from the U.S., use of intangible property by a U.S. entity and by a non-U.S. entity, and other transactions. In the majority of “APAs”, the covered transactions involve numerous business functions and risks.
The Delaware Court of Chancery dismissed a stockholder suit claiming that directors of B. Riley Financial breached their fiduciary duties by failing to catch problems with an investment that later went bad. The suit was framed as a Caremark claim, the label Delaware uses for lawsuits arguing that a board failed to conduct oversight. The Court reaffirmed why those claims are so hard to win: a board’s oversight duty is aimed at the company’s own internal compliance and risk systems, not at policing misconduct by outside parties the company does business with, even where the company has significant money on the line. A failed investment, on its own, is not evidence of bad faith, and stockholders cannot repackage hindsight criticism of a bad bet as a breach of duty. Delaware courts scrutinize process, meaning they evaluate whether the board informed itself and had systems in place, rather than whether that process led to a good outcome.
When allegations of corporate misconduct surface, one of the first questions companies may face is who should oversee the response. In some circumstances, an investigation led by management or in-house counsel may be appropriate. But allegations involving senior executives or directors, mission-critical compliance risks, or questions about management’s independence may require the board — often through an independent committee — to take a more active role.
In a new article for Reuters Practical Law, Sidley partner Holly J. Gregory examines when a board-driven investigation may be warranted and how boards can structure those investigations to withstand scrutiny from regulators, prosecutors, shareholders, and courts.
The article also considers recent Delaware decisions addressing directors’ responses to compliance red flags and highlights practical considerations for board-led investigations, including committee independence, investigative scope, preservation, privilege, documentation, whistleblower protections, self-disclosure, reporting, and remediation.
A Delaware Court of Chancery decision in Siegel v. Morse reaffirmed that courts will not entertain challenges to advance notice bylaws absent an actual, existing dispute. Even after the Delaware Supreme Court’s Kellner decision raised the bar for facial validity claims, the plaintiff attempted to reframe his challenge as an “as-applied” one, but the court found no ripe controversy since no stockholder had expressed an intent to nominate directors. The decision signals that bylaw litigation must be grounded in a real, concrete controversy and that generic concerns about defensive board behavior are insufficient without an active proxy contest or nomination dispute.
Many Delaware-incorporated companies include provisions in their corporate charters or bylaws requiring that stockholder lawsuits be brought in Delaware’s Court of Chancery — a court that decides cases before a judge, with no jury. This creates a tension with California law, which strongly guarantees the right to a jury trial and has a broad “long arm” statute that can pull disputes into California courts even when a company has chosen a different forum. A minority stockholder who was a California resident sued EpicentRX (a Delaware corporation) in California court. The lower courts refused to enforce the Delaware forum selection clause, reasoning that sending the case to Delaware would effectively strip the plaintiff of her California jury trial rights. The California Supreme Court reversed, holding that a forum selection clause is not unenforceable simply because it requires parties to litigate in a jurisdiction that does not provide the same jury trial right as California. The court reasoned that California’s strong public policy favoring jury trials applies to proceedings in California courts, not to courts in other states. It further reasoned that a forum selection clause determines where a dispute is litigated, not how, so it does not constitute a prohibited waiver of jury trial rights. The decision aligns California with the majority of states that enforce Delaware forum selection clauses, reinforcing the ability of Delaware-incorporated companies to channel stockholder disputes to Delaware’s specialized corporate court.
The Delaware Court of Chancery recently provided a powerful reminder of the Court’s equitable purpose, and how it will not countenance bad faith or duplicity. In Ghatty v. Mudili et al., three board members of a five-member board voted at a special board meeting to remove the remaining two directors from their officer positions, and later sued under 8 Del. C. § 225 to seek confirmation that the two directors had been validly removed from their officer roles. The Defendants challenged their removal on a number of grounds. The Court of Chancery considered one argument dispositive: that the meeting notice was inherently deficient because the meeting agenda omitted the removal action effectuated at the meeting, and indeed misleadingly suggested that one Defendant’s officer role would be expanded. The Court condemned the notice as “duplicity,” voided the vote, and held that the Defendants remained officers of the Company.
The Meeting Notice
The stated purpose of the meeting was to discuss how to bring “better governance and transparency” to the Company, and the agenda included the following items:
- Review of requests for financial statements, bank records, and supporting documentation;
- Discussion of alleged unauthorized transactions or approvals;
- Proposal for new signatory protocols and centralized finance email;
- Proposed recognition and role expansion for one of the Defendants; and
- Any additional matters raised by board members or shareholders in good faith.
Following the notice, there were additional communications amongst the directors detailing the items for discussion at the meeting. Notably, the removal of the Defendants as officers was never mentioned. In fact, although one Plaintiff director raised certain “potential areas of concern,” he specifically said that the meeting notice was not “an accusation of wrongdoing against any individual,” but was instead “a formal invitation to clarify and remedy any potential governance shortfalls,” and he invited the directors to “submit any ‘contrary evidence’ and ‘additional agenda items’ ahead of the meeting.” He also mentioned one Defendant’s “notable contributions,” and proposed that he be appointed Chief Revenue Officer and given enhanced compensation.
Before the board meeting, however, there was a “falling out” between that director and the Defendants. The latter then said that they would be unable to attend the meeting due to their “tight schedules.” The meeting went forward as planned, with only the three Plaintiff directors in attendance. Later resolutions state that, at the meeting, the three Plaintiff directors removed the Defendants as officers of the Company.
The Court found that the meeting notice technically complied with the Company’s bylaws, but nevertheless voided the vote taken at the meeting because the notice was not equitable. Instead, the Court considered it a “bait and switch that concealed the Plaintiffs’ intention to remove [the Defendants] as officers.” In holding that the Defendants remained officers of the Company, the Court stressed that “[e]quity will not abide such duplicity toward fellow directors.” The Court also rejected the argument that notice was not required where the targeted directors lacked the power to block the action, stressing that “[f]air notice fosters a genuine deliberative process – a purpose that was subverted here.”
Lessons Learned
Ghatty offers some important lessons about the value of good governance when taking board action:
- Directors are entitled to a “fair and non-misleading notice of the agenda for a special meeting,” even if the notice technically complies with the bylaws. When drafting agendas, consider whether the agenda adequately describes the discussion points and decision items for the meeting.
- Holding Regular Meetings. This meeting was the Company’s first in-person board meeting in three years. This fact was relevant to the determination of whether the meeting was a “regular” or “special” meeting. That distinction can be significant, particularly in instances where the company’s bylaws have different notice requirements for regular versus special board meetings.
- Clear Bylaws. The Court began its analysis by turning to the Company’s bylaws. In support of their argument that the meeting notice was deficient, the Defendants cited to a stockholder meeting provision in the bylaws that required a specific statement of the meeting’s purpose. Because the bylaws lacked an analog requirement for board meetings, the Court found that the notice was technically sufficient, and had to rely instead on its equitable power to reach its result. Consider whether there are unintentional gaps or inconsistencies in your company’s bylaws that can be clarified or corrected to provide more certainty and consistency across governance items. Also remember that bylaws set the rules for the game, but, as seen in Ghatty, can’t protect against bad faith.
- Records and Meeting Minutes. The Court referenced the fact that there were no contemporaneous minutes or evidence of the meeting, only a resolution dated a couple of weeks later stating that, at the meeting, “appropriate resolutions were adopted, changing certain officer and signatory roles within the Company.” Although the Court did not rely on this fact in its holding, it is a helpful reminder of the importance of appropriately and timely documenting actions taken at a meeting.
Children’s privacy regulations globally are shifting away from notice-and-consent models toward outright access restrictions, age-appropriate design mandates, categorical advertising prohibitions, and app-store-level age verification, as illustrated by Australia’s December 2025 enforcement of its under-16 social media ban. In the United States, similar legislative efforts have faced significant First Amendment challenges that have stalled most state laws restricting minor access to social media and AI platforms, while age-appropriate design requirements inspired by California’s law have been enacted in several states. Several states, including Oregon, have enacted categorical bans on targeted advertising to known minors, while app-store-level age verification laws imposing age-signal obligations on app developers are also subject to active litigation. Companies operating consumer-facing digital services should map where minors interact with their products, review advertising practices involving teens, and prepare for the eventual downstream effects of age-signal regimes.
In a Bloomberg Law article, Sidley lawyers Greg Lantier, Liv Herriot, and Raneem Eter examine recent federal court decisions clarifying lawyers’ obligations when using generative artificial intelligence (AI) in litigation. The article analyzes how courts are applying Federal Rule of Civil Procedure 11 to AI-assisted filings, emphasizing lawyers’ duties to verify citations, supervise AI-generated work product, and ensure the accuracy of court filings. The authors also outline practical governance measures law firms and legal teams can adopt to reduce AI-related litigation risks and strengthen accountability.
Courts are writing their own rules about generative AI, and in patent cases those rules differ sharply from judge to judge. This survey, current as of September 8, 2026, catalogs the generative-AI requirements in the venues where most patent infringement suits land: the Eastern and Western Districts of Texas, the Northern and Central Districts of California, the Northern District of Illinois, the District of New Jersey, and the District of Delaware and the U.S. International Trade Commission, where no AI-specific rules were identified. Only the Eastern District of Texas has a court-wide rule, making every litigant responsible for verifying AI-assisted filings. Elsewhere the obligations come from individual judges’ standing orders and vary widely, from restating the existing duty to verify what you sign to requiring a separate certificate naming the AI tool, confirmation that a human checked every citation, records of the prompts used, or disclosure of AI use in billing. Penalties include US$500 per violation and having the filing struck.
On April 29, 2026, the Delaware Supreme Court upheld the dismissal of consolidated stockholder challenges to advance notice bylaws that The AES Corporation and Owens Corning each adopted in 2023. Advance notice bylaws are the internal rules setting out how far in advance, and with what disclosures, a stockholder must tell a company it intends to nominate directors or bring business before a meeting. The stockholders attacked the provisions in the abstract, without anyone having actually attempted a nomination and been turned away.
The court held that this was not enough to proceed. Delaware courts will review these provisions when there is a concrete, live dispute about how a bylaw is being applied, not when the alleged harm depends on future events that have not occurred. The decision continues a consistent line of recent bylaw rulings and means such provisions generally will not be tested in court until a real nomination dispute arises.
On March 25, 2025, Delaware Governor Matt Meyer signed significant amendments to the Delaware General Corporation Law that provide greater predictability and clarity for conflicted transactions. The amendments create statutory safe harbors under Section 144 that preclude equitable relief and damage claims when transactions involving controlling stockholders or control groups are approved through either a properly functioning special committee of at least two disinterested directors or an informed, uncoerced vote of disinterested stockholders (with both mechanisms required only for controller go-private transactions). The amendments also define key terms including “controlling stockholder” (with a one-third voting control floor), “control group,” and “disinterested director,” extend duty-of-care exculpation to controlling stockholders, and narrow stockholder books-and-records inspection rights under Section 220 to core materials while adding heightened requirements for accessing additional records. The amendments apply to acts and transactions regardless of when they occurred, but do not apply to legal proceedings or demands commenced on or before February 17, 2025.
On February 27, 2026, in a unanimous 37-page opinion, the Delaware Supreme Court upheld the constitutionality of significant changes to the Delaware General Corporation Law (DGCL) enacted in March 2025 via Senate Bill 21 (SB 21). This decision permits Delaware corporations and their advisers to confidently rely on these amendments for transactions with interested fiduciaries (including controlling stockholders), thereby increasing transaction planning flexibility and certainty while decreasing litigation risk under Delaware law.
Background of SB 21
As previously discussed in this Sidley Update, SB 21 provided greater statutory clarity in a number of important areas that had been the subject of common law development. It amended Section 144 to, among other things, create new statutory safe harbors for transactions with interested fiduciaries, including controlling stockholders. Although these safe harbors are akin to previously existing common law standards, they reflect important changes thereto that decrease transaction planning risk beyond those prior tests. These include (i) offering safe harbor protection in all interested-fiduciary transactions (except for going private transactions) by the use of either disinterested committee/director approval or a majority-of-the-minority vote (not both), (ii) incorporating a definition of “controlling stockholder,” and (iii) codifying standards for director independence and disinterestedness. SB 21 also amended Section 220 to clarify the scope of books and records inspections. These changes applied retroactively to all acts or transactions whether occurring before, on, or after enactment, subject only to a carveout for litigation commenced or demands made before February 17, 2025 (when SB 21 was announced). The constitutionality of the Section 144 amendments, and their retroactivity, was promptly challenged.
Constitutional Questions and Answers
In Rutledge v. Clearway Energy Group LLC, No. 248, 2025 (Del. Feb. 27, 2026), the Delaware Supreme Court considered two constitutional challenges to Section 144, focused on its safe harbor provisions and retroactive application. It rejected both.
1. First, the Delaware Supreme Court held that Section 144’s safe harbors, which preclude equitable relief and eliminate damages claims against fiduciaries, do not improperly limit the Court of Chancery’s equity jurisdiction.
Highlighting the Delaware General Assembly’s long-respected and regularly employed legislative power to amend the DGCL, including in response to common law developments, the Delaware Supreme Court held that the Court of Chancery was not improperly divested of its equitable jurisdiction via SB 21’s amendments to Section 144. The Supreme Court reasoned that the Court of Chancery remains empowered to adjudicate fiduciary duty claims and to determine whether the prerequisites for the safe harbor protections in Section 144 are achieved. Although two remedies previously available to the Court of Chancery — equitable relief and awards of monetary damages against directors, officers, controllers, or control groups — are now unavailable where the Section 144 safe harbor prerequisites have been met, the Court of Chancery retains jurisdiction over fiduciary duty claims. The Supreme Court viewed SB 21 as “a legitimate exercise of the General Assembly’s authority to enact substantive law that, in its legislative judgment, serves the interests of the citizens of our State.”
2. Second, the Delaware Supreme Court held that the retroactive application of SB 21 to transactions occurring prior to its enactment does not violate due process by eliminating vested fiduciary claims.
The Delaware Supreme Court held that SB 21’s retroactive application does not extinguish vested rights of action in a manner violative of constitutional due process rights. The Delaware Supreme Court questioned the premise that Rutledge had a vested property right prior to SB 21’s enactment because his interest was more in the form of an “anticipated continuance of” existing law. But it concluded that even assuming he had such a right, the Delaware General Assembly clearly intended that the statute apply retroactively and “exercise[d] its legislative authority in conformity with the dictates of due process” by crafting a statute reasonably related to a legitimate objective. As a result, SB 21 does not strip away vested claims in violation of due process and will apply equally to all acts and transactions on or before February 17, 2025, unless already then subject to an action, proceeding, or demand.
Key Takeaways for Boards and Dealmakers
Safe Harbor Certainty
First and foremost, Clearway preserves SB 21’s empowerment of disinterested decisionmakers to protect investors in transactions with interested fiduciaries. Corporations engaging in transactions with fiduciaries may confidently rely on the safe harbor frameworks in Section 144, which will continue to increase predictability and flexibility in corporate dealmaking while reducing litigation risk. Significantly, transaction planners can be confident that any act or transaction involving an interested director, officer, controller, or control group (other than a going private transaction) may be cleansed by either a special committee approval or by a majority-of-the-minority stockholder approval. Although Clearway settles SB 21’s constitutionality, all corporate law statutory frameworks necessarily reflect some degree of unpredictability when first enacted that will be reduced over time through case law development.
Compliance and Documentation
Parties and practitioners should take into account these amendments and design transactions to fit within Section 144’s safe harbor protections to avoid potential application of the “entire fairness” standard of review. Corporations and their counsel should continue to deploy best practices to monitor and carefully document compliance with the contours of the safe harbors. Some key areas for monitoring and documentation include:
- analysis of the disinterestedness of decisionmakers;
- disclosure of all material facts to disinterested directors;
- processes supporting a “good faith” approval of any such transaction by disinterested directors “without gross negligence”; and
- disclosure of material facts in connection with any disinterested stockholder approval of a transaction.
Reincorporation Considerations
Underpinning the Delaware Supreme Court’s constitutional analysis was a deep deference to the Delaware General Assembly’s ability to amend (often swiftly) Delaware’s corporate law statutes. The decision therefore bolsters one of the reasons many corporations have chosen to incorporate in Delaware: a fast-acting and responsive legislative branch. The substance of SB 21 is likewise an important consideration in any reincorporation discussion, because the Section 144 amendments provide a roadmap for transaction planners to follow that reduces unpredictability and overall litigation risk, although we anticipate that litigation challenges will be brought to develop the contours of the statute’s application.
The Delaware Court of Chancery threw out all twelve claims a group of Jenzabar stockholders brought against the company’s founder, his former spouse, and the board. The stockholders complained about two things: that the company had paid the founder’s appeal bond and legal fees in an earlier case where he was found to have taken a corporate opportunity worth US$81 million, and that a decade of generous stock and bonus awards had let the founder and his ex-wife grow their ownership from 18% to 91% while diluting everyone else. The court held that dilution claims like these belong to the company, not to individual stockholders, so they had to be brought as derivative claims on the company’s behalf.
The rest of the case failed on timing. The claims about the appeal bond and legal fees were filed too early, because the indemnification agreement required an independent lawyer to decide whether the founder was entitled to be reimbursed, and that process was still underway. The compensation claims were filed too late, since the events happened between 2012 and 2015 and Delaware applies a three-year clock. The practical lesson for founders and counsel is that indemnification and advancement are different promises with different timing, and that if your equity grants ever draw scrutiny, the clock starts running when stockholders have enough information to ask questions.
In Fortis Advisors v. Krafton, the Delaware Court of Chancery awarded a striking equitable remedy: it ordered the reinstatement of a CEO who was wrongfully terminated using a strategy developed with ChatGPT, and extended the earnout period by the full duration of his improper exclusion. The buyer had used AI to strategize avoidance of a US$250 million earnout, but because that advice was generated outside the attorney-client relationship, it was not privileged and became damning evidence at trial. The decision puts buyers on notice that depriving seller-managers of bargained-for post-closing operational control may result in not just damages, but equitable remedies that restore control and reset the earnout clock.
One of the most common legal missteps among emerging companies involves the classification of the people doing the work. In the earliest days of a startup, founders often bring on talented individuals as “consultants” or “independent contractors,” compensating them primarily or exclusively with equity. This arrangement feels natural when cash is scarce and everyone is pitching in to build something from the ground up. But what begins as a practical solution can quickly become a significant legal liability if the company does not revisit these classifications as it matures and secures funding.
This article provides a high-level overview of the risks associated with worker misclassification, the key legal frameworks that govern these determinations, and the steps founders should take to clean up classification issues before they become costly problems.
The Common Pattern: Early “Consultants” Who Are Really Employees
It is extremely common for pre-revenue startups to engage early team members as independent contractors or consultants. The logic is straightforward: The company cannot yet afford salaries, payroll taxes, or benefits, so it issues equity in exchange for labor. On paper, the individual signs a consulting agreement, invoices the company (or doesn’t), and is treated as a 1099 worker for tax purposes.
The problem is that many of these individuals are, as a matter of law, employees regardless of what the agreement says. Classification is not a matter of mutual agreement between the parties. It is determined by the nature of the working relationship under applicable federal and state law. If the engagement looks and feels like employment, then government agencies and courts are likely to treat it as such.
When these individuals are never reclassified, the company accumulates exposure over time. That exposure includes unpaid wages, overtime, employment taxes, penalties, and potential liability under both federal and state law. These issues often surface at the worst possible moment: during due diligence for a funding round, an acquisition, or in response to a complaint filed by a disgruntled former worker.
Why Reclassification Should Be a Priority After Funding
Securing any meaningful financing event should serve as a trigger for the company to revisit every worker classification. There are several reasons for this.
First, the original justification for the consulting arrangement, namely the inability to pay cash compensation, has likely changed. Once the company has capital, it has the resources to bring workers onto payroll and provide the protections required by law. Continuing to classify a worker as an independent contractor when the company now has the means to pay wages and withhold taxes weakens any argument that the arrangement was legitimate.
Second, investors and their counsel will scrutinize the company’s employment practices during due diligence. Misclassification issues are a well-known red flag. Unresolved classification problems can delay or even derail a financing, reduce the company’s valuation, or result in specific indemnification obligations imposed on the founders.
Third, as the company grows, the risks multiply. More workers mean more potential claimants. Longer periods of misclassification mean larger back-pay and tax liabilities. And the shift from a small, informal team to a structured organization makes it increasingly difficult to argue that any given worker was genuinely operating as an independent business.
The bottom line is that reclassification is not merely a housekeeping exercise. It is a critical step in putting the company on sound legal footing for its next phase of growth.
Federal Law: The Key Frameworks
At the federal level, worker classification is governed by several overlapping tests, depending on the statute at issue.
The Fair Labor Standards Act
The FLSA uses an “economic reality” test to determine whether a worker is an employee or an independent contractor. The inquiry focuses on whether the worker is economically dependent on the company or is in business for themselves. Factors include the degree of control the company exercises over the work, the worker’s opportunity for profit or loss, the worker’s investment in equipment or materials, the permanence of the relationship, the degree of skill required, and the extent to which the work is an integral part of the company’s business. The Department of Labor has historically taken a broad view of employment under this test, and the consequences of misclassification include liability for unpaid minimum wages and overtime, liquidated damages, and attorneys’ fees.
The Internal Revenue Code
The IRS applies a common-law test that examines the degree of control and independence in the relationship. The IRS groups relevant factors into three categories: behavioral control (whether the company directs how the work is done), financial control (whether the company controls the business aspects of the worker’s role, such as how the worker is paid and whether expenses are reimbursed), and the type of relationship (including written contracts, benefits, and the permanence of the engagement). Misclassification under the tax code can result in liability for unpaid employment taxes, penalties, and interest. In some cases, officers of the company may face personal liability under the trust fund recovery penalty.
Exempt vs. Non-Exempt Classification
Once a worker is properly classified as an employee, the company must also determine whether the employee is exempt or non-exempt under the FLSA. Exempt employees are not entitled to overtime pay, but they must meet specific salary and duties tests. The most commonly applicable exemptions for startups are the executive, administrative, professional, and computer employee exemptions. Each requires that the employee be paid on a salary basis at or above a specified threshold and that the employee’s primary duties satisfy specific criteria. Founders should not assume that simply paying a salary or giving someone a managerial title is sufficient. The analysis turns on the actual duties performed, not the job title.
State Law: Where the Rules Get Stricter
Many states impose classification standards that are more restrictive than federal law, and compliance with federal standards alone does not guarantee compliance at the state level.
California’s ABC Test
California applies a particularly stringent standard under its ABC test, codified by Assembly Bill 5. Under this test, a worker is presumed to be an employee unless the hiring entity demonstrates that the worker (A) is free from the company’s control and direction in performing the work, (B) performs work that is outside the usual course of the company’s business, and (C) is customarily engaged in an independently established trade, occupation, or business of the same nature as the work performed. Prong B is often the most difficult to satisfy for startups, because early workers are typically performing tasks that are central to the company’s core business. California law also provides for significant penalties for misclassification, including penalties under the Private Attorneys General Act, which allows employees to bring representative actions on behalf of the state.
Other Notable State Frameworks
Several other states have adopted or are moving toward ABC-style tests, including Massachusetts, New Jersey, and Illinois. New York applies a similar multi-factor test and has aggressive enforcement mechanisms. States vary considerably in their approaches, and companies with remote workers in multiple states must ensure compliance in each jurisdiction where a worker is located, not merely where the company is headquartered. Founders should be particularly attentive to any state in which the company has workers, as the applicable test is generally determined by the worker’s location.
Cleaning Up Past Misclassification
For companies that have already been operating with misclassified workers, there are several steps to consider when undertaking a remediation effort.
The first step is to conduct an honest internal audit. Identify every individual who has been engaged as a contractor or consultant and evaluate each engagement under the applicable federal and state tests. Determine which individuals are likely misclassified and assess the duration and scope of the exposure.
The second step is to consult with experienced employment counsel. Remediation strategies vary depending on the jurisdiction, the number of affected workers, the duration of misclassification, and the company’s financial position. In some cases, the IRS Voluntary Classification Settlement Program may be available, which allows companies to prospectively reclassify workers with limited look-back liability in exchange for a modest payment. Similar programs or settlement frameworks may exist at the state level.
The third step is to transition misclassified workers to employee status going forward. This includes placing them on payroll, withholding applicable taxes, providing required benefits, and ensuring compliance with wage and hour laws, including proper exempt or non-exempt classification.
The fourth step is to address the equity arrangements already in place. Early equity grants made to individuals who should have been classified as employees may have been structured as contractor grants, which have different tax treatment than employee equity awards. Companies should work with both employment counsel and tax advisors to evaluate whether corrective filings or revised equity documentation are necessary, particularly with respect to Section 409A of the Internal Revenue Code, which governs deferred compensation and imposes significant penalties for noncompliance.
Finally, companies should implement classification policies and procedures that will prevent these issues from recurring as the company continues to hire. A brief intake process for every new engagement, whether employee or contractor, can go a long way toward ensuring that the correct classification is applied from the outset.
The Department of Justice announced a US$21.5 million settlement with five Deloitte entities to resolve allegations under the False Claims Act, the federal statute that penalizes companies for submitting false claims for government money. Notably, the DOJ alleged that the companies’ employment practices violated Title VII and the standard equal opportunity clause found in federal contracts, and that billing the government while out of compliance amounted to a false claim. The case is the second settlement secured under DOJ’s Civil Rights Fraud Initiative, a cross-agency enforcement push that pairs the False Claims Act with other tools such as the Equal Credit Opportunity Act. For startups, the relevant exposure is real: companies that sell to federal agencies and their subcontractors are bound by the equal opportunity clause, Title VII, and the compliance obligations that come with them.
For private companies backed by venture capital investors, acquisition is frequently the most likely path to liquidity. Founders are often laser-focused on product development, market expansion, and fundraising, without devoting the same early-stage discipline to ensuring the company is well-positioned for a future exit via a merger or acquisition.
M&A preparedness is not a late-stage exercise, but an operational strategy to position your company as an attractive, high-value target to potential acquirors.
Corporate Governance
Some of the most common obstacles to efficient M&A processes stem from issues related to corporate governance. Complex capitalization tables, unclear chain of equity ownership, and unresolved governance issues can create transaction delay and, depending on the structure of the transaction, loss of leverage.
Companies should consider focusing on three key areas of corporate governance to be prepared for future M&A processes: capitalization table discipline, stockholder rights, and board and stockholder alignment.
Capitalization Table Discipline
Maintain clear documentation of all equity issuances with proper board and stockholder approvals; confirm board minutes are complete, approved by the board, and signed; verify that 83(b) elections have been timely filed with respect to restricted stock grants to founders and early employees; and ensure 409A valuations are updated following major events that may impact valuation (such as a financing) and, absent such events, at least annually.
Stockholder Rights
Ensure all stockholders have signed the relevant stockholder agreements and that the company’s management team understands the protective provisions embedded within such agreements; similarly, ensure that the company’s management team is familiar with relevant provisions of any investor side-letters (think drag-along mechanics, rights of first refusal, and co-sale rights).
Board and Stockholder Alignment
Understand what approvals are required to approve a sale or merger of the company and whether any investor has blocking rights.
Contracting Discipline
Material contracts, such as key vendor and customer agreements, collaboration agreements, and licensing arrangements, are some of the first diligence requests in an M&A process. These contracts often contain assignment or change-of-control provisions that can require third-party consent, accelerate payment obligations, or trigger termination rights or other contractual rights that could significantly impact the trajectory of a deal. Accordingly, it is important for companies to maintain clear records of all material contracts, ensuring that all contracts are fully executed and include all attachments, exhibits, amendments, and restatements. Companies should track whether any material contracts have upcoming renewals or expiration dates. Additionally, tracking key provisions in such material contracts that may be triggered by an M&A (such as third-party consent requirements) will help streamline the M&A diligence and consent process.
Intellectual property is another value-driver for life sciences companies and technology companies, making it vital for companies to have documentation that clearly delineates intellectual property ownership. Companies should verify that all employees and contractors have signed Proprietary Information and Inventions Assignment Agreements (PIIAAs), review consulting agreements to confirm that intellectual property created by consultants/contractors has been validly assigned to the company, and obtain confirmatory assignments from founders and early contributors, if needed, and at the appropriate time. For companies with affiliated entities, confirm that the company’s core intellectual property assets sit within the target entity and not within any affiliated entities.
Being proactive can save time and expense during the M&A diligence process.
Regulatory Compliance
Depending on industry and geography, regulatory risk can become a gating diligence issue. Companies should identify areas of risk and preemptively resolve any outstanding compliance risks (e.g., data integrity, marketing, industry-specific licensing, etc.). In particular, life sciences companies should consider pursuing regulatory planning with the assistance of healthcare and/or FDA counsel (as needed) to ensure, among other things, that regulatory filings, communications, and approvals are complete and accessible.
Deal Team Preparation
Once the company has decided to start a sale process, identify at the outset who will be part of the core deal team, which will typically consist of a select number of employees and outside advisors. Members of executive management and other key internal personnel with specialized knowledge about the company’s corporate governance, labor and employment practices, employee benefits structure, assets (IP, real estate, etc.), litigation exposure, and regulatory compliance are typically included within the core deal team. Further, at the appropriate time, companies should engage outside advisors, such as outside legal counsel, financial/tax advisors, and investment bankers, all of whom can help quarterback the transaction and efficiently drive the deal process.
After the deal team is in place, consider implementing deal confidentiality procedures to maintain the integrity of the sale process:
- assign code names to the project and company participants;
- limit working group size and access; and
- consider antitrust issues and the use of “clean team” agreements and data rooms.
Data Room Readiness
Prepared companies treat diligence readiness as an ongoing process and not an exercise triggered by a letter of intent or term sheet. First, select a virtual data room that provides strong security and activity tracking. Second, build the company’s data room with organizational discipline, using logical folder structures (corporate, IP, finance, regulatory, benefits, etc.) and uploading documents in a searchable, digital format with consistent document naming conventions. Lastly, in connection with building the data room, flag with the guidance of deal counsel any confidentiality concerns and access restrictions that need to be put in place. For example, are there any documents that need to be redacted or anonymized? Does the transaction present antitrust sensitivity requiring documents to be shared through a “clean room”?
In all, a well-maintained and categorically organized data room significantly accelerates a sale process and signals sophistication to potential acquirors.
The most successful exits rarely begin when a banker is engaged. Ideally, they begin years earlier with strategic and operational foresight. Companies that understand the value of M&A preparedness can preserve negotiation leverage and act more decisively when M&A opportunities arise. After all, engineering an exit is more than closing a deal — it is positioning the company so that the right deal finds you.
Two February 2026 federal court decisions addressed how existing privilege and work product doctrines apply to generative AI, with one court (in United States v. Heppner) denying privilege and work product protection where an executive used an AI platform without adequate confidentiality safeguards and without counsel’s direction, and another (in Warner v. Gilbarco) holding that a pro se litigant’s AI-assisted analysis via a public AI platform was protected work product. These decisions signal that courts may apply existing doctrines to new technology in the legal context. Key considerations include whether the AI platform’s terms and privacy policies preserve confidentiality, the extent of attorney involvement in the AI-assisted work, and whether the materials were prepared in anticipation of litigation. Organizations should inventory AI tools and review their confidentiality terms, establish guardrails against AI use for legal analysis, and consider updating litigation hold protocols to account for AI-generated materials such as prompts and outputs.
Courts are now addressing how protective orders should govern the use of generative AI in discovery. Two federal decisions — Morgan v. V2X, Inc. and Jeffries v. Harcros Chemicals, Inc. — distinguish between “open” public AI tools that may retain and train on user data and more secure “closed” systems, and contemplate contractual safeguards before confidential discovery materials can be submitted to AI platforms. Practical takeaways may include addressing AI use explicitly at the outset of discovery and drafting concrete operational safeguards rather than referencing specific tools. Emerging issues that parties may anticipate include pro se litigants’ access to AI, AI’s influence on user behavior, and the conceptualization of AI within existing privilege and confidentiality frameworks.
Whether a company is gearing up for an acquisition, a growth equity financing, or an IPO, a due diligence review will be an inevitable part of that transaction, and that review will test not only the current business but also the integrity of a company’s historical records. Readiness for that review is critical, as once a diligence process begins, gaps in corporate approvals, equity records, contract management, intellectual property ownership, and regulatory compliance can quickly become leverage for purchase price adjustments, closing conditions, and/or special indemnities. At best, diligence gaps can consume management attention at a time when a company has little bandwidth to spare. At worst, they can detract from a company’s credibility and can have a meaningful impact on deal speed and certainty. Most issues are fixable, but the available solutions often narrow after a deal is already on the table. This article provides an overview of actionable steps leadership at mid- to late-stage private companies can take to make transaction readiness an ongoing discipline rather than a pre-signing scramble.
Set Up and Maintain a Virtual Data Room
Rather than waiting until a letter of intent is signed, companies should stand up and maintain a virtual data room (VDR) early, using records they already keep locally, and treat it as a living repository of critical corporate documents. Management teams that prepare to address anticipated diligence focus areas and maintain organized virtual records early are better positioned when a process launches than teams that start flat-footed. Companies can get a head start by asking outside counsel for a standard due diligence request list, which serves as an organizational and gap-identification tool, as well as an organized table of contents for their VDR. This ensures that documents are comprehensive and indexed by categories prospective investors and acquirers will expect.
The VDR should contain current, fully executed, and dated documents together with all amendments, statements of work, and side letters. Superseded and terminated agreements should be archived, not deleted or mixed with operative versions. One small but time-saving step in setting up a VDR is using a consistent and intuitive naming convention as documents are uploaded, which will help not only management but also third-party reviewers quickly navigate the VDR’s contents. Once a diligence process begins, access should be staged and subject to tiered permissions, with additional controls for competitively sensitive information, compensation data, and litigation files; privileged materials should be withheld or handled through a process designed to preserve privilege. Particularly when a potential buyer is a competitor, or when the underlying material is subject to confidentiality restrictions that do not permit sharing with a potential acquirer or investor, counsel should advise prior to upload and contemplate redactions, clean-team arrangements, and restrictions on downloading or printing. When in doubt, leave it out; it is easier to pause early and evaluate permissions and other protections than to pull back a document after it has been shared.
A word of caution: prospective investors now run AI review tools that can scan an entire data room in minutes, and while that process can generate false positives, it can also magnify every internal inconsistency across the VDR, including in the cap table, contracts, and other materials. As a best practice, keeping the VDR updated quarterly helps identify issues early and positions the company and management to earn credibility from the moment that transaction diligence begins.
Maintain a Corporate Record Book and Organizational Documents
M&A buyers and growth equity investors will expect clean and current corporate governance records. This means prospective investors will review: current versions of the certificate of incorporation (including all amendments) and bylaws; board and stockholder minutes; and fully executed, dated written consents. An improperly compiled consent with a missing signature page or date can cost the company meaningful time and resources to track down or, worse, require corrective action to cure. Every material corporate action should tie out to a corresponding board and/or stockholder approval, including equity issuances, option grants, director and officer elections, and subsidiary formations.
Companies should also at least annually confirm good standing in their state of incorporation and in every jurisdiction in which they are qualified to do business. Outside counsel can obtain verbal good standing confirmations from third-party service providers, often for a nominal or no cost to the company. Good standing lapses can trigger fees, taxes, and penalties and, in many states, can bar the company from bringing suit in local courts until the lapse is cured, although a lapse does not typically invalidate contracts executed while the company was not in good standing. For an additional layer of caution, companies can consider ordering lien and litigation searches from third-party service providers in the same set of jurisdictions.
Ensure Vigilant Capitalization Table Hygiene
The company should expect buyers or investors to request a current copy of the capitalization table and, in the case of an equity financing, a pro forma cap table reflecting the completed round. Most cap table hygiene issues exist well before a contemplated transaction and surface in the diligence process. Common hiccups include unsigned option grants, undocumented stock issuances, unrecorded convertible note draws, and inconsistencies between vesting schedules and employment terms. Cap table accuracy is key: a company’s representations about its capitalization are often treated as fundamental representations, giving buyers or investors the ability to claim breach even for minor discrepancies. Moreover, a messy cap table can be perceived as poor ownership discipline by the company or its management.
With assistance from outside counsel, the company should reconcile the cap table against the stock ledger and equity grant documentation, ensuring that every stock and option issuance is supported by board resolutions, grant agreements, evidence of payment of the exercise or purchase price, and, if applicable, an approved, unexpired equity incentive plan. Each option grant should also be supported by a current 409A valuation that supports the board’s determination of the fair market value of the underlying shares.
Importantly, companies should develop a clear understanding of how antidilution provisions operate and how change-of-control acceleration clauses (single-trigger and double-trigger) may affect the equity/distribution waterfall in a transaction. Modeling these scenarios in advance allows management to communicate the deal economics clearly to all stockholders and avoids last-minute surprises that can derail negotiations.
Understand Key Provisions in Material Contracts
Counsel for buyers and investors will expect the opportunity to review each contract that is material to the business. These typically include: contracts with key customers and suppliers above certain revenue or expense thresholds; license agreements; leases; employment and severance agreements with key personnel; and other contracts that are important to the business. These contracts often contain change-of-control consent triggers, rights of first refusal, out-licensing restrictions, most favored nation provisions, exclusivity, non-solicit, non-compete, and other restrictive covenants. In certain circumstances, a counterparty may have a notice, consent, or termination right in connection with a transaction. Accordingly, with the help of outside counsel, a company should be generally aware of which key agreements contain those provisions and should have a plan for obtaining consents or providing timely notice in advance of entering into a transaction process. Seeking consent late in the process can give leverage to the counterparty, which can increase overall costs and decrease deal certainty.
Confirm Intellectual Property Ownership and Assignment of IP
Depending on the company’s core business, clean IP title is often a significant driver of the diligence process. One consideration that comes up time and again is whether every founder, employee, and contractor who contributed to the company’s IP portfolio has executed an invention assignment agreement that assigns all intellectual property rights to the company. It isn’t uncommon for advisors and early contributors in early-stage companies, often compensated in equity, to miss the assignment paperwork altogether, or to execute, but not date, the assignment. Any gaps in assignment should be addressed ahead of the buyer or investor diligence process, which can be done with the help of outside IP counsel. Companies should also routinely conduct an audit of open-source software usage to confirm compliance with applicable license terms.
Maintain Compliance with Industry-Specific Regulatory Requirements
Companies operating in regulated industries, such as healthcare, financial services, energy, and government contracting, should confirm that all material licenses, permits, and registrations are current and in good standing. Identifying regulatory approvals or notices that would be required in connection with a change-of-control or assignment of a license can avoid an additional layer of investor diligence caused when gaps are identified later in the deal negotiation process. Regulatory non-compliance discovered during diligence can significantly delay closing or reduce deal certainty.
The Court of Justice of the European Union has clarified whether a health-related product counts as a “medical device” in the EU, which determines whether the heavy compliance obligations of the Medical Devices Regulation apply. In Case C-427/24, Diagramm Halbach, the Court held that the analysis has two parts: what the manufacturer says the product is for, drawn from labeling, instructions, and marketing, and whether the product objectively performs one of the specific medical functions the regulation lists, such as diagnosis, monitoring, or treatment of disease. Marketing claims should not be considered in isolation and may not pull a product into the regime if it does not actually perform a medical function, and equally a company cannot avoid the rules by staying quiet about an obvious medical use. For founders building software or AI-enabled health tools, the ruling sharpens the line between administrative or organizational features and functions that genuinely inform clinical decisions, and that distinction determines whether CE marking and conformity assessment are required before selling in the EU.
In a US$250 million acquisition, the buyer refused to pay one stockholder his merger proceeds unless he first signed a joinder agreement that included a sweeping release of any claims he might have against the companies. After trial, the Delaware court held that withholding payment on that condition breached the company’s charter. A stockholder cannot be forced to give up legal claims just to collect money he is already owed, unless he receives something extra in exchange for that release. The company eventually conceded the point.
The Delaware Supreme Court recently affirmed that, with respect to limited liability companies (LLCs), courts will not fill gaps with implied duties that parties chose not to include in the LLC’s operating agreement. In Khan et al. v. Warburg Pincus, LLC, the Court found that minority LLC members could not use the implied covenant of good faith and fair dealing to challenge the outcome where the LLC agreement expressly waived fiduciary duties, authorized self-interested conduct by the majority investor, and provided a specific amendment mechanism for differential consideration. The Court refused to import corporate-style fairness and disclosure obligations where parties had negotiated a detailed contractual governance scheme, reinforcing Delaware’s highly contractarian approach to LLCs.
On August 19, the U.S. Federal Trade Commission (FTC or Commission) proposed an “Enforcement Policy Statement Regarding Personalized Pricing.” The statement explains that the FTC will prioritize enforcing its consumer protection mandate to prevent companies from varying prices based on individual consumers’ personal data without certain disclosures. The public — businesses and consumers alike — will have an opportunity to provide feedback on the policy statement. Comments were due by September 25.
As used by the FTC, “personalized pricing” means the practice of setting the price offered to a particular consumer based on that consumer’s personal data or inferences drawn from it. Importantly, the FTC does not treat every individualized or variable price as personalized pricing. It distinguishes dynamic pricing based on market conditions, such as changes in supply and demand that affect everyone in the same market, including highly localized rideshare demand; regional price differences attributable to taxes, regulation, or local market conditions; and prices that inherently depend on a purchaser’s individual characteristics — its examples are insurance and credit, where individualized risk legitimately affects price.
Federal prosecutors in Manhattan and the Commodity Futures Trading Commission charged a Google software engineer on May 27, 2026, with using confidential internal search data to make money on Polymarket, a platform where people trade contracts tied to whether a specified event will occur. It was the second such case in weeks, following one involving a service member accused of trading on classified information, and it pushed insider trading style theories well beyond stocks and bonds into event contracts.
The charges raise unsettled questions about whether confidential business information is protected in these markets the way it is in securities markets, and how far the CFTC’s enforcement authority reaches. For companies, the immediate concern is that standard insider trading and confidentiality policies were written with company stock in mind and may say nothing about employees trading on outside prediction platforms using nonpublic internal data. Regulators applying familiar fraud theories to a new market is the development to watch.
As prediction markets expand beyond elections and sports to cover corporate, regulatory, and geopolitical events, employees, directors, and other insiders who know something nonpublic may be able to profit from that knowledge without ever touching a share of stock. The government’s position, reflected in the first insider trading case brought over these markets, is that existing insider trading and antifraud principles already apply to event contracts. That leaves a gap for most companies given that standard insider trading policies, confidentiality agreements, and codes of conduct are typically drafted around trading in the company’s own securities and may not reach these platforms at all.
To avoid legal, reputational, and compliance exposure, organizations – whether public or private – should address prediction markets before an incident rather than after, including by: prohibiting misuse of confidential business information, naming prediction markets explicitly in the company’s relevant policies, extending confidentiality obligations to information that could move an event contract, training people on the risk, and adding monitoring and reporting controls.
Ordinary Delaware law tells a board selling control to get the best price reasonably available; however, by statute, directors of a public benefit corporation must balance stockholders’ financial interests against the interests of other people affected by the business and the company’s stated public mission. In Drakes Landing Associates, L.P. v. Tilden Park Capital Management, L.P., the court held that the Revlon stockholder value maximization standard of conduct does not apply to these directors, though courts may still review their decision-making under an enhanced scrutiny standard. The case was dismissed on a separate ground: the directors were protected by a statutory safe harbor, given that their decision was found to be informed, disinterested, and not one that no sensible person would approve. Here, an independent special committee with its own lawyers and a banker ran a market check before approving emergency financing that heavily diluted existing holders.
When it comes to non-competes, the state of California is not like much of the United States. The state maintains one of the most employee-friendly legal regimes in the country when it comes to post-employment restrictions, and those who fail to appreciate the breadth and force of California’s prohibitions risk not only unenforceability but also significant legal exposure.
California’s legal landscape demands that startups and investors approach restrictive covenants with clear eyes. Noncompetition agreements and customer nonsolicitation clauses are void. Employee nonsolicitation provisions are very likely void. And the increasingly popular strategy of repackaging a restrictive covenant as a trade secret protection, including by prohibiting the “use of proprietary information in order to” compete, solicit, or recruit, should be drafted and enforced narrowly to avoid an argument that they are operating as noncompetes in disguise.
The Foundation: Business and Professions Code Section 16600
California’s hostility toward restrictive covenants is rooted in Business and Professions Code Section 16600, which provides, in relevant part, that “every contract by which anyone is restrained from engaging in a lawful profession, trade, or business of any kind is to that extent void.” Courts have interpreted this provision broadly. Unlike jurisdictions that evaluate noncompetition agreements under a “reasonableness” standard, weighing the employer’s legitimate interests against the burden on the employee, California’s statute operates as a near-categorical prohibition. A contractual provision that prevents a former employee, consultant, or advisor from freely pursuing their livelihood is void on its face, regardless of how narrowly it is drafted, how short its duration, or how limited its geographic scope.1
The California Supreme Court held that the statute prohibits noncompetition agreements except in narrow statutory exceptions such as the sale of a business or the dissolution of a partnership. The court expressly rejected the argument that California should adopt a “narrow restraint” exception permitting noncompetition clauses that impose only limited restrictions on an employee’s future activities. The message was unambiguous: In California, noncompetition agreements with employees are void.
The Legislature also made it unlawful for an employer to enter into or attempt to enforce a noncompete agreement that is void under California law, even if the agreement was entered into outside of California.
Beyond Noncompetes: Employee Nonsolicitation Covenants
Founders and investors often assume that even if noncompetition agreements are off the table in California, employee nonsolicitation provisions, which are clauses that prevent a departing worker from recruiting former colleagues to join a competitor, remain permissible. This assumption is incorrect, or at least highly precarious.
California courts have increasingly treated employee nonsolicitation covenants as restraints on trade that fall within the ambit of Section 16600. The reasoning is straightforward: If a former employee cannot contact or recruit colleagues they previously worked with, their ability to engage in their profession is meaningfully restricted. They cannot freely build a team, they cannot leverage their professional network, and they are placed at a competitive disadvantage relative to others in their field who are not subject to such restrictions. While some practitioners still debate the outer boundaries of the holding (for instance, whether a narrowly drawn “no-raid” provision aimed at preventing the mass departure of an entire team might survive scrutiny), the prevailing trend in California jurisprudence strongly disfavors employee nonsolicitation covenants of any kind.
For startups, this has significant implications. It is common in the technology sector for key engineers, salespeople, or executives to depart and bring colleagues with them to a new venture. While this can be deeply disruptive to a young company, attempting to prevent it through contractual nonsolicitation provisions is unlikely to succeed in a California court and may expose the company to counterclaims.
Customer Nonsolicitation Covenants: An Equally Hostile Landscape
Customer nonsolicitation provisions - clauses that prohibit a former employee from soliciting or doing business with the company’s clients or customers - face a similarly difficult road in California. The California courts have confirmed they are just as much a restraint on mobility as an employee noncompete.
Some California courts have drawn a distinction between clauses that prevent a former employee from soliciting customers and clauses that merely prevent the misuse of trade secret information (such as confidential customer lists) to solicit those customers. This distinction brings us to one of the most important, and most misunderstood, issues in this area of law.
The Trade Secret “Workaround” That Isn’t
Precisely because California’s prohibition on restrictive covenants is so broad, creative drafters have long sought workarounds. One of the most common is to frame a restrictive covenant not as a restriction on competition or solicitation, but as a restriction on the use of the company’s proprietary or confidential information. Under this approach, an agreement might provide that the employee or consultant “shall not use Company proprietary information or trade secrets in order to compete with the Company,” or “shall not use Company confidential information to solicit Company employees or customers.”
The logic behind this formulation is superficially appealing. California law does, after all, protect trade secrets through the California Uniform Trade Secrets Act (CUTSA) and does permit employers to require employees to maintain the confidentiality of genuinely proprietary information. If the clause is framed as a trade secret protection rather than a restraint on competition, the argument goes, it should survive scrutiny under Section 16600.
The critical question is whether the clause, as drafted and as applied, operates as a genuine trade secret protection or as a de facto restrictive covenant dressed in the language of trade secret law.
Consider a clause that states: “Employee shall not use Company proprietary information in order to solicit Company’s customers.” On its face, this appears to be a narrow, information-based restriction. But in practice, a former employee who spent years managing a portfolio of customer relationships will find it nearly impossible to demonstrate, to the satisfaction of a litigious former employer, that their solicitation of a customer was based entirely on publicly available information and not, in any respect, on knowledge acquired during their employment. The clause effectively gives the former employer a veto over any customer solicitation by the departing employee, because the employer can always allege that the solicitation was informed by proprietary knowledge. The practical effect may be difficult to distinguish from a customer nonsolicitation covenant.
The same analysis applies to clauses framed as restrictions on using proprietary information to compete. A provision stating that the employee “shall not use Company trade secrets in order to engage in a competing business” may sound like a reasonable trade secret protection, but if the employee’s general knowledge of the company’s business strategies, product roadmap, or market positioning is broad enough, the clause effectively prevents the employee from working in the same industry. At that point, it is a noncompete in all but name. The important takeaway is that the inclusion of trade secret language does not immunize a clause that functions as a restrictive covenant.
This does not mean that employers cannot protect their trade secrets. They absolutely can, but they must do so through mechanisms that California law actually recognizes. A well-drafted confidentiality and nondisclosure agreement that identifies categories of protected information and prohibits its disclosure or use is generally enforceable. An employer can also bring a claim under CUTSA if a former employee actually misappropriates trade secrets to gain a competitive advantage. What an employer cannot do is use the specter of trade secret protection to achieve what amounts to a blanket prohibition on competition or solicitation.
Practical Implications for Consultants and Advisors
Much of the foregoing discussion has focused on employees, but the same principles apply with equal force to independent contractors, consultants, and advisors - relationships that are ubiquitous in the startup ecosystem. Technology companies frequently engage advisors under advisory agreements that include restrictive covenants, sometimes imported wholesale from templates designed for jurisdictions where such provisions are enforceable. In California, these provisions are no more valid when imposed on a consultant than when imposed on an employee.
Indeed, the case for enforceability may be even weaker with respect to independent contractors and advisors, who by definition maintain their own businesses and serve multiple clients. A nonsolicitation or noncompetition clause imposed on a consultant who advises several companies in the same sector would directly restrict the consultant’s ability to carry on their independent business and be squarely at odds with Section 16600.
All parties should review their advisory agreements, consulting agreements, and independent contractor agreements to ensure that they do not contain provisions that California law would render void. The inclusion of such provisions does not merely result in unenforceability; under the 2024 amendments, it can result in affirmative liability.
A Word About Choice of Law and Forum Selection
Some parties sometimes attempt to circumvent California’s restrictions by including choice-of-law provisions that designate a more permissive jurisdiction, for example, specifying that the agreement will be governed by the laws of Delaware or New York. This strategy is largely ineffective for individuals who work in California. California courts have consistently held that Section 16600 reflects a fundamental public policy of the state, and they will apply California law to restrictive covenants affecting California-based workers, regardless of the contractual choice of law. Furthermore, it is unlawful to enforce a void noncompete in California even if the agreement was signed outside of California.
For investors conducting due diligence on California-based portfolio companies, this is an area of particular concern. A company whose key employee agreements rely on restrictive covenants (whether styled as noncompetes, nonsolicitation clauses, or trade-secret-based activity restrictions) may have a materially weaker competitive moat than its cap table suggests. Diligence should specifically address the enforceability of employee and consultant agreements under California law and should flag any provisions that may expose the company to liability under the current statutory framework.
Federal health regulators settled four ransomware investigations on April 23, 2026, with a health provider network, an imaging provider, a third-party benefits administrator, and a self-funded health plan. Together the breaches exposed health and financial data for more than 427,000 people, and the companies agreed to pay a combined US$1,165,000 and to follow corrective plans monitored for two years. The common thread was not how the companies responded after the attacks but what they had failed to do beforehand: none had a complete, current assessment of where sensitive health data lived, how it moved through their systems, and what could go wrong.
For a startup handling health data, or acting as a vendor to one, the practical signal is that regulators are judging security preparation, not just incident response. Expectations include an up-to-date inventory of systems and data flows, encryption, multi-factor login, logging, vulnerability scanning, and training. Pending amendments to the HIPAA Security Rule would make many of these steps mandatory, with roughly 240 days to comply once finalized.
Hong Kong’s securities regulator is taking a harder line on claims that documents are shielded by legal professional privilege. Speaking in late August 2026, the Securities and Futures Commission’s head of enforcement said the agency is prepared to push back against over-broad privilege claims, echoing a recent court ruling. In that case, a broker hired outside lawyers after concerns arose about the handling of confidential information around a block trade, and the resulting internal investigation report was given to the SFC under a limited waiver. When a hedge fund manager sought the report, interview notes, and underlying communications, the broker claimed privilege and lost. The court applied the dominant purpose test: a document is privileged only if it was created mainly to obtain legal advice or for litigation, and here the main purpose was satisfying regulatory reporting obligations. Involving a lawyer or labeling a document does not by itself create privilege, although genuine privilege survives a limited waiver.
Against a backdrop of executive orders targeting diversity, equity, and inclusion (DEI) programs, anti-DEI shareholder proposals, and the post-SFFA v. Harvard legal landscape, companies face growing pressure to reassess their DEI initiatives. To navigate this environment, companies should assess their risk tolerance relative to peers and consider a comprehensive audit of existing DEI policies with counsel. They should also tie their programs to demonstrable business rationale, understand the perspectives of key stakeholders through surveys and listening sessions, maintain a consistent tone at the top, and establish a response team for potential public scrutiny, while monitoring evolving regulatory guidance.
Dodiya v. Franklin tested the limits of the safe harbors added in 2025 to Section 144 of the Delaware General Corporation Law. Those amendments can preclude equitable relief and eliminate damages claims in certain conflicted transactions that may involve insiders or a controlling stockholder by having it approved either by disinterested directors acting in good faith and without gross negligence, or by an informed vote of disinterested stockholders. In Dodiya v. Franklin, a company’s CEO leaked confidential valuation and process information to his father’s investment firm, which bought stock cheaply and then took the company private. The board continued to give the CEO access to deal materials and allowed him to attend a board meeting about the deal even after he recused himself, and despite the board’s knowledge of the leak. Despite this, the proxy statement stated he had not participated in the sale process after his recusal. In August 2026, the Delaware Court of Chancery found that the board acted with “reckless indifference” and that it was reasonably conceivable that the merger proxy statement contained a material misstatement, making both safe harbors unavailable. The safe harbor protection is real, but its availability depends on the board’s process and the accuracy of its disclosures.
In June 2025, the U.S. Supreme Court upheld a Texas law requiring websites where more than one-third of content is sexually explicit to verify users’ ages before granting access. The critical legal question was which First Amendment standard to apply. The Court chose the more lenient intermediate scrutiny rather than the strict scrutiny used to strike down similar federal laws in the early 2000s, reasoning that the law targets distribution of obscene content to minors and only incidentally burdens adults’ access to protected speech. The three-justice dissent argued strict scrutiny should apply and warned of a chilling effect on lawful speech. The ruling’s reach extends beyond traditional adult content sites to any platform (including social media) if one-third or more of the platform’s content could be deemed harmful to minors. With nearly half of U.S. states having already enacted similar laws, the decision is expected to accelerate that legislative trend. Privacy advocates have separately warned that mandatory age verification forces users to submit sensitive personal identification, raising data breach risks and potentially threatening the First Amendment right to browse the internet anonymously.
Texas overhauled its business organizations code last year through Senate Bill 29, part of a broader effort to make the state a more attractive home for companies looking beyond Delaware. One of the changes lets certain corporations, including publicly traded ones and other opt-in companies with more than 500 shareholders, adopt a bylaw requiring a shareholder to hold at least 3% of the company’s stock before bringing a lawsuit on the company’s behalf against its own directors or officers.
A federal court has now applied that provision, dismissing a derivative case against Southwest Airlines’ board because the plaintiff held far too little stock to clear the company’s 3% bylaw. The court also rejected the argument that a pre-suit demand letter sent before the new rules took effect counted as starting the proceeding. For companies weighing where to incorporate, the case is an early signal that Texas courts are giving the state’s new corporate litigation protections real effect.
Texas Governor Abbott signed House Bill 40, significantly expanding and refining the Texas Business Court just two years after its creation. Key changes include lowering the amount-in-controversy threshold from US$10 million to US$5 million across all case types, expanding substantive jurisdiction to cover intellectual property, trade secrets, and arbitration enforcement cases, clarifying that only business, commercial, or investment contracts may elect business court jurisdiction by agreement, authorizing transfer of pre-September 2024 cases by agreed motion, and tasking the Texas Supreme Court with establishing a jurisdictional framework and rulemaking procedures. The legislature also eliminated the sunset provision for unfunded court divisions, signaling the business court is a permanent fixture in the Texas legal system.
Texas Governor Greg Abbott signed Senate Bill 29, a sweeping overhaul of the Texas Business Organizations Code aimed at making Texas the “corporate law capital of America.” Key changes include codifying the business judgment rule for publicly traded corporations, creating a statutory framework for controlling shareholder transactions with special committee pre-approval procedures, allowing entities to waive jury trials in governing documents, narrowing books and records demands to exclude emails and text messages, imposing up to 3% ownership thresholds for derivative suits, eliminating mootness fees for disclosure-only supplements, and permitting alternative entities to fully eliminate fiduciary duties in their governing agreements.
Following an industry challenge to Texas Senate Bill 140’s new text marketing registration requirements, the Texas Attorney General submitted a detailed interpretation of the law agreeing that the registration requirements were not intended to apply to businesses that obtain prior consumer consent before sending marketing text messages. As part of a subsequent settlement, the Texas Secretary of State posted guidance on its website confirming that consent-based text senders are not required to complete the telemarketing registration process and agreed to formally request a published AG opinion reinforcing this interpretation. While this clarification significantly reduces the registration risk for businesses with proper consent practices, some litigation risk remains. Plaintiffs’ attorneys may still attempt to assert the law’s private right of action and other requirements of the law will continue to apply, such as quiet hours restrictions.
Texas amended its telephone solicitation and telemarketing law (known as the “mini-TCPA”) through Senate Bill 140, effective September 1, 2025, to require businesses sending marketing text messages to Texans to annually register with the Secretary of State, pay a registration fee, post a $10,000 security deposit, and make detailed disclosures about their business and planned solicitations. The law expands the definition of “telephone solicitation” to include text messages and creates de facto violations of the Texas Deceptive Trade Practices Act (which carries significant penalties including treble damages and a private right of action) for violations of existing text messaging consent and no-call list requirements. Several exemptions may limit applicability for established businesses, including carveouts for publicly traded companies, supervised financial institutions, nonprofits, and entities that have operated under the same name for at least two years and are messaging current or former customers, though the scope of the customer exemption is somewhat ambiguous.
Although AI-related patent filings have surged dramatically over the past two decades, patent litigation involving AI technologies has not yet kept pace, a trend the article suggests may mirror the delayed wave of smartphone patent litigation that followed the technology’s commercial growth. In this piece for Bloomberg Law, Sidley partner Alexis Cohen argues that AI companies should begin preparing now for increased future litigation by evaluating and strengthening their intellectual property protections, including patents and trade secrets, while also improving documentation, ownership records, employee agreements, and internal processes.
Reproduced with permission. Published May 21, 2026. Copyright 2026 Bloomberg Industry Group 800-372-1033. For further use, please visit: Bloomberg Industry Group copyright and usage guidelines.
England’s High Court has issued the UK’s first ruling in a copyright fight against an AI developer with an outcome that favors the AI industry. In Getty Images v. Stability AI, Getty (which licenses photos and video) alleged that Stability scraped millions of its images to train the Stable Diffusion image generator. During trial Getty dropped its main copyright claim because it could not show the training actually happened in the UK. Copyright is territorial, so no act in the UK means no UK infringement.
That left a narrower question: whether importing the already-trained model into the UK made it an “infringing copy” under the Copyright, Designs and Patents Act 1988. The court said no. A model’s weights are just numbers derived from statistics; they do not store or contain the underlying images, so supplying the model is not secondary infringement. Getty won only on a historic and limited trademark point about its marks appearing in outputs. The decision settles little about whether UK-based training would infringe, and Getty may appeal.
A stockholder of a Delaware e-commerce company sent a formal demand to inspect company books and records while the company was being acquired. The company objected, claiming the demand was too broad and lacked a proper purpose, but offered to negotiate a narrower production. The stockholder did not respond. The merger closed a week later, cancelling the stockholder’s shares, and the stockholder filed suit to enforce her demand 12 days after that. The Delaware court dismissed the case: under the state’s books-and-records statute, often called Section 220, you must actually be a stockholder on the day you file the lawsuit, not merely on the day you send the demand. Once the merger wiped out her shares, she no longer qualified.
The court also refused to excuse the delay on fairness grounds, noting the company had never agreed to produce anything nor promised a schedule, so nothing it did invited her to wait. The court left open, without deciding, whether a fairness exception could ever apply, and cautioned companies that stringing a stockholder along before closing could weaken that defense.
Attorney-client privilege is a cornerstone of effective legal risk management, but its application is nuanced — especially for in-house counsel. The privilege protects confidential communications between an attorney and a client made for the purpose of obtaining or providing legal advice. However, courts scrutinize claims of privilege, particularly when in-house counsel are involved or when communications comprise of both legal and business advice. The law governing privilege can vary significantly by jurisdiction; thus, it is important to seek the advice of counsel prior to any communications.
Key Considerations for In-House Counsel:
To maximize protection and avoid inadvertent waiver, legal teams and senior executives should keep the following in mind:
In-house counsel face extra scrutiny
Courts recognize that in-house counsel often wear multiple hats. Privilege will apply only where the primary purpose of the communication was to obtain or provide legal — not business — advice.
Privilege applies only to legal — not business — advice
Privilege attaches only to communications where the predominant purpose is legal advice, such as internal investigations to assess whether employees breached a contractual obligation, reviewing marketing materials for compliance with applicable law, or drafting and analyzing contractual language. Clearly distinguish legal analysis from business discussions, particularly in writing.
Confidentiality underpins privilege
Limit distribution of privileged communications to those who “need to know” and avoid including third parties unless necessary and protected by a recognized exception. This is especially important to keep in mind when discussing privileged information while working remotely. There are no exceptions for spouses, family, roommates, or neighbors.
Common-Interest Exception
For example, in California, generally the common-interest exception extends the privilege to communications between parties and their counsel relating to potential civil litigation provided that:
- The parties have some common litigation interest (a purely personal or business-oriented interest is insufficient); and
- The communications are made to further that shared legal interest.
This exception may also apply where parties maintain separate counsel but coordinate through a joint defense or litigation strategy.
Where it applies, the common-interest exception typically only protects communications involving counsel.
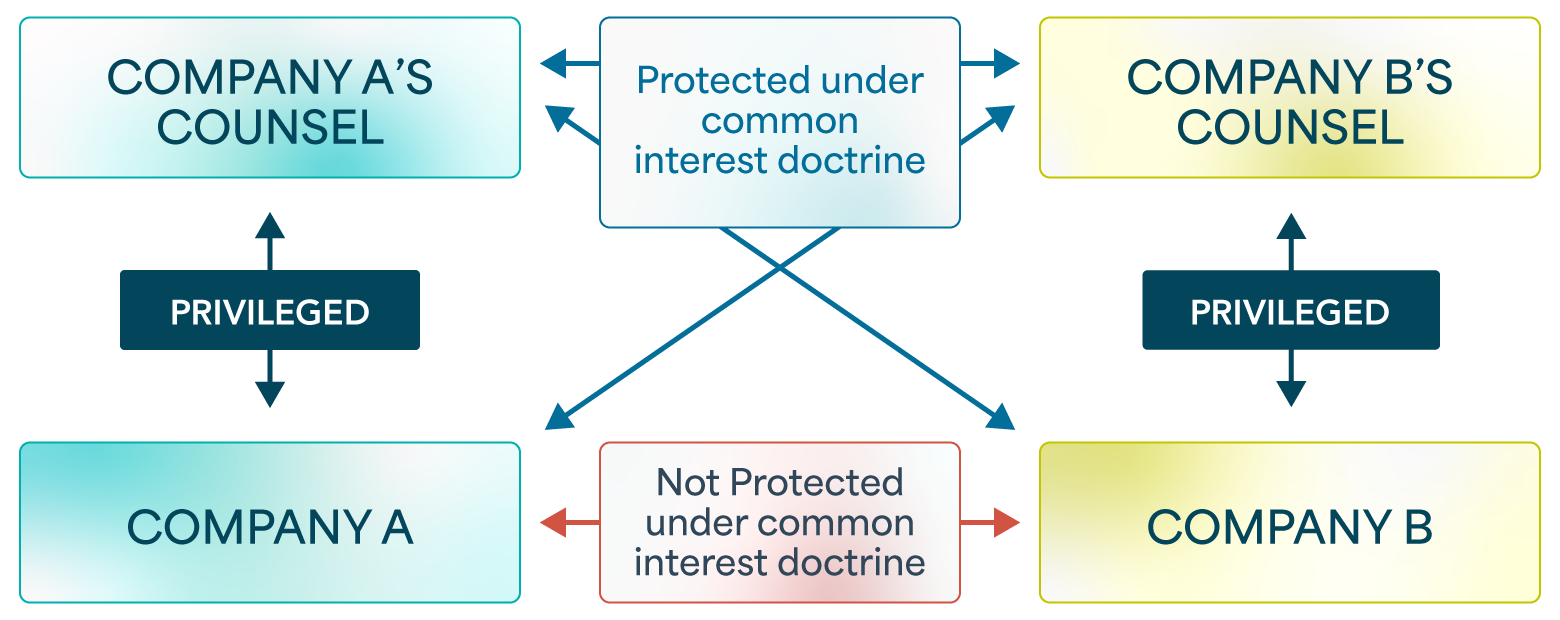
Do not assume privilege exists
Even if you believe a communication is privileged, write with the expectation that it could be reviewed by a court. Privilege does not necessarily extend automatically to subsidiaries or affiliates. Ensure formal retention and clear documentation when representing multiple entities or working with advisors. Additionally, the law governing privilege can vary significantly by jurisdiction; thus, it is important to seek the advice of counsel prior to any communications.
Labels help but don’t control
Mark emails or memos as “Attorney-Client Privileged” and “Confidential,” but remember: substance, not form, determines privilege. Where possible, clearly reference the legal advice sought or provided.
Be explicit in requests for legal advice
Directly address in-house or outside counsel, specify the legal issue, and avoid copying attorneys merely to shield a document.
Separate legal from business content
When communications blend legal and business matters, separate them or document the legal purpose clearly.
By proactively managing privilege, in-house counsel and executives can strengthen the protection of sensitive communications, preserve confidentiality, and reduce litigation risk.
President Trump’s December 11, 2025 Executive Order aims to protect American AI innovation from what it characterizes as overly burdensome state AI laws by creating a Department of Justice AI Litigation Task Force to identify and challenge problematic state regulations, conditioning federal Broadband Equity, Access, and Deployment (BEAD) Program funding on state AI policy alignment, directing the Federal Communications Commission (FCC) to consider preemptive federal AI reporting standards, and instructing the Federal Trade Commission (FTC) to clarify how Section 5 of the FTC Act applies to AI in ways that could preempt conflicting state laws. The Executive Order stops short of imposing the broad 10-year moratorium on state AI laws that was previously proposed in legislation, instead taking a more targeted approach that carves out state authority over child safety, AI infrastructure, and government AI procurement. The Executive Order also calls on Congress to enact a uniform federal AI framework.
Under Texas law, informal fiduciary relationships (which can theoretically arise from any personal or business relationship of special trust and confidence) are frequently claimed in litigation but almost never succeed. Two recent decisions illustrate the doctrine’s narrowing scope: in Pitts v. Rivas, the Texas Supreme Court rejected an informal fiduciary claim despite a decade-long personal friendship between an accountant and client, with a notable concurrence from Justice Huddle (joined by three justices) formally calling for the doctrine to be abandoned altogether. The Texas Business Court reached a similar conclusion in Tall v. Vanderhoef, dismissing an LLC minority member’s informal fiduciary claim because no special relationship of trust existed prior to and apart from the parties’ governing agreements. While the doctrine technically remains good law in Texas, courts continue to apply it with significant skepticism and practitioners should treat informal fiduciary claims as a high-risk, rarely successful avenue in business disputes
A founder-chief executive officer (CEO) whom the board no longer trusts may still hold a board seat, meaningful equity, and a dual-class voting block. A chief operating officer’s departure may activate a key-person provision in a venture debt facility before the company has aligned on a successor or a message. For later-stage private companies, an executive transition is rarely just an employment event: it can become a governance contest, a financing issue, an investigation, a cap-table negotiation, and a litigation risk at the same time. Below is a brief summary of some (but not all) key decisions and steps to consider when leadership changes hands and how to approach such change from inside the impacted organization.
Setting the Stage: Why the Nature of the Departure Drives Everything
Start by deciding what kind of event the company is actually managing: planned succession, negotiated exit, resignation, termination without cause, termination for cause, or an asserted resignation for good reason. These are not labels reserved for the separation agreement or the press statement. The characterization can control acceleration triggers, severance eligibility, notice and cure rights, release leverage, restrictive-covenant arguments, lender or investor notifications, and what the company can say to employees, investors, customers, and the market. An orderly succession may permit a staged handoff; an abrupt exit may require immediate access controls and a parallel fact investigation. Before anyone communicates, align the board, Human Resources (HR), finance, legal, and operations teams on the factual record and decision rights. Confirm the employment agreement, equity plan and award agreements, incentive arrangements, change-in-control terms, key-person provisions, and applicable policies. Labor-law compliance remains the baseline: assess discrimination, retaliation, whistleblower, wage-and-hour, final-pay, accrued-leave, benefits-continuation, and notice requirements, as well as any works-council or collective-bargaining obligations. Honor contractual payment and notice terms, and document the legitimate business rationale and decision process.
Governance and Board Dynamics: Beyond Simple Recusal
When a founder-CEO is also a director, holds protective provisions, or controls a dual-class voting block, removing the executive from an operating role does not necessarily change board composition or voting control. Separate the board’s power to remove an officer from the stockholders’ or, where permitted by applicable law and the governing documents, the board’s power to remove a director. Confirm who can call the meeting, what quorum and voting thresholds apply, whether an investor designation or protective provision is implicated, and whether a voting agreement, charter provision, or side letter constrains the path. A clean termination process can still fail if the company treats a governance problem as an HR action.
When the departure is tied to an internal investigation, run three tracks deliberately: protect facts and privilege; decide whether interim controls or termination for cause are warranted; and assess whether a negotiated separation creates value without compromising the investigation. Use an independent committee or outside counsel when the board’s independence is in question, define the client and privilege purpose at the outset, and keep business, HR, and communications teams on a need-to-know basis.
Investor and Stakeholder Dynamics: When a Departure Becomes a Capital-Structure Event
Credit agreements, venture debt facilities, preferred-stock documents, investor side letters, and material commercial arrangements may contain key-person provisions that require notice, consent, a replacement plan, or a cure period, and may turn silence into a default. The same analysis should cover customer, regulatory, and financing diligence processes already underway.
A departing stockholder-executive may retain board-observer status, inspection or information rights, rights under a voting agreement, or a contractual right to receive notices even after system access is revoked.
Investor relations should be sequenced, not improvised. Decide which directors, lead investors, lenders, and major stakeholders need a direct call, who will make it, and what they need to know about interim leadership, business continuity, financing impact, and customer coverage. Communicate early enough to avoid surprise but only after authority, facts, and the core message are aligned. A single factual narrative is more valuable than a detailed explanation of disputed allegations; document what is being said and to whom, and avoid allowing a departing executive or an investor to define the story through a leak.
Bring the director and officer (D&O) broker and carrier into the analysis early. Confirm notice obligations, extended-reporting or tail coverage, indemnification and advancement rights, and whether the facts could trigger a conduct exclusion or a coverage dispute. An allegation of misconduct can affect both the company’s and the departing executive’s coverage, especially if the company makes admissions or settles before giving the carrier a meaningful opportunity to respond. Separation documents should preserve applicable indemnification and cooperation arrangements, allocate responsibility for notices, and avoid language that unintentionally prejudices coverage.
Negotiation Strategy: Beyond the Severance Check
Map the executive’s priorities – equity treatment, exercise window, health coverage, title or reference, timing, transition, advisory role, indemnification, and departure message – then package concessions rather than negotiating one item at a time. At the same time, separate contractual entitlements from discretionary consideration and validate every term against the employment agreement, equity documents, plan rules, wage laws, benefits rules, and tax constraints.
Departure messaging is another bargaining instrument: agree who speaks, when the statement is issued, how the role is described, what reference is provided, and whether mutual non-disparagement is conditioned on performance. If the parties cannot align, have a short, factual unilateral message ready rather than letting the dispute write it.
Acceleration disputes usually turn on whether the termination was “without cause,” whether the executive established “good reason” and satisfied notice-and-cure requirements, and who had authority to make the decision. That characterization can cascade into vesting, exercise deadlines, repurchase price, dilution, withholding, and the executive’s leverage in a release. Also ask how separation interacts with drag-along, tag-along, transfer restrictions, voting agreements, and investor-consent rights. A departing executive who remains a significant stockholder may still be able to block, participate in, or complicate a sale. Coordinate any repurchase or recovery with wage laws and the governing documents; do not assume the company can simply withhold amounts otherwise owed.
Litigation Risk and Enforcement Strategy: Preserve Optionality Before You Escalate
Test the company’s legitimate protectable interest, the likelihood of irreparable harm, the evidence of competitive risk, and whether enforcement would accelerate disclosure or make the former executive a sympathetic witness. A targeted confidentiality, customer non-solicitation, intellectual-property, or trade-secret remedy – or carefully structured garden leave – may preserve more value than an overbroad non-compete.
A measured demand letter can identify continuing obligations, request return or deletion of information, preserve the company’s position, and invite a controlled resolution. A tolling agreement can protect limitations periods while the parties investigate, and targeted forensic imaging can preserve devices, cloud records, access logs, and transfer history before evidence disappears. Use legal holds, a defensible collection protocol, and an appropriate forensic vendor; overcollection, careless accusations, or an unlawful review of personal data can create the next dispute.
Before finalizing the departure, stress-test whistleblower and retaliation theories. Build a chronology of complaints, investigations, performance actions, protected disclosures, and decision-maker involvement; confirm that the stated rationale is supported by contemporaneous evidence and would have produced the same result absent protected activity. Keep the investigation independent where necessary, avoid labeling allegations as established fact, and ensure the separation agreement and communications do not restrict legally protected reporting. The goal is not merely to win the severance negotiation; it is to prevent the departure from being recharacterized as retaliation after the executive leaves.
Sequencing the Transition: Order of Operations Matters
First, preserve authority, facts, and business continuity: confirm the board action, legal hold, key-person notices, interim coverage, and immediate safety or access needs before the executive is told, where the risk profile permits. In parallel, build two calendars, one for the contested legal and negotiation track and one for the operating track, covering notice, severance and equity modeling, communications, customer and investor outreach, access changes, successor coverage, and knowledge transfer. After notice, execute access changes, device preservation, written reminders, and a controlled handoff in a coordinated sequence. Nonessential courtesy items, such as a reference format or advisory title, can wait until core rights and preservation steps are secured.
Identify mission-critical relationships, approvals, systems, customer commitments, product decisions, financial processes, and pending disputes; assign an owner and a deadline for each item. Use supervised sessions, written inventories, clean-room access, and time-boxed cooperation rather than giving a departing executive broader access simply to make the handoff easier. Decide whether a successor starts before the final day, whether an interim leader fills the gap, which board, customer, investor, and employee communications happen, and who signs off on completion. Document board resolutions, the termination or separation agreement, intellectual-property assignments, release, repayment or repurchase terms, cooperation obligations, successor agreements, authority matrices, and restrictive-covenant terms. Treat the paperwork as an operating control: it must match the actual sequence and must not promise rights the board has not approved.
Trade Secrets and Confidential Information: A Strategic Approach
When facts permit, conduct forensic triage before the departure conversation. Under an appropriate legal hold and applicable privacy and employment rules, identify high-value repositories, privileged files, source code, customer lists, pricing, financing materials, personal-device connections, and access logs; preserve targeted images and logs rather than taking an indiscriminate data grab. Build a trade-secret inventory and identify what makes each item secret: limited access, labeling, contractual controls, training, or technical safeguards. If the contract and applicable law permit, garden leave can serve as a cooling-off tool: maintain pay and benefits while suspending operational access and competitor contact instead of forcing an immediate binary choice between active access and termination.
Remind the executive in writing of confidentiality, intellectual-property, cooperation, non-solicitation, and other post-employment obligations, while preserving applicable indemnification and privilege boundaries. If the executive retains an advisory role or stockholder or observer rights, use segregated, time-limited access and a designated channel rather than blanket credentials. For a competitor departure, conduct a documented risk assessment, monitor only where lawful and disclosed, and escalate suspicious transfers; account for personal data, cross-border rules, and bring your own device (BYOD) before collecting or reviewing content.
A federal judge in Manhattan ruled in May 2026 that the government could not blame ChatGPT for its own decision to terminate more than 1,400 federal grants that the tool had flagged as related to diversity, equity, and inclusion. Staff fed short grant descriptions into the model and asked whether each one related to DEI, then acted on the answers without reading the underlying applications, without defining what DEI meant, and without a single instance of a reviewer disagreeing with the tool. The Court treated the prompts and outputs as discoverable evidence, noting that a decision-maker who chooses a tool cannot escape responsibility by blaming it.
For any company building generative or agentic AI into core business functions, the practical points are about governance: who is allowed to write prompts, whether reviewers have the expertise and authority to override an output, and whether the process is documented. AI-generated records can later surface in litigation or regulatory review, accurate or not.
By the time a venture-backed company reaches its mid to late stages, its board is usually built out of overlapping interests. Directors are affiliated with the funds that led earlier rounds, a founder may hold a large voting block, and executives and investors alike see a steady stream of opportunities, some of which look a lot like the company’s own roadmap. Generally, Delaware corporate law treats these relationships not as misconduct but as a process question. Most recently, Delaware corporate law received meaningful codified updates to its conflicted transaction rules and the key in evaluating such transactions remains to ensure that process follows the most recent developments in the law.
Loyalty Sets the Baseline
Directors and officers of a Delaware corporation owe fiduciary duties of care and loyalty to the corporation. The duty of loyalty bars a fiduciary from using a position of trust to advance personal interests at the corporation’s expense, and it is the source of both bodies of law discussed here. A conflict of interest does not by itself make a transaction wrongful; what it changes is the standard of judicial review if the transaction is later challenged. A conflicted transaction that has not been properly cleansed risks review for entire fairness, the most demanding standard under Delaware law, while a transaction that satisfies the statutory safe harbors described below is insulated from fiduciary duty damages and equitable relief.
Conflicted Transactions Under Section 144
DGCL Section 144 gives boards a set of alternative cleansing paths. An act or transaction involving a conflicted director or officer qualifies for the safe harbor if any one of the following is true: the material facts of the interest and the transaction are disclosed or known to the board or a committee, and a majority of the disinterested directors approve it in good faith and without gross negligence; the transaction is approved or ratified by an informed, uncoerced, affirmative vote of a majority of the votes cast by the disinterested stockholders; or the transaction is fair to the corporation and its stockholders. However, if a majority of the board is conflicted, the director-approval route must run through a committee of at least two disinterested directors.
Controlling stockholder transactions have their own rules, and the statute defines who is a controller: a person who owns or controls a majority of the voting power, has the right to cause the election of a majority of the board, or holds at least one third of the voting power together with the power to exercise managerial authority over the corporation’s business and affairs. On a maturing cap table, that can describe a founder with high-vote stock or, in some circumstances, a lead investor, and stockholders acting together under an agreement or understanding can constitute a control group. A controlling stockholder transaction (other than a going private transaction) qualifies for the safe harbor if it is approved or recommended by a committee of at least two disinterested directors with express authority to negotiate and to reject the transaction, or if it is conditioned on and receives an informed, uncoerced majority-of-the-minority vote. Only a going private transaction requires both protections, a deliberate departure from prior case law, under which both were generally required for a controller transaction to earn business judgment review.
The statute also defines disinterestedness. A disinterested director is one who is not a party to the transaction and has no material interest in it or material relationship with a person who does, with materiality keyed to whether the director’s objectivity would reasonably be expected to be impaired. Directors of exchange-listed companies also receive a heightened presumption of disinterestedness if the board has determined they are independent under exchange rules, a provision that becomes relevant after an IPO.
The Corporate Opportunity Doctrine
The corporate opportunity doctrine answers a different loyalty question: when a business opportunity belongs to the corporation rather than to the fiduciary who learned of it. A director or officer of a Delaware corporation may not take an opportunity for personal benefit if the corporation is financially able to undertake it, the opportunity falls within the corporation’s line of business and would be of practical advantage to it, the corporation has an interest or reasonable expectancy in it, and taking it would place the fiduciary’s self-interest in conflict with the fiduciary’s duties. The Delaware Supreme Court has emphasized that the factors are weighed together and that no single factor is dispositive.
In the venture ecosystem, fund-affiliated directors see deal flow across an entire portfolio, and founders and executives routinely encounter ideas adjacent to the corporation’s business. A fiduciary who takes an opportunity that a court later decides belonged to the corporation faces disgorgement of the opportunity or its proceeds. However, a fiduciary who presents the opportunity to the board and obtains a rejection from disinterested directors gains the benefit of a safe harbor, mitigating the risk of an after-the-fact judicial determination that the opportunity was usurped. Presentation is not legally required, but it creates a clean contemporaneous record, and the rejection should be clearly documented in the minutes.
Advance Waivers Under Section 122(17)
Delaware also permits much of this to be resolved in advance. Section 122(17) of the DGCL authorizes a corporation to renounce, in its certificate of incorporation or by action of its board, any interest or expectancy in specified business opportunities or specified classes or categories of business opportunities, whether presented to the corporation or to one or more of its officers, directors, or stockholders. Waivers of this kind are common in venture capital investments, where a firm and its designees may hold positions and board seats across a sector, and it is recommended to build them into the certificate of incorporation at the time of investment (which is consistent with the NVCA model certificate of incorporation). Note that such a waiver addresses only the corporate opportunity doctrine, not confidentiality. Accordingly, funds holding positions in competing companies should maintain information screens and avoid seating the same designee on the boards of competitors.
That said, advance waivers may not be an absolute shield to all issues arising out of potential corporate opportunities. Although details are scant as of the time of writing, and we expect to publish more detailed analysis once information becomes available, in August of 2026 the U.S. Department of Justice has been investigating certain venture capital firms with partners serving on boards of competing companies, potentially raising antitrust concerns, separate from the corporate law concepts of corporate opportunity.
DO’S & DON’TS:
Board Process for Conflicted Transactions
DO: Surface conflicts early and choose the cleansing path before approval. Disclose all material facts about the fiduciary’s interest and involvement, obtain approval from a majority of the disinterested directors acting in good faith and without gross negligence, and use a committee of at least two board-determined disinterested directors whenever a majority of the board is conflicted.
DON’T: Treat a conflicted deal as either automatically prohibited or automatically safe because the terms feel like market. Without disinterested director approval, a qualifying disinterested stockholder vote, or provable fairness, the transaction and the fiduciaries remain exposed.
Controlling Stockholders and Investor Directors
DO: Test whether a founder, investor, or group acting together is a controlling stockholder or control group under Section 144(e) before structuring any related party transaction. For controller transactions, use a fully empowered committee of at least two disinterested directors or a conditioned majority-of-the-minority vote, and use both for a going private transaction.
DON’T: Assume control requires majority ownership; one third of the voting power plus managerial authority can suffice. And do not rely on a stockholder vote to cleanse a controller transaction unless the deal was conditioned on disinterested stockholder approval by its terms when submitted for the vote.
Corporate Opportunities
DO: Adopt a simple protocol: fiduciaries promptly disclose opportunities arguably within the corporation’s line of business, the board or its disinterested members decide whether the corporation will pursue them, and any rejection is documented in the minutes before the fiduciary proceeds.
DON’T: Let a director or officer pursue such an opportunity quietly, or with the corporation’s resources, personnel, or information. Informal assurances from management are not a substitute for board-level disclosure and a documented rejection.
Waivers and Information Hygiene
DO: Consider a Section 122(17) waiver in the certificate of incorporation tailored to fund-affiliated directors and stockholders, revisit its scope at each financing, and pair it with confidentiality screens where investors hold competing positions.
DON’T: Seat the same designee on the boards of competing portfolio companies or treat a waiver as permission to share the corporation’s confidential information.
A Delaware Court of Chancery post-trial opinion in Holzbaur v. Trolley Square Hospitality, LLC serves as a cautionary tale about imprecise LLC agreement drafting. The plaintiff believed he was a “cash contributing member” with irremovable status, but contradictory language in the agreement led the court to rely on extrinsic evidence (including emails, pre-formation conversations, and drafting history) to find he was actually a “sweat equity” member subject to removal at will. The case underscores that the flexibility of the LLC form carries drafting responsibility: internal inconsistencies open the door to costly litigation and invasive discovery, and ambiguities will be resolved based on the parties’ actual intent, not favorable contract language.
In Fortis Advisors, LLC v. Stillfront Midco AB, the Delaware Supreme Court strictly enforced an arbitration clause in a merger agreement, finding that a seller’s bad faith claims regarding earnout manipulation fell within the alternative dispute resolution (ADR) provision’s scope because they were fundamentally a dispute about the calculation of the earnout. The court looked at the substance of the claims, concluding that “why” the earnout calculation was wrong cannot be severed from an arbitration clause covering calculation disputes. The decision is a strong reminder to dealmakers to precisely delineate which disputes are reserved for courts versus arbitration, and to draft ADR provisions with enough specificity to avoid costly threshold litigation over arbitrability.