All Articles

As generative AI becomes increasingly accessible and pervasive, many companies are experimenting with these tools to draft full legal agreements. For start-ups and businesses with limited resources, the appeal is obvious: AI can produce contracts quickly and at a fraction of the cost of traditional legal drafting. What once may have required days of attorney time and high legal fees can now theoretically be generated in minutes with a simple prompt.
While this efficiency is attractive, it comes with significant risks. AI-generated agreements frequently contain significant issues that ultimately make them unusable. Unlike an experienced attorney, AI lacks legal judgment, contextual understanding, and knowledge of specific client needs. It can generate provisions that appear polished on the surface but collapse under scrutiny.
One recurring issue is the inclusion of multiple conflicting provisions. For example, a recent AI-generated supply agreement included three different payment mechanisms for the same transaction: upfront payment, milestone-based installments, and payment upon delivery after invoicing. With three competing payment obligations for a single transaction, the contract leaves the payor guessing and sets the stage for potential disputes.
Another problem is language that reads like legal boilerplate but is, in fact, incoherent or legally meaningless. AI may generate complex wording that mimics the tone of a lawyer’s drafting, but it lacks the precision required in contract language. This can make agreements unnecessarily confusing and difficult to interpret. For example, a recent AI-generated commercial contract included the following dispute resolution provision:
“Any dispute, controversy, or claim arising out of or relating to this Agreement, or the breach, termination, or invalidity thereof, shall be finally settled by arbitration in São Paulo, Brazil, in accordance with the rules of the American Chamber of Commerce, Canadian Chamber of Commerce, or other mutually agreed renowned Chamber of Arbitrations.”
This dispute resolution clause has several problems. First, it does not identify the exact set of rules governing arbitration proceedings between the parties. More importantly, there are no such rules of the “American Chamber of Commerce” or the “Canadian Chamber of Commerce” and it is unclear what would be considered a “renowned Chamber of Arbitrations.” Finally, it is highly unlikely that parties resolving a dispute in Brazil would choose to apply American or Canadian-based arbitration rules. An attorney with even minimal experience in drafting arbitration provisions would not make these errors.
The underlying issue is that AI generates text based on patterns, not legal reasoning. It predicts what “sounds” like a contract without understanding enforceability, legal doctrine, or commercial practicality. Given the risks, companies should treat AI-generated contracts with caution. As such, attorney review remains essential to make sure agreements are clear, consistent, and tailored to the business’ needs.
Artificial intelligence (AI) continues to reshape healthcare delivery, particularly in diagnostics, imaging, and care coordination. For established healthcare platforms seeking to integrate innovative capabilities, effective transactions are not always single-step acquisitions. Phased relationships, beginning with commercial alignment and structured with the potential for full-scale integration, can provide a disciplined path to innovation.
For technology and life sciences transactions counsel, this raises a critical question: How can parties structure an initial collaboration to accelerate deployment while preserving long-term strategic optionality?
Phase I: Exclusive Commercial Alignment With Strategic Investment
In the healthcare sector, initial alignment frequently takes the form of an exclusive or field-limited license coupled with a minority equity investment. This structure enables a healthcare platform to secure access to differentiated technology, influence product development, and evaluate performance in a live clinical setting while mitigating integration and regulatory risk.
The effectiveness of this model turns on careful coordination in drafting foundational agreements.
Exclusivity
Exclusivity must be defined with intent and precision. In healthcare technology transactions, scope may be tied to specialty, site of care, modality, patient population, geography, or some combination of the foregoing. Performance milestones often are incorporated to ensure continued development and commercialization progress. Overly broad exclusivity may constrain a developer’s growth and create valuation tension; overly narrow drafting may undermine the strategic value of the arrangement. The objective is to balance long-term alignment with operational flexibility. Of course, in an AI context, parties need to address whether exclusivity extends to future model iterations, retrained versions, or algorithmic enhancements; consideration must be given to the dynamic nature of machine learning systems.
Intellectual Property and Data Rights
Healthcare collaborations frequently involve a convergence of technology developers and data-rich platform organizations. Clear delineation of background intellectual property, derivative works, algorithm improvements, and data usage rights is essential. Platforms typically seek rights to deploy and refine technology across their networks and express concerns around the control and use of their data; developers seek to preserve core intellectual property ownership and the integrity of their models having been trained with partner data. Sophisticated collaborators increasingly distinguish between ownership of model weights, fine-tuned models, embeddings, and generated outputs. Platforms also may be concerned with limiting use of their input data to improve only customer-specific instances rather than also generalized models. These provisions must be drafted with careful attention to the Health Insurance Portability and Accountability Act of 1996, state privacy regimes, cybersecurity obligations, and evolving regulatory scrutiny of AI-enabled tools.
Several intellectual property questions are distinctive in the AI context. First, where a party’s product is a layer built on a third-party foundation model (commonly referred to as a “wrapper”), the scope of any exclusivity grant requires careful scrutiny. The underlying model weights may remain owned and broadly licensed by the third-party foundation model provider. What a wrapper may practically protect is the specific configuration, fine-tuning, and proprietary data contributed by the parties; however, it likely cannot fence off the foundational capabilities beneath. Exclusivity in this context protects differentiation, not the underlying foundation model.
Second, ownership of AI-generated output remains legally unsettled, and third-party platform terms of use continue to shift in ways that increase that uncertainty. Current copyright doctrine in most jurisdictions requires human authorship; outputs produced autonomously by a model may provide no copyright protection at all. In practice, many organizations treat proprietary prompts, fine-tuning approaches, retrieval architectures, and workflow integrations as confidential know-how rather than relying on copyright protections in the outputs themselves. This approach can be effective, but trade secret protection is contingent on maintaining secrecy and on contractual controls that prevent disclosure. Strategic agreements governing AI development should address both the allocation of any rights that do arise as well as the confidentiality obligations, access controls, and use and disclosure restrictions necessary to sustain appropriate trade secret protection.
Third, background intellectual property carries additional complexity when applied to AI development. A developer’s model may incorporate vast quantities of third-party content, potentially including works subject to copyright claims or contested licensing. Training data provenance and any unlicensed works used in the development or subsequent retraining of a model represent material and ongoing diligence considerations. Parties collaborating on the development or deployment of a model should conduct appropriate diligence into training data lineage and should seek representations, warranties, and indemnities addressing third-party intellectual property infringement claims flowing from the model’s underlying composition.
Investment and Governance
A minority equity investment can accompany the commercial arrangement, aligning incentives and providing capital for continued development. Effectively structured governance rights, such as board observation rights, information rights, and other protective provisions, can provide strategic visibility without creating unintended control or regulatory implications. Coordination between the commercial agreement and the investment documents is critical, particularly with respect to transfer restrictions and change-of-control provisions. Moreover, AI governance may extend to oversight of model validation, change management processes, and any regulatory filings associated with algorithm modifications.
At this stage, sophisticated parties also frequently incorporate structural mechanisms that preserve a potential path to acquisition while maintaining flexibility for both parties.
Phase II: Commercialization Proving Grounds
The initial commercial phase often functions as live diligence. The healthcare platform gains insight into clinical adoption, workflow integration, model performance, regulatory positioning, and scalability. This operational visibility informs valuation and integration planning should the relationship mature. This phase can also serve as a period to assess real-world performance drift, explainability, robustness across diverse cohorts, and the sufficiency of monitoring systems required for ongoing compliance.
To preserve optionality for a transition toward a future acquisition, parties often incorporate structural tools with respect to equity, such as rights of first refusal or first offer, exclusive negotiation periods, call options, prealigned valuation frameworks, or some combination of the foregoing. Drag-along and tag-along rights associated with the equity may also be calibrated with a future acquisition scenario in mind. These mechanisms should be drafted with attention to enforceability and regulatory constraints. Early coordination among corporate, regulatory, and competition counsel can materially affect downstream optionality.
Phase III: Acquisition and Integration
If the collaboration demonstrates sustained strategic value, a full acquisition may enable a deeper operational integration and broader commercialization as well as enhance the platform’s market differentiation.
At this stage, issues addressed during the initial licensing phase assume heightened importance. Clear chain of title for intellectual property, documented rights to data and improvements, regulatory compliance history, and alignment across commercial agreements are central to confirmatory diligence. Particular scrutiny is given to training data lineage, model documentation, audit trails demonstrating controlled updates, and explainability materials required for U.S. Food and Drug Administration or equivalent regulatory submissions. Retention and incentive arrangements for founders, developers, and technical personnel often become critical to preserving innovation postclosing.
If lifecycle planning is embedded in the original agreements, the acquisition process typically becomes more efficient. Change-of-control consequences are understood, equity positions are aligned, and commercial rights do not require fundamental restructuring. The transaction can therefore focus on valuation, integration strategy, and long-term growth.
Deliberate Deal Architecture
As technology-enabled innovation continues to transform healthcare delivery, staged collaborations are likely to remain a defining feature of strategic transactions. A phased approach, beginning with commercial alignment and investment while preserving a clear path to integration, allows organizations to validate technology in practice before committing to full-scale acquisition.
For technology and life sciences transactions counsel, the task is not merely to document a license or negotiate a purchase agreement. It is to architect a relationship that accommodates immediate commercialization and future strategic flexibility within a highly regulated environment. Thoughtful lifecycle structuring at the outset can materially shape the trajectory, and ultimate success, of the deal. As AI becomes more deeply embedded in clinical workflows, deal architecture increasingly must anticipate issues such as ongoing model governance, regulatory obligations tied to adaptive algorithms, and safeguards around the responsible use of patient-derived data — all core components of strategic value and risk.
After a US$750 million acquisition, the parties ran the usual post-closing true-up that adjusts the price based on the target’s actual financials at closing. It turned out the seller had misapplied a revenue-recognition accounting standard in its pre-closing books, and once the standard was applied correctly the buyer owed roughly US$38.3 million more. The buyer paid, then sued separately for indemnification, arguing the seller had promised its financial statements complied with accounting standards and that promise was false. The Delaware Court agreed and let the buyer recover the extra payment.
The Court rejected the seller’s arguments that the buyer should have caught the error in due diligence, that the claim belonged in the earlier case, or that a contract clause barring double recovery blocked it. Diligence is not an audit, the claim was not ripe until the true-up concluded, and the anti-duplication clause was meant to prevent collecting twice, not to eliminate indemnity claims. The Court determined that a price true-up fixes the number, but does not by itself decide who bears the cost of an inaccurate representation.
Several U.S. treaty partner jurisdictions have recently become aggressive in extending their taxation rights to cross-border acquisition transactions and the movement of assets, such as intellectual property. As a result, multinational companies should consider seeking advance unilateral or bilateral advance pricing agreements (also referred to as “APAs”) to resolve potential disagreements with foreign tax authorities and avoid lengthy and expansive audits and litigation proceedings.
What are “APAs”?
Commonly, following an acquisition of a foreign company by a U.S.-based multinational company, certain IP assets of the foreign target may need to be integrated with such company’s other operating assets to better align the ownership of IP assets with such company group’s operating structure, functions, other assets, and risks. Such an alignment of assets could involve the license, sale, or transfer of IP to the U.S. parent company or to another member of the multinational company group located in a jurisdiction different than that of the target. A cross-border transfer of assets could result in income recognition based on the value of the assets being transferred.
An APA is an agreement between a multinational company and a taxing authority or authorities regarding the transfer pricing methodology, valuation, and pricing of assets and certain transactions. A bilateral or multilateral APA (which involves the multinational company and two or several tax authorities, respectively) provides a non-adversarial alternative to resolving potential cross-border transfer pricing disputes, among many other benefits. Furthermore, the IRS is expected to be more likely to support valuation methodologies and adjustments that are based on acceptable international tax principles and valuation methodologies. The IRS’s support of a company’s valuation methodology in an APA process could be helpful in a dispute or litigation with a treaty partner jurisdiction in support of a company’s position. As a result, a bilateral or multilateral APA process provides an opportunity to set the stage and level the playing field with the treaty partner country(ies). A bilateral or multilateral APA may be a viable alternative to consider for both treaty partners (including Canada, Germany, India, Israel, Japan, Korea, Switzerland, and others) and other jurisdictions.
As a primary benefit, a bilateral or multilateral APA could eliminate the need for uncertain tax position reporting and provide for penalty protection. It would also help parties avoid repetitive tax and transfer pricing audits; limit tax authorities’ ability to change transfer prices retroactively; allow parties to manage transfer pricing real-time (rather than responding to audits years later); and mitigate the risk, cost, and burden of an audit or potentially harmful tax litigation in the U.S. and in the treaty partner jurisdiction. Other benefits may include the suspension of current tax audits or assessments relating to the transactions covered by the bilateral or multilateral APA negotiations until the APA process has been concluded, which could take several years.
For instance, recently at least one tax jurisdiction has gone so far as to argue on several occasions that the value of a target company’s IP could be higher than the entire purchase price paid to acquire such target company. The argument has been that, surely the buyer has taken into account the tax cost associated with moving the IP following the acquisition and, thus, discounted the purchase price paid for the target company and all of its assets, including its IP. Such a result, in the absence of an APA, can have a significant effect on deal structure, outcome, and consideration if not addressed in advance.
While the taxing authorities and the multinational company are not obligated to reach an agreement, they are generally required to try to reach a mutual agreement pursuant to the applicable income tax treaty, including relevant provisions for the relief from double taxation and mutual agreement procedure.
In a welcome development in the U.S., the IRS released additional guidelines on the IRS’s Advance Pricing and Mutual Agreement Program (APMA), a program that looks to identify multinational companies and matters early in the process that are more likely to successfully reach an APA resolution based on the facts at issue. Multinational companies can contact APMA for a pre-submission review and receive a preliminary opinion on whether to proceed with the APA process within just a few weeks of submitting a pre-filing memo and providing additionally requested information.
APMA considers a number of factors, including: the significance of the transaction; the probability that transfer pricing compliance will be significantly enhanced by engaging with the treaty partner; the scope, materiality, and complexity of the company group-covered transactions in the U.S.; whether there is an actual or potential transfer pricing dispute that would be most efficiently resolved through a bilateral or multilateral APA based on the APMA’s experience; country-specific strategy considerations; and the input of the treaty jurisdiction regarding the APA.
In addition to transactions involving IP assets, a bilateral or multilateral APA can cover the provision of services by a non-U.S. entity, the provision of services by a U.S. entity, sale of tangible property into and from the U.S., use of intangible property by a U.S. entity and by a non-U.S. entity, and other transactions. In the majority of “APAs”, the covered transactions involve numerous business functions and risks.
The Delaware Court of Chancery dismissed a stockholder suit claiming that directors of B. Riley Financial breached their fiduciary duties by failing to catch problems with an investment that later went bad. The suit was framed as a Caremark claim, the label Delaware uses for lawsuits arguing that a board failed to conduct oversight. The Court reaffirmed why those claims are so hard to win: a board’s oversight duty is aimed at the company’s own internal compliance and risk systems, not at policing misconduct by outside parties the company does business with, even where the company has significant money on the line. A failed investment, on its own, is not evidence of bad faith, and stockholders cannot repackage hindsight criticism of a bad bet as a breach of duty. Delaware courts scrutinize process, meaning they evaluate whether the board informed itself and had systems in place, rather than whether that process led to a good outcome.
When allegations of corporate misconduct surface, one of the first questions companies may face is who should oversee the response. In some circumstances, an investigation led by management or in-house counsel may be appropriate. But allegations involving senior executives or directors, mission-critical compliance risks, or questions about management’s independence may require the board — often through an independent committee — to take a more active role.
In a new article for Reuters Practical Law, Sidley partner Holly J. Gregory examines when a board-driven investigation may be warranted and how boards can structure those investigations to withstand scrutiny from regulators, prosecutors, shareholders, and courts.
The article also considers recent Delaware decisions addressing directors’ responses to compliance red flags and highlights practical considerations for board-led investigations, including committee independence, investigative scope, preservation, privilege, documentation, whistleblower protections, self-disclosure, reporting, and remediation.
A Delaware Court of Chancery decision in Siegel v. Morse reaffirmed that courts will not entertain challenges to advance notice bylaws absent an actual, existing dispute. Even after the Delaware Supreme Court’s Kellner decision raised the bar for facial validity claims, the plaintiff attempted to reframe his challenge as an “as-applied” one, but the court found no ripe controversy since no stockholder had expressed an intent to nominate directors. The decision signals that bylaw litigation must be grounded in a real, concrete controversy and that generic concerns about defensive board behavior are insufficient without an active proxy contest or nomination dispute.
In April 2026, California’s Department of Motor Vehicles released final rules governing how self-driving vehicles are tested and deployed in the state, capping more than a year of drafting and public comment. The rules separate testing from broader commercial deployment and set up three staged permits: testing with a safety driver, testing with no driver, and full deployment. Most manufacturers must log at least 50,000 autonomous miles before each step up, with a lower 10,000-mile threshold for low-speed vehicles, and a much higher 500,000 miles for heavy trucks, which became eligible in California for the first time. Applicants must also submit a detailed safety case explaining why the vehicle is safe, which the DMV may review with outside experts.
Other changes include a new traffic-violation notice police can issue, triggering 24- or 72-hour reporting deadlines; required first-responder interaction plans and prompt responses to emergency geofencing requests; and training and licensing standards for remote drivers and remote assistants. Large passenger buses remain ineligible, apart from a narrow exception.
Many Delaware-incorporated companies include provisions in their corporate charters or bylaws requiring that stockholder lawsuits be brought in Delaware’s Court of Chancery — a court that decides cases before a judge, with no jury. This creates a tension with California law, which strongly guarantees the right to a jury trial and has a broad “long arm” statute that can pull disputes into California courts even when a company has chosen a different forum. A minority stockholder who was a California resident sued EpicentRX (a Delaware corporation) in California court. The lower courts refused to enforce the Delaware forum selection clause, reasoning that sending the case to Delaware would effectively strip the plaintiff of her California jury trial rights. The California Supreme Court reversed, holding that a forum selection clause is not unenforceable simply because it requires parties to litigate in a jurisdiction that does not provide the same jury trial right as California. The court reasoned that California’s strong public policy favoring jury trials applies to proceedings in California courts, not to courts in other states. It further reasoned that a forum selection clause determines where a dispute is litigated, not how, so it does not constitute a prohibited waiver of jury trial rights. The decision aligns California with the majority of states that enforce Delaware forum selection clauses, reinforcing the ability of Delaware-incorporated companies to channel stockholder disputes to Delaware’s specialized corporate court.
The Delaware Court of Chancery recently provided a powerful reminder of the Court’s equitable purpose, and how it will not countenance bad faith or duplicity. In Ghatty v. Mudili et al., three board members of a five-member board voted at a special board meeting to remove the remaining two directors from their officer positions, and later sued under 8 Del. C. § 225 to seek confirmation that the two directors had been validly removed from their officer roles. The Defendants challenged their removal on a number of grounds. The Court of Chancery considered one argument dispositive: that the meeting notice was inherently deficient because the meeting agenda omitted the removal action effectuated at the meeting, and indeed misleadingly suggested that one Defendant’s officer role would be expanded. The Court condemned the notice as “duplicity,” voided the vote, and held that the Defendants remained officers of the Company.
The Meeting Notice
The stated purpose of the meeting was to discuss how to bring “better governance and transparency” to the Company, and the agenda included the following items:
- Review of requests for financial statements, bank records, and supporting documentation;
- Discussion of alleged unauthorized transactions or approvals;
- Proposal for new signatory protocols and centralized finance email;
- Proposed recognition and role expansion for one of the Defendants; and
- Any additional matters raised by board members or shareholders in good faith.
Following the notice, there were additional communications amongst the directors detailing the items for discussion at the meeting. Notably, the removal of the Defendants as officers was never mentioned. In fact, although one Plaintiff director raised certain “potential areas of concern,” he specifically said that the meeting notice was not “an accusation of wrongdoing against any individual,” but was instead “a formal invitation to clarify and remedy any potential governance shortfalls,” and he invited the directors to “submit any ‘contrary evidence’ and ‘additional agenda items’ ahead of the meeting.” He also mentioned one Defendant’s “notable contributions,” and proposed that he be appointed Chief Revenue Officer and given enhanced compensation.
Before the board meeting, however, there was a “falling out” between that director and the Defendants. The latter then said that they would be unable to attend the meeting due to their “tight schedules.” The meeting went forward as planned, with only the three Plaintiff directors in attendance. Later resolutions state that, at the meeting, the three Plaintiff directors removed the Defendants as officers of the Company.
The Court found that the meeting notice technically complied with the Company’s bylaws, but nevertheless voided the vote taken at the meeting because the notice was not equitable. Instead, the Court considered it a “bait and switch that concealed the Plaintiffs’ intention to remove [the Defendants] as officers.” In holding that the Defendants remained officers of the Company, the Court stressed that “[e]quity will not abide such duplicity toward fellow directors.” The Court also rejected the argument that notice was not required where the targeted directors lacked the power to block the action, stressing that “[f]air notice fosters a genuine deliberative process – a purpose that was subverted here.”
Lessons Learned
Ghatty offers some important lessons about the value of good governance when taking board action:
- Directors are entitled to a “fair and non-misleading notice of the agenda for a special meeting,” even if the notice technically complies with the bylaws. When drafting agendas, consider whether the agenda adequately describes the discussion points and decision items for the meeting.
- Holding Regular Meetings. This meeting was the Company’s first in-person board meeting in three years. This fact was relevant to the determination of whether the meeting was a “regular” or “special” meeting. That distinction can be significant, particularly in instances where the company’s bylaws have different notice requirements for regular versus special board meetings.
- Clear Bylaws. The Court began its analysis by turning to the Company’s bylaws. In support of their argument that the meeting notice was deficient, the Defendants cited to a stockholder meeting provision in the bylaws that required a specific statement of the meeting’s purpose. Because the bylaws lacked an analog requirement for board meetings, the Court found that the notice was technically sufficient, and had to rely instead on its equitable power to reach its result. Consider whether there are unintentional gaps or inconsistencies in your company’s bylaws that can be clarified or corrected to provide more certainty and consistency across governance items. Also remember that bylaws set the rules for the game, but, as seen in Ghatty, can’t protect against bad faith.
- Records and Meeting Minutes. The Court referenced the fact that there were no contemporaneous minutes or evidence of the meeting, only a resolution dated a couple of weeks later stating that, at the meeting, “appropriate resolutions were adopted, changing certain officer and signatory roles within the Company.” Although the Court did not rely on this fact in its holding, it is a helpful reminder of the importance of appropriately and timely documenting actions taken at a meeting.
Children’s privacy regulations globally are shifting away from notice-and-consent models toward outright access restrictions, age-appropriate design mandates, categorical advertising prohibitions, and app-store-level age verification, as illustrated by Australia’s December 2025 enforcement of its under-16 social media ban. In the United States, similar legislative efforts have faced significant First Amendment challenges that have stalled most state laws restricting minor access to social media and AI platforms, while age-appropriate design requirements inspired by California’s law have been enacted in several states. Several states, including Oregon, have enacted categorical bans on targeted advertising to known minors, while app-store-level age verification laws imposing age-signal obligations on app developers are also subject to active litigation. Companies operating consumer-facing digital services should map where minors interact with their products, review advertising practices involving teens, and prepare for the eventual downstream effects of age-signal regimes.
Since August 2, 2026, organizations have been subject to the transparency obligations set out in Article 50 of the EU AI Act. Article 50 introduces transparency requirements for providers and deployers in relation to certain AI system functionalities and use cases that may create transparency risks for individuals. Whilst much of the EU AI Act focusses on obligations on high-risk AI systems, Article 50 obligations may also apply to certain limited-risk systems. As a result, many organizations need to implement governance, disclosure, and content-labelling measures to ensure users are appropriately informed about the use of certain AI systems and AI-generated content.
Importantly, these obligations were largely unaffected by the implementation delays contained in the Digital Omnibus on AI (Regulation (EU) 2026/1744), except for the marking obligations contained in Article 50(2) of the EU AI Act, i.e. relating to AI systems that generate synthetic audio, image, video, or text content and that were placed on the market before August 2, 2026. Following the agreement reached between the Council and the European Parliament on May 7, 2026 (see the European Parliament procedure record), and formally adopted on June 29, 2026, the introduction of these marking obligations has been delayed until December 2, 2026.
In a Bloomberg Law article, Sidley lawyers Greg Lantier, Liv Herriot, and Raneem Eter examine recent federal court decisions clarifying lawyers’ obligations when using generative artificial intelligence (AI) in litigation. The article analyzes how courts are applying Federal Rule of Civil Procedure 11 to AI-assisted filings, emphasizing lawyers’ duties to verify citations, supervise AI-generated work product, and ensure the accuracy of court filings. The authors also outline practical governance measures law firms and legal teams can adopt to reduce AI-related litigation risks and strengthen accountability.
Courts are writing their own rules about generative AI, and in patent cases those rules differ sharply from judge to judge. This survey, current as of September 8, 2026, catalogs the generative-AI requirements in the venues where most patent infringement suits land: the Eastern and Western Districts of Texas, the Northern and Central Districts of California, the Northern District of Illinois, the District of New Jersey, and the District of Delaware and the U.S. International Trade Commission, where no AI-specific rules were identified. Only the Eastern District of Texas has a court-wide rule, making every litigant responsible for verifying AI-assisted filings. Elsewhere the obligations come from individual judges’ standing orders and vary widely, from restating the existing duty to verify what you sign to requiring a separate certificate naming the AI tool, confirmation that a human checked every citation, records of the prompts used, or disclosure of AI use in billing. Penalties include US$500 per violation and having the filing struck.
On June 2, 2026, President Trump signed an executive order called “Promoting Advanced Artificial Intelligence Innovation and Security” building on the cyber strategy his administration released in March 2026, which sets deadlines for federal agencies in three areas: using artificial intelligence (AI) to defend government and critical infrastructure systems, evaluating the most capable AI models, and prosecuting people who use AI to break into computers or commit fraud. It directs the Cybersecurity and Infrastructure Security Agency (CISA) to issue binding directives within 30 days, and the United States Department of Treasury to create an industry clearinghouse that coordinates vulnerability scanning and patching.
Within 60 days, agencies must build a classified benchmarking process to decide when a model counts as a covered frontier model, plus a voluntary program letting developers give the government early access before a wider release. For companies, the signal is that AI security and cybersecurity are being treated as one governance topic, and AI-enabled defenses may become a baseline expectation in government and critical infrastructure contracts.
On April 29, 2026, the Delaware Supreme Court upheld the dismissal of consolidated stockholder challenges to advance notice bylaws that The AES Corporation and Owens Corning each adopted in 2023. Advance notice bylaws are the internal rules setting out how far in advance, and with what disclosures, a stockholder must tell a company it intends to nominate directors or bring business before a meeting. The stockholders attacked the provisions in the abstract, without anyone having actually attempted a nomination and been turned away.
The court held that this was not enough to proceed. Delaware courts will review these provisions when there is a concrete, live dispute about how a bylaw is being applied, not when the alleged harm depends on future events that have not occurred. The decision continues a consistent line of recent bylaw rulings and means such provisions generally will not be tested in court until a real nomination dispute arises.
On March 25, 2025, Delaware Governor Matt Meyer signed significant amendments to the Delaware General Corporation Law that provide greater predictability and clarity for conflicted transactions. The amendments create statutory safe harbors under Section 144 that preclude equitable relief and damage claims when transactions involving controlling stockholders or control groups are approved through either a properly functioning special committee of at least two disinterested directors or an informed, uncoerced vote of disinterested stockholders (with both mechanisms required only for controller go-private transactions). The amendments also define key terms including “controlling stockholder” (with a one-third voting control floor), “control group,” and “disinterested director,” extend duty-of-care exculpation to controlling stockholders, and narrow stockholder books-and-records inspection rights under Section 220 to core materials while adding heightened requirements for accessing additional records. The amendments apply to acts and transactions regardless of when they occurred, but do not apply to legal proceedings or demands commenced on or before February 17, 2025.
On February 27, 2026, in a unanimous 37-page opinion, the Delaware Supreme Court upheld the constitutionality of significant changes to the Delaware General Corporation Law (DGCL) enacted in March 2025 via Senate Bill 21 (SB 21). This decision permits Delaware corporations and their advisers to confidently rely on these amendments for transactions with interested fiduciaries (including controlling stockholders), thereby increasing transaction planning flexibility and certainty while decreasing litigation risk under Delaware law.
Background of SB 21
As previously discussed in this Sidley Update, SB 21 provided greater statutory clarity in a number of important areas that had been the subject of common law development. It amended Section 144 to, among other things, create new statutory safe harbors for transactions with interested fiduciaries, including controlling stockholders. Although these safe harbors are akin to previously existing common law standards, they reflect important changes thereto that decrease transaction planning risk beyond those prior tests. These include (i) offering safe harbor protection in all interested-fiduciary transactions (except for going private transactions) by the use of either disinterested committee/director approval or a majority-of-the-minority vote (not both), (ii) incorporating a definition of “controlling stockholder,” and (iii) codifying standards for director independence and disinterestedness. SB 21 also amended Section 220 to clarify the scope of books and records inspections. These changes applied retroactively to all acts or transactions whether occurring before, on, or after enactment, subject only to a carveout for litigation commenced or demands made before February 17, 2025 (when SB 21 was announced). The constitutionality of the Section 144 amendments, and their retroactivity, was promptly challenged.
Constitutional Questions and Answers
In Rutledge v. Clearway Energy Group LLC, No. 248, 2025 (Del. Feb. 27, 2026), the Delaware Supreme Court considered two constitutional challenges to Section 144, focused on its safe harbor provisions and retroactive application. It rejected both.
1. First, the Delaware Supreme Court held that Section 144’s safe harbors, which preclude equitable relief and eliminate damages claims against fiduciaries, do not improperly limit the Court of Chancery’s equity jurisdiction.
Highlighting the Delaware General Assembly’s long-respected and regularly employed legislative power to amend the DGCL, including in response to common law developments, the Delaware Supreme Court held that the Court of Chancery was not improperly divested of its equitable jurisdiction via SB 21’s amendments to Section 144. The Supreme Court reasoned that the Court of Chancery remains empowered to adjudicate fiduciary duty claims and to determine whether the prerequisites for the safe harbor protections in Section 144 are achieved. Although two remedies previously available to the Court of Chancery — equitable relief and awards of monetary damages against directors, officers, controllers, or control groups — are now unavailable where the Section 144 safe harbor prerequisites have been met, the Court of Chancery retains jurisdiction over fiduciary duty claims. The Supreme Court viewed SB 21 as “a legitimate exercise of the General Assembly’s authority to enact substantive law that, in its legislative judgment, serves the interests of the citizens of our State.”
2. Second, the Delaware Supreme Court held that the retroactive application of SB 21 to transactions occurring prior to its enactment does not violate due process by eliminating vested fiduciary claims.
The Delaware Supreme Court held that SB 21’s retroactive application does not extinguish vested rights of action in a manner violative of constitutional due process rights. The Delaware Supreme Court questioned the premise that Rutledge had a vested property right prior to SB 21’s enactment because his interest was more in the form of an “anticipated continuance of” existing law. But it concluded that even assuming he had such a right, the Delaware General Assembly clearly intended that the statute apply retroactively and “exercise[d] its legislative authority in conformity with the dictates of due process” by crafting a statute reasonably related to a legitimate objective. As a result, SB 21 does not strip away vested claims in violation of due process and will apply equally to all acts and transactions on or before February 17, 2025, unless already then subject to an action, proceeding, or demand.
Key Takeaways for Boards and Dealmakers
Safe Harbor Certainty
First and foremost, Clearway preserves SB 21’s empowerment of disinterested decisionmakers to protect investors in transactions with interested fiduciaries. Corporations engaging in transactions with fiduciaries may confidently rely on the safe harbor frameworks in Section 144, which will continue to increase predictability and flexibility in corporate dealmaking while reducing litigation risk. Significantly, transaction planners can be confident that any act or transaction involving an interested director, officer, controller, or control group (other than a going private transaction) may be cleansed by either a special committee approval or by a majority-of-the-minority stockholder approval. Although Clearway settles SB 21’s constitutionality, all corporate law statutory frameworks necessarily reflect some degree of unpredictability when first enacted that will be reduced over time through case law development.
Compliance and Documentation
Parties and practitioners should take into account these amendments and design transactions to fit within Section 144’s safe harbor protections to avoid potential application of the “entire fairness” standard of review. Corporations and their counsel should continue to deploy best practices to monitor and carefully document compliance with the contours of the safe harbors. Some key areas for monitoring and documentation include:
- analysis of the disinterestedness of decisionmakers;
- disclosure of all material facts to disinterested directors;
- processes supporting a “good faith” approval of any such transaction by disinterested directors “without gross negligence”; and
- disclosure of material facts in connection with any disinterested stockholder approval of a transaction.
Reincorporation Considerations
Underpinning the Delaware Supreme Court’s constitutional analysis was a deep deference to the Delaware General Assembly’s ability to amend (often swiftly) Delaware’s corporate law statutes. The decision therefore bolsters one of the reasons many corporations have chosen to incorporate in Delaware: a fast-acting and responsive legislative branch. The substance of SB 21 is likewise an important consideration in any reincorporation discussion, because the Section 144 amendments provide a roadmap for transaction planners to follow that reduces unpredictability and overall litigation risk, although we anticipate that litigation challenges will be brought to develop the contours of the statute’s application.
The Delaware Court of Chancery threw out all twelve claims a group of Jenzabar stockholders brought against the company’s founder, his former spouse, and the board. The stockholders complained about two things: that the company had paid the founder’s appeal bond and legal fees in an earlier case where he was found to have taken a corporate opportunity worth US$81 million, and that a decade of generous stock and bonus awards had let the founder and his ex-wife grow their ownership from 18% to 91% while diluting everyone else. The court held that dilution claims like these belong to the company, not to individual stockholders, so they had to be brought as derivative claims on the company’s behalf.
The rest of the case failed on timing. The claims about the appeal bond and legal fees were filed too early, because the indemnification agreement required an independent lawyer to decide whether the founder was entitled to be reimbursed, and that process was still underway. The compensation claims were filed too late, since the events happened between 2012 and 2015 and Delaware applies a three-year clock. The practical lesson for founders and counsel is that indemnification and advancement are different promises with different timing, and that if your equity grants ever draw scrutiny, the clock starts running when stockholders have enough information to ask questions.
Delaware has long been the default jurisdiction of incorporation of high-growth emerging companies due to its advanced, and evolving, body of corporate law, a specialized Court of Chancery, and decades of corporate law cases and precedents. But that default assumption has now come into question.
In recent years, Delaware’s courts have issued a series of decisions that have left some founders of high-growth companies unsettled. See, for instance, the recent Tesla cases, following which Elon Musk publicly blasted Delaware and both Tesla and SpaceX reincorporated in Texas. Musk is not alone in this trend toward “DExit” – TripAdvisor, Dropbox, AMC Networks, and Roblox are among those reincorporating in Nevada, and Dillard’s joined Tesla and SpaceX by reincorporating in Texas. Even Meta publicly announced that it was exploring a move out of Delaware in 2025.
In response, Delaware’s legislature adopted major reforms in 2024 and early 2025 (SB 313 and SB 21) codifying safe harbors for conflicted transactions, narrowing books-and-records access, and strengthening management’s shield against litigation.
More and more founders and GCs of later-stage companies are now wondering if Delaware should still be the default.
So, should you care and, if so, where are companies moving?
“Y’all Street” as an Alternative?
In recent years, Texas lawmakers have aggressively reformed state law to attract corporations. The state’s pitch? A pro-business legal climate, big-market economy, and fewer stockholder hassles. In 2024, Texas launched a new statewide Business Court system modeled on Delaware’s Chancery Court, with specialized judges to handle complex corporate cases. This was quickly followed in May 2025 with sweeping legislated changes (SB 29) to the Texas Business Organizations Code, in a package branded as “Texas: Open for Business." Key provisions include:
Codification of the Business Judgment Rule:
Texas now explicitly codifies the business judgment rule and the high bar to rebut it, giving directors stronger protection when their decisions are challenged.
Limits on Derivative Lawsuits:
Allowing corporations to set a minimum ownership threshold (up to 3%) for stockholder-plaintiffs to bring a derivative suit. This threshold is higher than most states and drastically curbs the ability of small stockholders to sue on behalf of the corporation.
Records and Litigation Procedure:
Limiting what constitutes corporate “books and records” available for stockholder inspection. For instance, emails and electronic communications are excluded. It also allows companies to include provisions in their charters or bylaws waiving the right to jury trials in corporate disputes, meaning cases would be heard solely by judges (as they are in Delaware’s Chancery Court).
In addition to the changes effected by SB 29, Texas later enacted several additional measures to allow certain Texas-listed public companies to adopt higher thresholds for stockholder proposals and to authorize the board of directors to delegate more discretion to the corporation’s executives.
Pros and Cons of the Y’all Street
The Texas proposals seem very attractive, especially to issuers and their insiders, but, in practice, their effectiveness is hard to measure. The new courts lack Delaware’s decades of precedent, making Texas less predictable for companies. So, certainty with respect to a few specific matters is offset by uncertainty with respect to treatment of a myriad of others. Additionally, incorporating in Texas might expose a corporation to Texas venue for certain lawsuits.
Texas has certainly had some luck in attracting private and public companies as of late, and we are working with a number of companies exploring Texas as a potential alternative to Delaware.
The “Silver Sanctuary”?
Like Texas, Nevada’s appeal lies in providing certainty to companies and their insiders with respect to certain specific common transactions. It automatically offers directors and officers strong protections. Key features of Nevada’s corporate environment include:
Robust Liability Shields
Nevada law automatically exculpates directors and officers from personal liability for breaches of fiduciary duty (except in cases of intentional misconduct, fraud, or knowing law violations). In Delaware, by contrast, corporations must opt in to exculpation (and even then, it covers only duty of care, not loyalty, and only recently were officers allowed similar protection). Nevada’s default rule thus gives executives peace of mind that honest mistakes won’t easily lead to personal liability. Likewise, Nevada statutes make it easier to indemnify and protect managers, which can reduce D&O insurance costs.
Consideration of Other Interests
Nevada explicitly permits boards to consider long-term corporate interests and the impacts on employees, customers, the community, etc., when making decisions. Directors are not strictly bound to maximize immediate stockholder value at all costs. This allows directors to justify decisions that favor sustainable growth or other constituencies, without breaching their duty to stockholders. This contrasts with states like Texas or Delaware, where directors must generally act in the best interests of the corporation and its stockholders, with true stakeholder balancing available only if the corporation opts into a Public Benefit Corporation framework.
No Franchise Tax
From a financial perspective, Nevada imposes no corporate franchise tax and so may prove cheaper to operate in, especially for early-stage companies.
Pros and Cons of the Silver Sanctuary
Nevada offers what Nevada usually offers: more freedom to operate at the expense of less predictability. Nevada’s business courts were established in 2001, but those courts have not published nearly as many written opinions, or as routinely, as Delaware’s Court of Chancery. The law, while more insider-friendly, is also less modernized in other areas.
So, in the end, what should you do?
The answer is not clear-cut. For now, there is no mass flight out of Delaware, but certainly lots of discussions are taking place. No clear winner has emerged for the alternatives, but it does appear that more public companies are leaning towards Texas while more private companies are considering Nevada. But the vast majority of new incorporations are still taking place in Delaware.
It all comes down to perception, expectation, and, perhaps in the future, actual experience. To help your thinking, a chart summarizing some, but certainly not all, of the key features of the three regimes may be found here:
In more challenged private company financing environments, down rounds (i.e., an equity financing at a lower valuation than a prior equity financing) often go from a relatively uncommon occurrence to a more common aspect of many growth equity and venture capital financings. The interrelated impact of geopolitical and macroeconomic events such as valuation resets from post-pandemic highs, public and private market liquidity constraints, prolonged fundraising cycles, and shifts in bargaining power can have profound effects on growth equity and venture capital financing dynamics, making down rounds and valuation pressure more common. Down rounds have significant implications for all participants in the venture ecosystem: founders and management teams, investors, employees, and fund limited partners.
This article focuses on the basic mechanics of conversion price-based anti-dilution protections for convertible preferred stock. Anti-dilution protections need to be considered in the context of the impact on the pricing of the down round in question, and also on the potential impact of future adjustments.
Anti-Dilution Protections
In any equity financing, two types of dilution can occur when a company issues new shares: (1) percentage dilution occurs because the issuance increases the number of outstanding and fully-diluted shares, reducing an existing holder’s ownership percentage if that holder does not maintain their ownership percentage through additional investment, and (2) economic (or price) dilution occurs when a company issues shares at a price that is lower than the conversion price applicable to an investor’s shares, reducing the value of that investor’s position on an as-converted basis.
The conversion price-based anti-dilution protections discussed below are intended to mitigate economic (or price) dilution and the resulting percentage dilution on an as-converted basis. Investors may also help protect against percentage dilution through preemptive rights, which can permit pro rata participation in later financings, whether those are up rounds or down rounds.
Below is a simple illustration of how dilution can occur:
- Before a down round, if Investor A purchased 2,500,000 shares of convertible preferred stock at a price of US$5 per share, and after that financing there were 10,000,000 shares of the company outstanding, Investor A’s US$12,500,000 investment would represent a 25% ownership stake in the company.
- In the down round, the company sells 5,000,000 new shares to investors (other than Investor A) at a price of US$4 per share.
- Following the down round, Investor A continues to own 2,500,000 shares of convertible preferred stock, now out of 15,000,000 outstanding shares of the company, representing a decreased ownership stake in the company of 16.67%, valued at approximately US$10,000,000.
To help protect against the scenario above, Investor A would typically have negotiated for price-based anti-dilution protection when it originally purchased its convertible preferred shares. In a down round, these protections operate to adjust Investor A’s conversion price and therefore the rate at which those shares ultimately convert into common stock. There are two main types of conversion price-based anti-dilution protection: (i) full ratchet and (ii) weighted average.
Full Ratchet
While less common in practice, there has been an increased use of full-ratchet anti-dilution protections to bridge valuation gaps (sometimes, with a sunset date). When used, they can have a profound impact on down-round financing. With full ratchet anti-dilution protection, the conversion price applicable to Investor A’s convertible preferred shares is reset to the new lower price per share from the down round (which is US$4 in the example above), meaning each preferred share from then on would convert into 1.25 shares of common stock.
Now, as a result, if those preferred shares convert, Investor A would own 3,125,000 shares of common stock out of 15,625,000 outstanding shares, meaning Investor A would therefore have a 20% ownership stake (which is less than Investor A’s initial 25% stake, but greater than the 16.67% stake Investor A would have been left with without this full ratchet protection).
Full ratchet protection is not common, but when it does exist, the resulting impact in a down-round financing can be profound.
Weighted Average
Weighted-average anti-dilution protection is far more customary. With weighted-average anti-dilution protection, a formula is used to determine a new conversion price that will apply to existing preferred shares following a down round:
- New Conversion Price = Old Conversion Price * [(X + Y) / (X + Z)]
- X = the number of shares outstanding on a fully-diluted basis before the down round.
- Note that the nuances of the X variable are sometimes negotiated, with a company preferring a broader approach (often referred to as the “broad-based” weighted-average formula) that includes all shares on a fully diluted basis, and an investor preferring a narrower approach (often referred to as the “narrow-based” weighted-average formula) that excludes certain types of derivative shares such as options and warrants. The broad-based weighted-average formula is more commonly used.
- Y = the number of shares that would have been issued to new investors in the down round had the full investment been made at the old price per share (which is US$5 in our example above).
- Z = the number of shares issued to new investors in the down round at the new price per share (US$4 in our example).
- X = the number of shares outstanding on a fully-diluted basis before the down round.
In our example, the resulting math would be:
New Conversion Price = US$5.00 * [(10,000,000 + 4,000,000) / (10,000,000 + 5,000,000)]
- US$5.00 * [(14,000,000) / (15,000,000)]
- US$5.00 * [0.933]
- US$4.67
Under this approach, the adjusted conversion price applicable to Investor A’s convertible preferred shares is now US$4.67, meaning each of Investor A’s preferred shares is convertible into 1.07 shares of common stock.
Now, if those preferred shares convert, Investor A would own 2,675,000 common shares out of 15,175,000 outstanding shares, meaning Investor A would therefore have a 17.63% ownership stake (which is less than Investor A’s initial 25% stake, and less than the 20% stake Investor A would have had with full-ratchet protection, but more than the 16.67% stake that would have resulted without any protection).
Economic Dilution
As mentioned above, conversion price-based anti-dilution protections are designed to reduce the impact of percentage dilution, but they also mitigate economic dilution. Continuing with our example:
- Before the down round, the value of Investor A’s as-converted stake in the company was US$12,500,000.
- Value = (Price Per Share * Number of As-Converted Shares)
- (US$5.00 * 2,500,000)
- US$12,500,000
- Value = (Price Per Share * Number of As-Converted Shares)
- Without any anti-dilution protection, the value of Investor A’s as-converted stake in the company would drop to US$10,000,000.
- Value = (Price Per Share * Number of As-Converted Shares)
- (US$4.00 * 2,500,000)
- US$10,000,000
- Value = (Price Per Share * Number of As-Converted Shares)
- With full-ratchet anti-dilution protection, the value of Investor A’s as-converted stake in the company would remain US$12,500,000.
- Value = (Price Per Share * Number of As-Converted Shares)
- (US$4.00 * 3,125,000)
- US$12,500,000
- Value = (Price Per Share * Number of As-Converted Shares)
- With weighted-average anti-dilution protection, the value of Investor A’s as-converted stake in the company would drop to US$10,700,000 instead of US$10,000,000.
- Value = (Price Per Share * Number of As-Converted Shares)
- (US$4.00 * 2,675,000)
- US$10,700,000
- Value = (Price Per Share * Number of As-Converted Shares)
Down Round Pricing Must Be Modeled Holistically
These anti-dilution mechanics may be familiar to and understood by most management teams, investors, and advisors, but the practical implications are often not as straightforward. In practice, the negotiated enterprise value, or pre-money valuation, of a company is typically set at the outset of a negotiation, but the resulting per-share price often is not. The per-share price must generally be solved for after giving effect to anti-dilution adjustments, any option pool increase, and the resulting post-closing capitalization. When solving for this price per share, if anti-dilution adjustments would be triggered, the result is that the end-result number of as-converted shares outstanding will be higher than otherwise, which can prompt an iterative calculation. The end-result number of as-converted shares outstanding, and therefore the preferred price per share, must be solved for again.
Existing investors’ anti-dilution protections typically create a direct economic tension with the investors proposing to lead the down-round financing. This is because new investors typically bargain for a specified ownership percentage and expect their investment to buy it. Existing investors may seek to maximize the value of their anti-dilution adjustments. Common stockholders and other unprotected holders, including management and employee option holders, end up bearing much of the resulting dilution and often are most heavily “crammed down.” On the other hand, existing and new investors typically want to ensure that the management team is protected and appropriately motivated, so the option pool increases, the number of end-result fully diluted shares outstanding again changes, and the entire iterative calculation dance begins again. Add in the fact that many down rounds are led by some subset of existing investors, and the tension around the per-share price calculations increases further.
Because of these dynamics, down-round pricing should not be modeled by simply picking a per-share price. Instead, the agreed pre-money valuation, anti-dilution adjustments, option pool increase, and post-closing ownership targets should be modeled together and holistically to ensure that the intended transaction is delivered.
Discussions over a down-round transaction often expand well beyond pricing mechanics and can raise questions about participation, including the potential emergence of a pay-to-play dynamic, board fiduciary duties, voting power, minority equityholder protections, contingency planning for future financing, potential waivers of anti-dilution protections, control-investor risks, the consent process, and the consensus-building required to secure key approvals.
In Fortis Advisors v. Krafton, the Delaware Court of Chancery awarded a striking equitable remedy: it ordered the reinstatement of a CEO who was wrongfully terminated using a strategy developed with ChatGPT, and extended the earnout period by the full duration of his improper exclusion. The buyer had used AI to strategize avoidance of a US$250 million earnout, but because that advice was generated outside the attorney-client relationship, it was not privileged and became damning evidence at trial. The decision puts buyers on notice that depriving seller-managers of bargained-for post-closing operational control may result in not just damages, but equitable remedies that restore control and reset the earnout clock.
One of the most common legal missteps among emerging companies involves the classification of the people doing the work. In the earliest days of a startup, founders often bring on talented individuals as “consultants” or “independent contractors,” compensating them primarily or exclusively with equity. This arrangement feels natural when cash is scarce and everyone is pitching in to build something from the ground up. But what begins as a practical solution can quickly become a significant legal liability if the company does not revisit these classifications as it matures and secures funding.
This article provides a high-level overview of the risks associated with worker misclassification, the key legal frameworks that govern these determinations, and the steps founders should take to clean up classification issues before they become costly problems.
The Common Pattern: Early “Consultants” Who Are Really Employees
It is extremely common for pre-revenue startups to engage early team members as independent contractors or consultants. The logic is straightforward: The company cannot yet afford salaries, payroll taxes, or benefits, so it issues equity in exchange for labor. On paper, the individual signs a consulting agreement, invoices the company (or doesn’t), and is treated as a 1099 worker for tax purposes.
The problem is that many of these individuals are, as a matter of law, employees regardless of what the agreement says. Classification is not a matter of mutual agreement between the parties. It is determined by the nature of the working relationship under applicable federal and state law. If the engagement looks and feels like employment, then government agencies and courts are likely to treat it as such.
When these individuals are never reclassified, the company accumulates exposure over time. That exposure includes unpaid wages, overtime, employment taxes, penalties, and potential liability under both federal and state law. These issues often surface at the worst possible moment: during due diligence for a funding round, an acquisition, or in response to a complaint filed by a disgruntled former worker.
Why Reclassification Should Be a Priority After Funding
Securing any meaningful financing event should serve as a trigger for the company to revisit every worker classification. There are several reasons for this.
First, the original justification for the consulting arrangement, namely the inability to pay cash compensation, has likely changed. Once the company has capital, it has the resources to bring workers onto payroll and provide the protections required by law. Continuing to classify a worker as an independent contractor when the company now has the means to pay wages and withhold taxes weakens any argument that the arrangement was legitimate.
Second, investors and their counsel will scrutinize the company’s employment practices during due diligence. Misclassification issues are a well-known red flag. Unresolved classification problems can delay or even derail a financing, reduce the company’s valuation, or result in specific indemnification obligations imposed on the founders.
Third, as the company grows, the risks multiply. More workers mean more potential claimants. Longer periods of misclassification mean larger back-pay and tax liabilities. And the shift from a small, informal team to a structured organization makes it increasingly difficult to argue that any given worker was genuinely operating as an independent business.
The bottom line is that reclassification is not merely a housekeeping exercise. It is a critical step in putting the company on sound legal footing for its next phase of growth.
Federal Law: The Key Frameworks
At the federal level, worker classification is governed by several overlapping tests, depending on the statute at issue.
The Fair Labor Standards Act
The FLSA uses an “economic reality” test to determine whether a worker is an employee or an independent contractor. The inquiry focuses on whether the worker is economically dependent on the company or is in business for themselves. Factors include the degree of control the company exercises over the work, the worker’s opportunity for profit or loss, the worker’s investment in equipment or materials, the permanence of the relationship, the degree of skill required, and the extent to which the work is an integral part of the company’s business. The Department of Labor has historically taken a broad view of employment under this test, and the consequences of misclassification include liability for unpaid minimum wages and overtime, liquidated damages, and attorneys’ fees.
The Internal Revenue Code
The IRS applies a common-law test that examines the degree of control and independence in the relationship. The IRS groups relevant factors into three categories: behavioral control (whether the company directs how the work is done), financial control (whether the company controls the business aspects of the worker’s role, such as how the worker is paid and whether expenses are reimbursed), and the type of relationship (including written contracts, benefits, and the permanence of the engagement). Misclassification under the tax code can result in liability for unpaid employment taxes, penalties, and interest. In some cases, officers of the company may face personal liability under the trust fund recovery penalty.
Exempt vs. Non-Exempt Classification
Once a worker is properly classified as an employee, the company must also determine whether the employee is exempt or non-exempt under the FLSA. Exempt employees are not entitled to overtime pay, but they must meet specific salary and duties tests. The most commonly applicable exemptions for startups are the executive, administrative, professional, and computer employee exemptions. Each requires that the employee be paid on a salary basis at or above a specified threshold and that the employee’s primary duties satisfy specific criteria. Founders should not assume that simply paying a salary or giving someone a managerial title is sufficient. The analysis turns on the actual duties performed, not the job title.
State Law: Where the Rules Get Stricter
Many states impose classification standards that are more restrictive than federal law, and compliance with federal standards alone does not guarantee compliance at the state level.
California’s ABC Test
California applies a particularly stringent standard under its ABC test, codified by Assembly Bill 5. Under this test, a worker is presumed to be an employee unless the hiring entity demonstrates that the worker (A) is free from the company’s control and direction in performing the work, (B) performs work that is outside the usual course of the company’s business, and (C) is customarily engaged in an independently established trade, occupation, or business of the same nature as the work performed. Prong B is often the most difficult to satisfy for startups, because early workers are typically performing tasks that are central to the company’s core business. California law also provides for significant penalties for misclassification, including penalties under the Private Attorneys General Act, which allows employees to bring representative actions on behalf of the state.
Other Notable State Frameworks
Several other states have adopted or are moving toward ABC-style tests, including Massachusetts, New Jersey, and Illinois. New York applies a similar multi-factor test and has aggressive enforcement mechanisms. States vary considerably in their approaches, and companies with remote workers in multiple states must ensure compliance in each jurisdiction where a worker is located, not merely where the company is headquartered. Founders should be particularly attentive to any state in which the company has workers, as the applicable test is generally determined by the worker’s location.
Cleaning Up Past Misclassification
For companies that have already been operating with misclassified workers, there are several steps to consider when undertaking a remediation effort.
The first step is to conduct an honest internal audit. Identify every individual who has been engaged as a contractor or consultant and evaluate each engagement under the applicable federal and state tests. Determine which individuals are likely misclassified and assess the duration and scope of the exposure.
The second step is to consult with experienced employment counsel. Remediation strategies vary depending on the jurisdiction, the number of affected workers, the duration of misclassification, and the company’s financial position. In some cases, the IRS Voluntary Classification Settlement Program may be available, which allows companies to prospectively reclassify workers with limited look-back liability in exchange for a modest payment. Similar programs or settlement frameworks may exist at the state level.
The third step is to transition misclassified workers to employee status going forward. This includes placing them on payroll, withholding applicable taxes, providing required benefits, and ensuring compliance with wage and hour laws, including proper exempt or non-exempt classification.
The fourth step is to address the equity arrangements already in place. Early equity grants made to individuals who should have been classified as employees may have been structured as contractor grants, which have different tax treatment than employee equity awards. Companies should work with both employment counsel and tax advisors to evaluate whether corrective filings or revised equity documentation are necessary, particularly with respect to Section 409A of the Internal Revenue Code, which governs deferred compensation and imposes significant penalties for noncompliance.
Finally, companies should implement classification policies and procedures that will prevent these issues from recurring as the company continues to hire. A brief intake process for every new engagement, whether employee or contractor, can go a long way toward ensuring that the correct classification is applied from the outset.
The Department of Justice announced a US$21.5 million settlement with five Deloitte entities to resolve allegations under the False Claims Act, the federal statute that penalizes companies for submitting false claims for government money. Notably, the DOJ alleged that the companies’ employment practices violated Title VII and the standard equal opportunity clause found in federal contracts, and that billing the government while out of compliance amounted to a false claim. The case is the second settlement secured under DOJ’s Civil Rights Fraud Initiative, a cross-agency enforcement push that pairs the False Claims Act with other tools such as the Equal Credit Opportunity Act. For startups, the relevant exposure is real: companies that sell to federal agencies and their subcontractors are bound by the equal opportunity clause, Title VII, and the compliance obligations that come with them.
For companies considering an IPO, relationships with investment bankers should often begin well before the company formally mandates its IPO syndicate. Early banker relationships can provide valuable market perspective while there is still time to act on it — helping companies understand how public investors may view the business, pressure-test the equity story, and identify issues that may matter when an IPO becomes more immediate. As the IPO becomes more concrete, the relationship should evolve from market intelligence and relationship-building toward positioning, syndicate selection, and execution. The takeaway: engage with bankers early; formally mandate them later when the company is ready to pursue an IPO.
The Stages of Banker Engagement
Companies often think about engaging bankers as a discrete step in the IPO process — running a “bake-off,” selecting the syndicate and moving toward an organizational meeting. But the most productive banker relationships often begin much earlier. The purpose of those relationships, however, should change as the company moves closer to a potential IPO.
Relationship-Building (as early as 24–36 months out)
For many high-growth companies, banker relationships begin years before a potential IPO. At this stage, there is no mandate to award and no syndicate to construct. The objective is to develop relationships with a thoughtful group of bankers and to leverage their perspective to understand how the public markets are likely to view the company.
Bankers can be a valuable source of market intelligence during the pre-mandate period. They can provide periodic market and valuation perspectives, invite management to industry conferences, make introductions to potential investors, and help management understand how the public markets are likely to frame the business. These interactions also give bankers an opportunity to develop their understanding of the company well before they are competing for a formal role. Just as importantly, the company can use this period to assess various banks over a long horizon, rather than solely in the compressed setting of a formal pitch process.
This early dialogue can be particularly useful because the feedback comes while there is still time to act on it. Bankers may identify a disconnect between the companies that management views as peers and the comparables public investors are likely to use, a KPI that investors will expect but the company does not yet track rigorously, or an aspect of the business model that may require additional explanation or proof. Receiving this feedback early is important because some issues require time, not simply better messaging. For example, it requires time to build the systems that produce key metrics reliably, quarter after quarter, such that at the IPO the company can present multiple years of history against the very measures investors will use to value it. More broadly, early feedback can help management identify a weakness in the equity story — or in the business itself — while management still has time to address it. The goal is not to let bankers author the company’s strategy or equity story, but to use their perspectives to distinguish a messaging issue from a business issue early enough to address either. Companies should also develop relationships across several banks: each bank’s perspective naturally reflects its own franchise, coverage, and views of the market and triangulating among them can provide better intelligence than relying on any single relationship.
Testing the Story (roughly 12–24 months out)
As an IPO becomes a more realistic near- or medium-term objective, banker interactions should become purposeful and market-facing. Bankers can help companies deepen relationships with research analysts and begin appropriate investor education, including through bank-sponsored conferences, non-deal meetings, and, where relevant, late-stage or crossover financings. This engagement is best intensified once a company has genuine visibility into a potential IPO horizon, rather than merely the aspiration to go public. The objective is not simply earlier or greater exposure, but appropriately timed engagement once the company is ready to benefit from — and make a strong first impression in — those interactions.
One of the most consequential relationships is with research analysts. The investment banking team’s role is concentrated in the offering itself; the research analysts who cover the company will remain part of its public-market life for years afterward — publishing estimates, framing quarterly results, and interpreting the company’s strategy and performance for institutional investors. Their sector standing and understanding of the company can meaningfully influence how the company is understood in the public markets following the IPO. Prior to mandating the banks, conversations with research analysts can be genuinely two-way, including by analysts sharing perspectives on the sector. Once banks are formally mandated and an offering process is underway, analyst-independence rules effectively make these interactions one-directional. Nevertheless, even in the pre-mandate period, these conversations should be structured with care and should not extend to valuation or to any bank’s pursuit of an underwriting role, both to preserve analyst independence and to avoid complicating the process later.
In addition, bankers can help build investor familiarity before a formal IPO process begins. Once the process is underway, investor communications become significantly more regulated — and as a practical matter, the quiet-period and “gun-jumping” constraints of the federal securities laws generally begin to attach around the time underwriters are formally mandated, well before any public filing — and investor education is compressed into a limited series of interactions, including testing-the-waters meetings and the roadshow. Investors who already understand the company, its business model, and the key drivers of its financial performance are better positioned to use those interactions to evaluate the equity story and valuation, rather than learning the business for the first time. Bank-sponsored conferences, organized investor meetings, and other appropriate investor-education opportunities allow management to build that familiarity while also giving management an earlier view into the questions public investors actually ask before formal testing-the-waters meetings and the roadshow.
Earlier engagement, however, should not be confused with casual engagement. A premature meeting can be counterproductive: first impressions can be difficult to reverse, and investors and analysts do not simply forget information or expectations communicated in earlier interactions. Companies should think about consistency across private financing materials, investor communications, testing-the-waters materials, and ultimately the registration statement, rather than treating each interaction as a standalone conversation. Information shared in private financings or other pre-IPO interactions can also create legal and practical issues later in the process — for example, projections or other material nonpublic information provided to an investor can complicate that investor's participation in a subsequent IPO if the information remains material nonpublic information. These interactions also consume management attention that may be better spent building the business if an IPO remains too remote. Early outreach should therefore be deliberate, appropriately structured, and coordinated with securities counsel.
The Mandate and IPO Execution (roughly 8–12 months out)
The formal mandate marks the transition from pre-IPO engagement to execution of the IPO itself. As an IPO becomes an execution priority, companies typically conduct a competitive “bake-off” and formally mandate their lead bookrunners. The organizational meeting then kicks off the IPO-specific workstreams, including preparation of the registration statement, valuation and positioning, testing-the-waters and investor education, analyst preparation, roadshow planning, and, ultimately, pricing, allocation, and distribution.
From that point, the banks become part of the core working group and are actively involved in the IPO-specific workstreams. They are closely involved in drafting the registration statement — particularly the business and marketing sections that carry the equity story — and in translating that story into the framework investors will use to evaluate the offering. They lead investor education: identifying the institutions best positioned to anchor the order book, arranging testing-the-waters meetings, and synthesizing investor feedback into refinements of positioning and, ultimately, valuation. And they drive the offering's rhythm — advising on when to convert the confidential submission to a public filing, when to launch the roadshow against the market backdrop and the competing IPO calendar, and how to sequence analyst preparation alongside the offering itself. As a result, banks are typically one of the first groups of advisors formally engaged for an IPO process.
Bank selection should reflect more than proposed valuation or league-table position. Companies should consider the strength and availability of the specific team that will staff the transaction, relevant sector experience, distribution capabilities, and — importantly — the research analysts. Syndicate size and composition should also be deliberate. A broader syndicate can expand distribution and prospective research coverage, but additional banks add coordination and dilute economics and attention across the group. Companies typically select the lead bookrunners at the mandate and add other bookrunners and co-managers later, allowing the core working group to remain relatively small during the early stages of execution.
For private companies backed by venture capital investors, acquisition is frequently the most likely path to liquidity. Founders are often laser-focused on product development, market expansion, and fundraising, without devoting the same early-stage discipline to ensuring the company is well-positioned for a future exit via a merger or acquisition.
M&A preparedness is not a late-stage exercise, but an operational strategy to position your company as an attractive, high-value target to potential acquirors.
Corporate Governance
Some of the most common obstacles to efficient M&A processes stem from issues related to corporate governance. Complex capitalization tables, unclear chain of equity ownership, and unresolved governance issues can create transaction delay and, depending on the structure of the transaction, loss of leverage.
Companies should consider focusing on three key areas of corporate governance to be prepared for future M&A processes: capitalization table discipline, stockholder rights, and board and stockholder alignment.
Capitalization Table Discipline
Maintain clear documentation of all equity issuances with proper board and stockholder approvals; confirm board minutes are complete, approved by the board, and signed; verify that 83(b) elections have been timely filed with respect to restricted stock grants to founders and early employees; and ensure 409A valuations are updated following major events that may impact valuation (such as a financing) and, absent such events, at least annually.
Stockholder Rights
Ensure all stockholders have signed the relevant stockholder agreements and that the company’s management team understands the protective provisions embedded within such agreements; similarly, ensure that the company’s management team is familiar with relevant provisions of any investor side-letters (think drag-along mechanics, rights of first refusal, and co-sale rights).
Board and Stockholder Alignment
Understand what approvals are required to approve a sale or merger of the company and whether any investor has blocking rights.
Contracting Discipline
Material contracts, such as key vendor and customer agreements, collaboration agreements, and licensing arrangements, are some of the first diligence requests in an M&A process. These contracts often contain assignment or change-of-control provisions that can require third-party consent, accelerate payment obligations, or trigger termination rights or other contractual rights that could significantly impact the trajectory of a deal. Accordingly, it is important for companies to maintain clear records of all material contracts, ensuring that all contracts are fully executed and include all attachments, exhibits, amendments, and restatements. Companies should track whether any material contracts have upcoming renewals or expiration dates. Additionally, tracking key provisions in such material contracts that may be triggered by an M&A (such as third-party consent requirements) will help streamline the M&A diligence and consent process.
Intellectual property is another value-driver for life sciences companies and technology companies, making it vital for companies to have documentation that clearly delineates intellectual property ownership. Companies should verify that all employees and contractors have signed Proprietary Information and Inventions Assignment Agreements (PIIAAs), review consulting agreements to confirm that intellectual property created by consultants/contractors has been validly assigned to the company, and obtain confirmatory assignments from founders and early contributors, if needed, and at the appropriate time. For companies with affiliated entities, confirm that the company’s core intellectual property assets sit within the target entity and not within any affiliated entities.
Being proactive can save time and expense during the M&A diligence process.
Regulatory Compliance
Depending on industry and geography, regulatory risk can become a gating diligence issue. Companies should identify areas of risk and preemptively resolve any outstanding compliance risks (e.g., data integrity, marketing, industry-specific licensing, etc.). In particular, life sciences companies should consider pursuing regulatory planning with the assistance of healthcare and/or FDA counsel (as needed) to ensure, among other things, that regulatory filings, communications, and approvals are complete and accessible.
Deal Team Preparation
Once the company has decided to start a sale process, identify at the outset who will be part of the core deal team, which will typically consist of a select number of employees and outside advisors. Members of executive management and other key internal personnel with specialized knowledge about the company’s corporate governance, labor and employment practices, employee benefits structure, assets (IP, real estate, etc.), litigation exposure, and regulatory compliance are typically included within the core deal team. Further, at the appropriate time, companies should engage outside advisors, such as outside legal counsel, financial/tax advisors, and investment bankers, all of whom can help quarterback the transaction and efficiently drive the deal process.
After the deal team is in place, consider implementing deal confidentiality procedures to maintain the integrity of the sale process:
- assign code names to the project and company participants;
- limit working group size and access; and
- consider antitrust issues and the use of “clean team” agreements and data rooms.
Data Room Readiness
Prepared companies treat diligence readiness as an ongoing process and not an exercise triggered by a letter of intent or term sheet. First, select a virtual data room that provides strong security and activity tracking. Second, build the company’s data room with organizational discipline, using logical folder structures (corporate, IP, finance, regulatory, benefits, etc.) and uploading documents in a searchable, digital format with consistent document naming conventions. Lastly, in connection with building the data room, flag with the guidance of deal counsel any confidentiality concerns and access restrictions that need to be put in place. For example, are there any documents that need to be redacted or anonymized? Does the transaction present antitrust sensitivity requiring documents to be shared through a “clean room”?
In all, a well-maintained and categorically organized data room significantly accelerates a sale process and signals sophistication to potential acquirors.
The most successful exits rarely begin when a banker is engaged. Ideally, they begin years earlier with strategic and operational foresight. Companies that understand the value of M&A preparedness can preserve negotiation leverage and act more decisively when M&A opportunities arise. After all, engineering an exit is more than closing a deal — it is positioning the company so that the right deal finds you.
On July 7, 2026, the European Data Protection Board (the “EDPB”) released draft Guidelines 02/2026 on Anonymisation. Once final, these guidelines will replace the former Article 29 Working Party’s Opinion 05/2014 on Anonymisation Techniques and reset how companies decide whether data has been anonymised sufficiently to fall outside the EU’s General Data Protection Regulation. The draft adopts a “relative” view of identifiability, following the EU Court of Justice’s decision in EDPS v. SRB: whether data counts as personal depends on who holds it and what that holder could realistically do to re-identify someone. The same dataset can therefore be personal data in one company’s hands and anonymous in another’s.
For a startup, this matters most where anonymised data is doing real work, such as training or fine-tuning AI models, sharing research datasets with partners, or building analytics products. Labelling data “anonymised” is not a one-time conclusion; it depends on context, recipient, and available re-identification tools. The guidelines are in draft form and open for public consultation until October 30, 2026, after which the EDPB will consider feedback and adopt a final version.
The U.S. Food and Drug Administration is deepening its own use of artificial intelligence. Less than a year after launching its internal AI tool, Elsa, the agency released Elsa 4.0 and connected it to a new unified data platform that pulls together roughly 40 previously separate systems, so staff can query agency data directly instead of uploading documents each time. New features include custom AI agents, document generation, data analysis and visualization, and better search. FDA says humans stay involved at every step and that the model is not trained on data submitted by regulated companies.
On the same day, the then-Commissioner announced a pilot of “one-day inspections” for facilities that AI-driven risk analysis flags as lower risk. These are short screening visits meant to supplement, not replace, full inspections. More than 40 have been completed since April 2026, mostly ending with no action indicated, though inspectors can still issue formal observations and can expand the visit on the spot. Companies are not told in advance whether they are in the pilot, so life sciences startups with manufacturing or clinical sites should stay ready for either format. Complex or higher-risk operations, such as sterile manufacturing, remain on the standard inspection track.
Two February 2026 federal court decisions addressed how existing privilege and work product doctrines apply to generative AI, with one court (in United States v. Heppner) denying privilege and work product protection where an executive used an AI platform without adequate confidentiality safeguards and without counsel’s direction, and another (in Warner v. Gilbarco) holding that a pro se litigant’s AI-assisted analysis via a public AI platform was protected work product. These decisions signal that courts may apply existing doctrines to new technology in the legal context. Key considerations include whether the AI platform’s terms and privacy policies preserve confidentiality, the extent of attorney involvement in the AI-assisted work, and whether the materials were prepared in anticipation of litigation. Organizations should inventory AI tools and review their confidentiality terms, establish guardrails against AI use for legal analysis, and consider updating litigation hold protocols to account for AI-generated materials such as prompts and outputs.
Courts are now addressing how protective orders should govern the use of generative AI in discovery. Two federal decisions — Morgan v. V2X, Inc. and Jeffries v. Harcros Chemicals, Inc. — distinguish between “open” public AI tools that may retain and train on user data and more secure “closed” systems, and contemplate contractual safeguards before confidential discovery materials can be submitted to AI platforms. Practical takeaways may include addressing AI use explicitly at the outset of discovery and drafting concrete operational safeguards rather than referencing specific tools. Emerging issues that parties may anticipate include pro se litigants’ access to AI, AI’s influence on user behavior, and the conceptualization of AI within existing privilege and confidentiality frameworks.
The U.S. Copyright Office’s Part III report on AI and copyright signals that companies cannot assume generative AI training is automatically allowed under “fair use.” The report says copyright issues may arise at several stages: when developers collect and copy protected material for training the model, when a model memorizes protected material in its internal “weights,” and when AI outputs closely resemble copyrighted material. It emphasizes that fair use must be judged case by case, looking at why the original work was used, whether the use is commercial or transformative, how much of the original work was copied, whether guardrails prevent copying in outputs, and whether the AI system harms existing or potential markets for the original work. The report also points to licensing and possible policy reforms as ways to address uncertainty, but overall it takes a cautious approach that is more favorable to copyright owners than to unrestricted generative AI training.
Whether a company is gearing up for an acquisition, a growth equity financing, or an IPO, a due diligence review will be an inevitable part of that transaction, and that review will test not only the current business but also the integrity of a company’s historical records. Readiness for that review is critical, as once a diligence process begins, gaps in corporate approvals, equity records, contract management, intellectual property ownership, and regulatory compliance can quickly become leverage for purchase price adjustments, closing conditions, and/or special indemnities. At best, diligence gaps can consume management attention at a time when a company has little bandwidth to spare. At worst, they can detract from a company’s credibility and can have a meaningful impact on deal speed and certainty. Most issues are fixable, but the available solutions often narrow after a deal is already on the table. This article provides an overview of actionable steps leadership at mid- to late-stage private companies can take to make transaction readiness an ongoing discipline rather than a pre-signing scramble.
Set Up and Maintain a Virtual Data Room
Rather than waiting until a letter of intent is signed, companies should stand up and maintain a virtual data room (VDR) early, using records they already keep locally, and treat it as a living repository of critical corporate documents. Management teams that prepare to address anticipated diligence focus areas and maintain organized virtual records early are better positioned when a process launches than teams that start flat-footed. Companies can get a head start by asking outside counsel for a standard due diligence request list, which serves as an organizational and gap-identification tool, as well as an organized table of contents for their VDR. This ensures that documents are comprehensive and indexed by categories prospective investors and acquirers will expect.
The VDR should contain current, fully executed, and dated documents together with all amendments, statements of work, and side letters. Superseded and terminated agreements should be archived, not deleted or mixed with operative versions. One small but time-saving step in setting up a VDR is using a consistent and intuitive naming convention as documents are uploaded, which will help not only management but also third-party reviewers quickly navigate the VDR’s contents. Once a diligence process begins, access should be staged and subject to tiered permissions, with additional controls for competitively sensitive information, compensation data, and litigation files; privileged materials should be withheld or handled through a process designed to preserve privilege. Particularly when a potential buyer is a competitor, or when the underlying material is subject to confidentiality restrictions that do not permit sharing with a potential acquirer or investor, counsel should advise prior to upload and contemplate redactions, clean-team arrangements, and restrictions on downloading or printing. When in doubt, leave it out; it is easier to pause early and evaluate permissions and other protections than to pull back a document after it has been shared.
A word of caution: prospective investors now run AI review tools that can scan an entire data room in minutes, and while that process can generate false positives, it can also magnify every internal inconsistency across the VDR, including in the cap table, contracts, and other materials. As a best practice, keeping the VDR updated quarterly helps identify issues early and positions the company and management to earn credibility from the moment that transaction diligence begins.
Maintain a Corporate Record Book and Organizational Documents
M&A buyers and growth equity investors will expect clean and current corporate governance records. This means prospective investors will review: current versions of the certificate of incorporation (including all amendments) and bylaws; board and stockholder minutes; and fully executed, dated written consents. An improperly compiled consent with a missing signature page or date can cost the company meaningful time and resources to track down or, worse, require corrective action to cure. Every material corporate action should tie out to a corresponding board and/or stockholder approval, including equity issuances, option grants, director and officer elections, and subsidiary formations.
Companies should also at least annually confirm good standing in their state of incorporation and in every jurisdiction in which they are qualified to do business. Outside counsel can obtain verbal good standing confirmations from third-party service providers, often for a nominal or no cost to the company. Good standing lapses can trigger fees, taxes, and penalties and, in many states, can bar the company from bringing suit in local courts until the lapse is cured, although a lapse does not typically invalidate contracts executed while the company was not in good standing. For an additional layer of caution, companies can consider ordering lien and litigation searches from third-party service providers in the same set of jurisdictions.
Ensure Vigilant Capitalization Table Hygiene
The company should expect buyers or investors to request a current copy of the capitalization table and, in the case of an equity financing, a pro forma cap table reflecting the completed round. Most cap table hygiene issues exist well before a contemplated transaction and surface in the diligence process. Common hiccups include unsigned option grants, undocumented stock issuances, unrecorded convertible note draws, and inconsistencies between vesting schedules and employment terms. Cap table accuracy is key: a company’s representations about its capitalization are often treated as fundamental representations, giving buyers or investors the ability to claim breach even for minor discrepancies. Moreover, a messy cap table can be perceived as poor ownership discipline by the company or its management.
With assistance from outside counsel, the company should reconcile the cap table against the stock ledger and equity grant documentation, ensuring that every stock and option issuance is supported by board resolutions, grant agreements, evidence of payment of the exercise or purchase price, and, if applicable, an approved, unexpired equity incentive plan. Each option grant should also be supported by a current 409A valuation that supports the board’s determination of the fair market value of the underlying shares.
Importantly, companies should develop a clear understanding of how antidilution provisions operate and how change-of-control acceleration clauses (single-trigger and double-trigger) may affect the equity/distribution waterfall in a transaction. Modeling these scenarios in advance allows management to communicate the deal economics clearly to all stockholders and avoids last-minute surprises that can derail negotiations.
Understand Key Provisions in Material Contracts
Counsel for buyers and investors will expect the opportunity to review each contract that is material to the business. These typically include: contracts with key customers and suppliers above certain revenue or expense thresholds; license agreements; leases; employment and severance agreements with key personnel; and other contracts that are important to the business. These contracts often contain change-of-control consent triggers, rights of first refusal, out-licensing restrictions, most favored nation provisions, exclusivity, non-solicit, non-compete, and other restrictive covenants. In certain circumstances, a counterparty may have a notice, consent, or termination right in connection with a transaction. Accordingly, with the help of outside counsel, a company should be generally aware of which key agreements contain those provisions and should have a plan for obtaining consents or providing timely notice in advance of entering into a transaction process. Seeking consent late in the process can give leverage to the counterparty, which can increase overall costs and decrease deal certainty.
Confirm Intellectual Property Ownership and Assignment of IP
Depending on the company’s core business, clean IP title is often a significant driver of the diligence process. One consideration that comes up time and again is whether every founder, employee, and contractor who contributed to the company’s IP portfolio has executed an invention assignment agreement that assigns all intellectual property rights to the company. It isn’t uncommon for advisors and early contributors in early-stage companies, often compensated in equity, to miss the assignment paperwork altogether, or to execute, but not date, the assignment. Any gaps in assignment should be addressed ahead of the buyer or investor diligence process, which can be done with the help of outside IP counsel. Companies should also routinely conduct an audit of open-source software usage to confirm compliance with applicable license terms.
Maintain Compliance with Industry-Specific Regulatory Requirements
Companies operating in regulated industries, such as healthcare, financial services, energy, and government contracting, should confirm that all material licenses, permits, and registrations are current and in good standing. Identifying regulatory approvals or notices that would be required in connection with a change-of-control or assignment of a license can avoid an additional layer of investor diligence caused when gaps are identified later in the deal negotiation process. Regulatory non-compliance discovered during diligence can significantly delay closing or reduce deal certainty.
As AI vendors become integral to business operations, their potential bankruptcy creates complex challenges under a Bankruptcy Code that has yet to fully adapt to AI technology. The first of a two-part series, this article focuses on intellectual property considerations: specifically, how companies that license AI tools or models can protect their continued access when a vendor enters bankruptcy. Among the key risks is a debtor’s ability to reject executory contracts, which could strip away the ongoing services that make a licensed AI tool usable, even where the bare license itself survives. Proactive contractual measures, including escrow arrangements and source code and deployment rights, can mitigate these risks before a vendor crisis occurs.
The second of a two-part series, this article examines consumer privacy risks and strategic implications that arise when an AI vendor files for bankruptcy. Key issues include how trained models, fine-tuned weights, and training data derived from sensitive customer-provided data may be treated as bankruptcy estate assets that can be sold to third parties, how those model artifacts can enable reconstruction or extraction of personally identifiable data even without a sale of the raw data, and whether courts will classify AI vendors as “critical vendors” or “utilities” — designations that carry significant consequences for service continuity and restructuring negotiations. Companies should address these risks proactively through contract terms and vendor risk management protocols before a crisis occurs.
In an IPO, due diligence is best understood as the working group’s disciplined effort to (1) identify and assess potentially material issues in the company’s business, history, and financial reporting, (2) translate those issues into accurate and appropriately balanced disclosure in the prospectus and related offering communications, and (3) pressure-test factual assertions so the offering record can be supported if challenged later.
A thorough due diligence investigation is designed to identify not only “problems,” but also facts that could disappoint investors if they emerge later without having been fairly described. Because an IPO is often the first time a company describes its business, results, and risks in significant detail, investors rely heavily on the prospectus as the principal disclosure document when evaluating the company and the investment.
The Due Diligence Investigation Runs from Day 1 Through Pricing and Closing
Companies should begin preparing their documentary data room in advance of kicking off an IPO process by identifying employees with subject matter ownership and assigning responsibility for collecting the relevant materials. Documents should flow to a single point of contact who will ensure materials are loaded into an organized virtual data room.
At the organizational meeting, having a substantially complete data room enables the working group to begin immediately and complete initial document review earlier, allowing diligence to run in parallel with drafting. This helps avoid a common frustration: marketing-forward disclosure drafted early in the process later must be rewritten based on diligence findings. Ideally, the working group incorporates diligence input as the disclosure is developed.
While the most intensive diligence typically wraps up around the initial SEC submission or filing, the work needs to continue through pricing and closing (including effectiveness and any bring-down diligence). New disclosure added in subsequent filings should be vetted, and new information and documentation should be added to the data room on a rolling basis. Maintaining an open issues log, with clear owners, next steps, and deadlines, helps avoid last-minute diligence scrambles that can disrupt the timing of amendments and the overall IPO schedule.
No Surprises
While it may not be enjoyable to share all of the company’s more challenging issues, companies should strive to ensure that underwriters’ counsel is not learning about issues for the first time late in the process. Early identification and resolution also avoids a common dynamic: issues are significantly easier to manage if the company or its counsel shares relevant details early, along with appropriate context, so that matters can be evaluated and framed appropriately from the outset.
This approach also protects against “over-reactions,” where diligence counsel believes it has identified a significant issue and therefore expands review and follow-up. That dynamic can devolve into time-consuming exercises and unnecessary “all-hands” calls, often avoidable where the issue was presented proactively rather than discovered.
Create a Record and Document Support
A thorough diligence record maintained by counsel helps to track progress, monitor efficacy, and create an audit trail in case of a later challenge.
Counsel should maintain a back-up book linking factual statements in the prospectus to supporting sources. Subject matter owners at the company should prioritize responsiveness to support requests and avoid treating the process as a check-the-box exercise.
The process itself should also be documented. Counsel can circulate written questions for diligence calls in advance and cover those questions on the call. A memo should capture attendance, and follow-up items should be tracked to resolution. The open issues log should be shared among the company, its counsel, and underwriters’ counsel and updated regularly.
Don’t Rely on the “Belief” Crutch
One of the most repeated phrases in an IPO prospectus is “we believe.” A statement of belief can be an appropriate way to express judgments or expectations that cannot be definitively verified, and it can help avoid overstating certainty. However, a belief qualification is not a free pass to make claims that are not supportable. Where management expresses a belief, there should be a reasonable basis for that belief and the diligence process should confirm that basis exists and that the disclosure is appropriately calibrated.
For example, a biotechnology company developing a new drug may state in the prospectus: “We believe our product candidate may offer clinically meaningful benefits to patients.” While there may not yet be clinical data demonstrating that outcome, there should be a sound scientific rationale and supporting pre-clinical evidence that provides a reasonable basis for the statement as framed.
Check with Experts
Counsel will review large volumes of material as part of the investigation, but that does not guarantee the working group will fully understand highly technical, specialized, or cutting-edge topics. In appropriate cases, diligence should include calls with relevant subject matter experts (whether technical, regulatory, cybersecurity, accounting, tax, or otherwise) to ensure the record supports the disclosure.
Diligence is More Than Lawsuit Avoidance
A properly conducted due diligence investigation can reduce the likelihood of securities claims for IPO participants. It cannot eliminate the possibility of litigation, but a thorough process can create a defensible record for those who may need it.
The credibility of the working group is also at stake. Underwriters care deeply about successful offerings. Their reputation is their biggest asset and missed diligence issues can cause real reputational harm.
More broadly, accurate IPO disclosure is a long-term asset. Companies will live with their disclosure regime as public companies, updating it regularly under ongoing investor scrutiny. Strong diligence helps public company executives spend more time executing their strategy and less time responding to avoidable surprises.
Moving ahead with an IPO is a major commitment of time and resources. The companies that execute efficiently are the ones that start managing the process well before the organizational meeting by building a realistic base-case timeline, staffing internal owners, and making a small set of initial decisions that drive the critical path.
Construct the Base-Case Timeline Around Key Milestones
A useful approach is to anchor the company’s IPO timeline around three broad windows. At the outset, establish a target IPO pricing date and construct the rest of the timeline to make that achievable. Once determined, establish a target date for the initial confidential submission of the registration statement and a date for the organizational meeting.
- Readiness planning: preparing for the organizational meeting. The company’s approach to readiness planning can either pave the way for a more efficient process or inadvertently create bottlenecks that cannot be fixed on the back-end. The length of the readiness stage can vary, and more time means better preparation. Completing the key readiness workstreams before the organizational meeting is critical to staying on schedule. As part of readiness planning, companies should identify any third-party consents, waivers, or contractual constraints that may require outreach and turnaround time, because those items can create non-negotiable lead times that compress the schedule later.
- Confidential execution: organizational meeting to initial confidential submission. This is typically the most drafting-intensive period and often drives internal resourcing needs. The company’s internal IPO team will be heavily engaged in the process and the IPO demands effectively create a second job for them on top of their day-to-day responsibilities. It’s critical that the company’s internal and external staffing is fully engaged and prepared following the organizational meeting.
- SEC process: initial submission to public filing, launch/roadshow, and pricing. Companies have the least amount of control over this period as it depends heavily on SEC comment cadence and market performance. In practice, a slower or more complex SEC comment cycle can require additional confidential submissions and can also create financial statement update pressure as quarters roll, which can affect both timing and workload. Addressing challenging SEC comments is often best handled in the confidential submission process, which typically means additional confidential submissions and more time, putting pressure on hitting a financial statement staleness window. External factors are rarely predictable in advance, so the best planning will get the company to the public filing on time and enable business leaders to make a go-forward decision on the planned schedule.
Even in a well-run process, timelines move. Treat the company’s base case as a model that gets updated as the process evolves from factors that the company can control toward factors that the company cannot control.
Assign Ownership
Effective IPO execution requires effective organization. The plan and a company’s ability to hit its milestones become manageable with clearly defined internal roles and assignments given to those with the time and resources to properly manage them. A few readiness decisions tend to pay outsized dividends:
- Create a small internal IPO working group. This should include key decision-makers and functional leaders with responsibilities that touch upon the IPO process. The working group should stay in close contact through regularly scheduled meetings with internal and outside counsel to ensure accountability and focus on key workstreams.
- Identify subject matter owners for each workstream. Identify an individual to take ownership of each specific subject matter workstream, including communications, data room management, finance, accounting, legal, compensation, IP, tax, and regulatory, and then make them responsible for the day-to-day management of their workstream.
- Designate a lead draftsperson and a master-document process. Working with the company’s outside counsel, determine a drafting plan for the registration statement with an initial focus on the business section, the management discussion and analysis (“MD&A”), and financial statements. Company counsel can draft much of the registration statement, but someone at the company who has (i) an in-depth knowledge of the company’s business and mission, (ii) drafting and management skills, and (iii) time, should take the lead on overseeing the drafting of the business section. Assigning an owner enables narrative coherence that is not possible with multiple people drafting independently.
- Corporate housekeeping. Assign a tech-savvy person to oversee the due diligence document collection system to ensure the data room is complete and organized. This individual can also serve as a documentation coordinator for cap tables, stockholder consents, lockup signatures, public company policies, and employee education materials.
The practical theme: clarity on ownership of workstreams and tasks prevents the “everyone is responsible, so no one is responsible” dynamic that turns into schedule compression later. Each workstream owner should have clear escalation paths and decision rights (or access to decision-makers) to avoid bottlenecks and ensure key decisions are given the right attention and made at the right time.
Hire Advisors
Companies often treat the banking process as a separate track from readiness planning. It is not. Several early choices directly affect the company’s ability to run a controlled timeline:
- Underwriter selection and coverage strategy. Underwriter selection is one of the most important early decisions because it shapes execution roles, staffing, and investor positioning. In evaluating banks, companies should focus not only on senior coverage, but also on (i) sector fluency, (ii) the experience and availability of the day-to-day execution team, and (iii) the bank’s ability to support the company’s investor narrative through launch and aftermarket. A strong execution bench matters because it directly affects cadence, responsiveness, and how efficiently the working group can run.
- Outside Counsel. The IPO is also an opportunity to confirm that the company will have an IPO-ready legal team with the capacity and continuity to run a fast, iterative drafting and diligence process. Regardless of whether the company uses existing counsel or adds new counsel, the key is to ensure the team has deep IPO experience, the right specialist bench, and the ability to maintain a disciplined process from the organizational meeting through pricing and closing.
- Compensation Consultants. Public company executives are compensated differently than private company executives. Compensation committees will insist on getting high-quality input from experienced compensation advisors before making any compensation decisions. Additionally, structuring public company equity compensation plans is a significant and strategic undertaking. These plans require stockholder approval, which becomes significantly more challenging as a public company, so designing and implementing a plan to take effect alongside the IPO is essential and getting the details right will make life as a public company substantially easier. Lining up the company’s compensation advisors early enables them to give the right guidance at the right time.
- Communications/Investor Relations. While much of the IPO process is governed by what companies cannot communicate, developing a public company story and hitting the ground running as a public company with a functioning Investor Relations (“IR”) infrastructure will make the transition significantly easier. Companies will want IR professionals who are familiar with the story and involved in crafting it so that they can communicate consistently and clearly once public.
A good planning posture is to treat “advisor selection” as a gating item: once selected, the team can finalize the calendar, set drafting cadence, and schedule key events (including analyst education and investor-facing prep).
Financial Statements, Accounting, and Controls
The biggest internal constraint on an IPO timeline is the availability of audited financial statements. The SEC has strict rules regarding the inclusion of audited financial statements in registration statements, and missing a filing window before a staleness date can have significant consequences for execution of a timeline.
Key decisions and actions that typically belong in the earliest phase of readiness planning include:
- Audit readiness and Public Company Accounting Oversight Board (“PCAOB”) planning. It’s never too early to have financial statements audited under PCAOB standards. If a company thinks an IPO in the next two years is a possibility, then there should be a plan to produce the financial statements.
- Identify and resolve complex accounting issues. Complex accounting issues will require careful analysis and likely involve working with the national office of the auditor. It’s a time-consuming process both to analyze and resolve the issue and then complete the audit and draft financial statements. For discrete, high-risk accounting judgments, companies, in coordination with auditors and counsel, should consider early on whether SEC consultation or pre-clearance may be appropriate, as unresolved accounting issues can materially disrupt an IPO timeline.
- Internal controls and Sarbanes-Oxley Act (“SOX”) planning. Developing internal controls is an intensive process that requires an experienced staff and implementation of complex enterprise reporting systems that need to be deployed across the organization. Having a team ready to handle the rigors of public company reporting before going public is essential, and the earlier they are involved, the better.
The practical point: if finance readiness lags, everything becomes reactive. The financial statements and controls work cannot be “crammed” without creating risk.
Plan the Drafting Strategy
The best registration statement drafting processes are the ones where the company arrives at the organizational meeting with (1) a solid draft of the business section that will enable productive drafting sessions, (2) draft financial statements, and (3) a clear drafting plan. A few decisions matter disproportionately:
- Business section planning. This is the most time-consuming drafting exercise and will be the focal point of a substantial portion of the drafting sessions. Arriving at the organizational meeting with a draft that has a clear narrative will make those drafting sessions significantly more productive. It is substantially easier to refine a message in a drafting session than to write new text in a group setting.
There are different approaches to producing the first internal business section draft, and it’s a useful exercise to discuss the company’s plans with outside counsel. The main point is to formulate a plan and see it through all the way to the organizational meeting.
- Material contracts and redaction planning. The company will likely need to file certain material contracts with the registration statement and will likely want to redact commercially sensitive or confidential information from those contracts. This requires coordination with the contractual counterparty for review. As this requires divulging IPO plans to a third party, the timing of this outreach needs to be carefully considered, but it cannot be left until the last minute because it can become a negotiation process.
- Collect source material. If the company expects to cite third-party sources (market data, industry reports) or discuss internal, non-financial metrics, the company should start collecting those sources and consider how they will be used and supported. These are all key diligence materials, and maintaining sources while drafting can go a long way toward running diligence in parallel with drafting to avoid rewriting the business section if later diligence doesn’t check out.
Drafting is time-consuming and is often more challenging than expected. Private companies do not have prospectus-ready disclosure, so a significant amount of content needs to be created, and that content needs to live up to intense scrutiny that comes along with strict disclosure liability in an IPO. Early effort makes it less painful.
The timeline benefit is straightforward: once the narrative architecture and key performance indicator definitions stabilize, drafting cycles compress; until then, each diligence issue and SEC comment is more likely to trigger downstream rewrites that consume time and management bandwidth.
Plan Ahead for Communications
IPO communications restrictions and “quiet period” discipline are schedule issues, not merely legal issues. The company’s communications calendar (conferences, investor touchpoints, press, social media, internal communications) can create avoidable friction if not planned early. Communications discipline is a timeline issue because avoidable public statements, inconsistencies, or unsupported claims can force last-minute disclosure revisions or create heightened scrutiny at exactly the point in the process when timing is most sensitive.
A disciplined approach typically includes:
- Build a communications schedule. The schedule should cover all planned external events during the IPO period and the first months as a public company.
- Calibrate investor communications. Work closely with counsel to only communicate what is permitted and supportable, with particular care around the risk that public statements get amplified by analysts. Be mindful of investor and third-party consents and plan outreach that is not too early and not too late.
- Tighten internal communications. Provide appropriate guidance at key milestones to employees (including the first confidential submission and the first public filing). How early to inform the whole company is a judgment call that can vary depending on the size of the company, but in the pre-organizational meeting stage, it is generally advisable to keep IPO plans to those with a need to know.
The planning theme: communications discipline reduces the risk of last-minute issues that force drafting changes or create unnecessary SEC sensitivity.
A Note on AI in the IPO Process
Generative AI can be useful in producing some of the “boilerplate” sections of the registration statement and can be useful in incremental drafting (paragraphs, not pages) using structured source materials in an iterative manner. Any AI-generated drafting should be verified against source materials and the company’s actual records, because speed without substantiation can create avoidable disclosure risk and rework later in the process. For example, uploading one slide from the company’s pitch deck into an LLM and using a thoughtfully constructed prompt can produce one or two paragraphs of prospectus-style disclosure that can serve as a useful starting point for human-powered drafting.
“Conversion” drafting is also becoming increasingly used. For example, summary financial sections or MD&A tables can be populated from completed financial statements using AI tools. These uses build drafting efficiency, but they are not yet (as of early 2026) revolutionary.
Companies should be mindful of confidentiality when using AI and should ensure that employees are using a closed enterprise system and not a public-facing generative AI tool.
The Court of Justice of the European Union has clarified whether a health-related product counts as a “medical device” in the EU, which determines whether the heavy compliance obligations of the Medical Devices Regulation apply. In Case C-427/24, Diagramm Halbach, the Court held that the analysis has two parts: what the manufacturer says the product is for, drawn from labeling, instructions, and marketing, and whether the product objectively performs one of the specific medical functions the regulation lists, such as diagnosis, monitoring, or treatment of disease. Marketing claims should not be considered in isolation and may not pull a product into the regime if it does not actually perform a medical function, and equally a company cannot avoid the rules by staying quiet about an obvious medical use. For founders building software or AI-enabled health tools, the ruling sharpens the line between administrative or organizational features and functions that genuinely inform clinical decisions, and that distinction determines whether CE marking and conformity assessment are required before selling in the EU.
Not every liquidity transaction is a “Tender Offer.” Many private company secondary transactions are one-off, individually negotiated sales of shares by a founder, employee, or early investor to a new or existing investor. These transactions avoid much of the regulatory apparatus discussed in our companion article on Tender Offers, but they are far from unregulated and raise their own legal, tax, and practical considerations for the seller, the buyer, and the company.
Secondary Sales vs. Tender Offers
If a secondary transaction does not meet the definition of a “Tender Offer” (a determination made under the Wellman test discussed in another Catalyst article), the Tender Offer rules – including those mandating minimum disclosures, a minimum offering period, withdrawal rights, and others – will not apply. Instead, the terms of each transaction are negotiated between the buyer and the seller, with the company sitting in the middle as the party whose consent is needed and whose stock records must reflect the transfer.
Documentation and Settlement Mechanics
Secondary sales are typically documented in a secondary stock purchase agreement negotiated between the buyer and the seller. Although such agreements typically follow a similar format, they are usually tailored to the transaction at hand, addressing sale mechanics, representations and warranties, waivers and disclaimers, and any additional rights, and they typically feature company consent, the waiver or expiration of rights of first refusal and co-sale rights, and the allocation of transfer costs and taxes.
Settlement mechanics deserve more attention than they often receive. Because private company shares are not held through a clearing system, closing is a coordinated exercise among the buyer, the seller, and the company (or its cap table administrator), and it can get complicated if the seller must first exercise stock options or convert other securities. In that case, the mechanics must often provide an advance of the exercise price to the seller (whether by the buyer or the company), the company’s processing of the exercise, and the calculation and processing of any associated tax withholdings. The agreement should spell out the sequence of events and the responsibilities of each party clearly; note also that option exercises may take several days to process, so the timeline should be clear and precise.
Securities Law Considerations
Exemption from Registration
As these are still transactions in private company stock, they must be conducted in reliance on a valid exemption from the registration requirements of Section 5 of the Securities Act of 1933 (the “Securities Act”). Because the seller is not the issuer, the question is whether the seller can resell its shares without being deemed an “underwriter.” Two approaches have become the most common over the years:
- The “Section 4(a)(1½)” exemption: Historically the most commonly used exemption, especially prior to the introduction of Section 4(a)(7), this is a product of practice and case law rather than statute. The idea is that a resale by a non-issuer should be exempt under Section 4(a)(1) (which exempts transactions by persons other than issuers, underwriters, and dealers) so long as it is conducted in the manner required of an issuer’s private placement under Section 4(a)(2): generally, a sale to a limited number of sophisticated or accredited purchasers with access to information about the issuer, with no general solicitation and with the purchaser taking the shares for investment. The full list of conditions is longer, and although the Section 4(a)(1½) exemption is typically viewed as a well-trodden path, it requires careful analysis and structuring of each transaction. Note also that there is no statutory safe harbor and no preemption of state blue sky requirements when this exemption is invoked.
- Section 4(a)(7): Added to the Securities Act by the FAST Act in 2015, Section 4(a)(7) effectively codified the Section 4(a)(1½) exemption into the Securities Act, although it introduced a number of additional requirements (including that each purchaser be an accredited investor, that no general solicitation be used, and that the securities have been outstanding for at least 90 days). Notably, where the issuer is not a reporting company, the seller must make available to the purchaser prescribed information about the issuer, including a description of its business, the names of its officers and directors, and its most recent balance sheet and two years of income statements. Securities sold under Section 4(a)(7) are “covered securities” exempt from state registration requirements, although they remain restricted securities in the buyer’s hands. Section 4(a)(7) was not intended to invalidate the Section 4(a)(1½) exemption when it was introduced and is typically viewed as a more certain path to an exemption for individual secondary transactions.
There are other exemptions that may be available to sellers, including Rule 144, but these are much less frequently used due to compliance complexity and limited availability in light of the typical structure of such transactions.
Antifraud – Rule 10b-5
Secondary sales are frequently marked by an asymmetry of information between the parties. An employee seller may know the company’s operations but not its financing plans; an investor buyer may sit on the board and know both. Whatever the direction of the asymmetry, Rule 10b-5 still applies to the purchase or sale of any security – public or private – and prohibits material misstatements and omissions in connection with the transaction. Insiders who trade with less-informed counterparties while in possession of material nonpublic information face real exposure, as does a company that facilitates such a trade. Parties commonly manage this risk through “big boy” letters and non-reliance provisions, in which each side acknowledges that the other may possess undisclosed material information. These provisions help but are not a complete defense, as their enforceability often turns on the facts and circumstances and their specific wording. As with Tender Offers, any information material to an investment decision should be disclosed to both parties before they commit to the transaction (including by the company, even though it is not a direct party to the transaction).
Corporate Law Considerations
Transfer Restrictions and Protective Provisions
Many VC-backed companies restrict transfers of their shares to third parties. These restrictions typically include a right of first refusal in favor of the company and major investors, co-sale rights, a board consent requirement, and – especially for preferred stock – protective provisions requiring the approval of a majority of the preferred holders for specified actions. Each must be reviewed, waived, or complied with before closing. Protective provisions are easy to overlook: a transfer of shares, a repurchase, or other distribution by the company on account of its stock, or a sale large enough to change the outcome of a class vote may require consents beyond the board. Larger sales should also be checked against “Deemed Liquidation Event” definitions and interested party transaction rules.
Capital Impairment and Distribution Requirements
Where the company itself is the buyer, the transaction is a repurchase and is subject to statutory limits on distributions. Under Delaware law, for example, a corporation may not repurchase its shares when its capital is impaired or when the repurchase would cause impairment, and directors who approve an unlawful repurchase face personal liability. Debt agreements and preferred stock terms frequently add restrictions on repurchases and restricted payments. A company repurchase should therefore be supported by a board determination of available surplus and reviewed against all contractual covenants and protective provisions.
Using the Company’s Consent as Leverage
Because the company’s consent is almost always required, a secondary sale is an opportunity for the company to tidy up its relationships with both the incoming buyer and the departing seller. Companies regularly condition consent on the following:
- Additional obligations on the buyer, including:
- A joinder to the company’s voting, right of first refusal and co-sale, and drag-along agreements, often without the information or registration rights afforded to lead investors.
- A market standoff or lock-up agreement in anticipation of an IPO.
- Confidentiality obligations and limitations on further transfers of the shares, including to competitors.
- Releases and confirmations from the seller, including:
- A general release of claims against the company.
- Confirmation of the seller’s remaining equity, if any.
- Reaffirmation of confidentiality, invention assignment, and other continuing obligations, particularly for current and former employee sellers.
Tax Considerations
Tax consequences to both the seller and the buyer deserve special attention and are too often addressed only after the price has been agreed. For the seller, the central questions are whether the gain is capital or ordinary, whether the holding period qualifies for long-term treatment, and whether the shares are qualified small business stock eligible for the Section 1202 exclusion (i.e., QSBS). Employee sellers face additional issues: a purchase price above the company’s most recent 409A valuation may be treated in part as compensation; shares acquired on exercise of incentive stock options may suffer a disqualifying disposition; and so on. Both sides should understand these issues before the price is set, and structuring matters. Parties also often negotiate separate tax obligations and indemnities directly into the agreement.
Secondary sales offer flexibility that Tender Offers do not, but that flexibility comes with the burden of getting each transaction right individually. While that burden is real, it also carries a benefit: the parties can be more thoughtful about structuring, and the company can control timing and negotiate for terms that benefit it.
With AI becoming central to business strategy, the legal questions surrounding it are keeping pace. As companies race to build and deploy AI systems, a critical question is emerging: Do their teams understand the data that powers these tools well enough to manage the risks? For some, the learning curve has come with real legal consequences.
Two categories of AI data sit at the center of these questions: training data and grounding data. Each raises meaningfully different legal and contractual concerns. For organizations working with AI developers and building their own models, understanding the distinction is an increasingly important part of getting AI right.
Training Data: The Textbook
Training data refers to the large datasets used during the development of an AI model. During training, the model analyzes large quantities of information, such as text, images, or software code, to identify patterns that allow the model to generate outputs when responding to prompts.
Think of training data as a student’s textbook.
Once students have read a textbook, they don’t carry it around to solve problems.
Training datasets can originate from a variety of sources, including:
- publicly available internet content, such as websites or online forums;
- digitized books, academic journals, and research publications;
- open-source software repositories;
- commercially licensed databases; and
- proprietary enterprise datasets (typically owned by the developer or provided to the developer by an external partner, customer, or collaborator).
Because these datasets often contain copyrighted or proprietary materials, and potentially personal information or other regulated data, the legal rights associated with training data can vary significantly. In some situations, the AI developer may own or curate the dataset itself (including, with respect to curation, to mitigate regulatory risks by using deidentified or synthetic data). In others, the underlying materials may remain owned by third-party publishers, content creators or owners, or database providers (and may still include data subject to various regulatory regimes).
Companies developing AI models internally may also incorporate proprietary operational data, customer information, or research datasets. When external collaborators are involved, training data may be governed by contractual agreements that define ownership, permitted uses, and rights to derivative models and datasets.
Importantly, training data is typically used during the model development phase. Once the model has been trained, the system generally no longer needs direct access to the underlying training dataset in order to function. The distinction can become relevant when licensing arrangements change or when organizations reevaluate their data governance strategies after a model has already been deployed.
Grounding Data: The Exam Fact Pattern
Grounding data serves a different purpose. Rather than teaching the model general patterns, grounding data provides contextual information at the time a model generates a response to a prompt. Organizations frequently use grounding to ensure that AI systems reference authoritative or up-to-date sources when producing outputs.
Think of grounding data as an exam fact pattern with specific facts and context.
Grounding data can include:
- internal company policies or compliance manuals (e.g., an employee handbook retrieved to answer an HR query);
- corporate knowledge bases and document repositories (e.g., past deal memos surfaced during contract negotiation);
- regulatory guidance or industry standards (e.g., Food and Drug Administration guidance retrieved to support a compliance question);
- proprietary databases (e.g., a licensed case law database queried at inference time); and
- user-provided documents or uploaded files (e.g., a contract the user uploads and asks the AI tool to summarize).
To make this concrete: When an attorney asks an AI tool, “What are the notice requirements under this contract?” the user input is that question. The grounding data is what the system automatically retrieves behind the scenes to answer it (e.g., the specific contract, the firm’s internal playbook, a relevant regulatory database). The user does not see that retrieval, but it drives the response.
A common implementation approach for grounding data is retrieval-augmented generation (RAG), where an AI system retrieves relevant documents and information from a database or search index and incorporates those materials into its response.
For businesses deploying AI tools internally, grounding can play an important role in maintaining guardrails around model outputs. By referencing trusted materials, grounding mechanisms can help improve model accuracy and reduce the likelihood that unsupported or misleading responses are generated.
From a legal perspective, grounding data presents a distinct set of considerations because it is actively retrieved and potentially reproduced at the time of each query rather than absorbed into the model’s parameters during the development phase. This distinction also has practical consequences postdeployment: A trained model generally continues to function even if access to its training data is later lost or a license expires, because the learned patterns are encoded in the model’s weights. Grounding data, by contrast, must remain continuously accessible, and loss of access or limitations on access to support risk management needs (e.g., cybersecurity, privacy, or other data governance purposes) may directly impair the model’s outputs.
The following table summarizes the key distinctions between training data and grounding data.
Litigation Trends: Focus on Training Data
To date, the most significant AI copyright decisions have focused on training data practices — specifically, whether copying protected works to build or improve a model is authorized and lawful. No court has yet issued a comparable ruling centered on grounding data or RAG systems, though legal risks in that area are building, as discussed below.
In Thomson Reuters Enterprise Centre GmbH v. ROSS Intelligence Inc., Thomson Reuters, the owner of Westlaw, sued ROSS Intelligence, a developer of an AI-powered legal research tool, alleging that ROSS used Westlaw headnotes as training data. ROSS argued that its use of the headnotes to train its model constituted fair use because the system learned from the material without reproducing it (i.e., without including the material in outputs). The U.S. District Court for the District of Delaware rejected that argument (in part) and found infringement, emphasizing that the use of proprietary, curated content to train a competing product weighed heavily against fair use. The decision suggests that training on copyright-protected materials, particularly where the resulting system functions as a market substitute, can give rise to copyright infringement risk even if the model does not use the original content in its output. Notably, the Court explicitly mentioned in its holding that only nongenerative AI was at issue in this case.1
Two decisions issued in June 2025 by the U.S. District Court for the Northern District of California reached different conclusions in cases involving generative AI and together illustrate how fact-specific the fair-use analysis has become.
In Kadrey v. Meta Platforms, a group of authors sued Meta alleging that training its LLaMA large language model on copyrighted books constituted infringement. The Court found for Meta, concluding that the training use was a highly transformative fair use. The Court also found that the plaintiffs had failed to develop sufficient evidence of market harm (one of the central fair-use factors) and analyzed the copying and the training as a single, unified act rather than as separate instances of reproduction and use. The decision is notable, but its reach is limited: The Court declined to issue a broad ruling that AI training on copyrighted materials is categorically fair use, and the outcome turned heavily on the specific evidence presented (or lack thereof).2
In Bartz v. Anthropic, also decided in June 2025, the Court drew a sharper line based on how training copies were obtained. The Court found that training the Claude model on lawfully acquired or purchased books constituted fair use but declined to extend that protection to a central library Anthropic had compiled from pirated sources. The distinction (fair use for legally obtained copies, no fair use for pirated ones) has practical implications for how AI developers source and document their training data. The case settled for approximately US$1.5 billion following the ruling.3
Taken together, ROSS, Kadrey, and Bartz reflect a landscape in which outcomes turn on particular facts: what kind of content was used, how it was obtained, whether the resulting system competes with the original market, and what evidence of harm was presented. No appellate court has yet weighed in on the merits of AI training and fair use, meaning none of these decisions are binding precedent beyond its own jurisdiction. Significant cases remain in active litigation, including The New York Times Co. v. OpenAI and Microsoft in the Southern District of New York (the first major generative AI case brought by a news organization) and Disney v. Midjourney in the Central District of California, both of which are pending.4, 5 The appellate trajectory of ROSS, which is on interlocutory appeal to the Third Circuit, may also provide the first appellate guidance on these questions. For now, the law remains unsettled, and companies with significant exposure should monitor developments closely.
RAG Systems, Scraping, and Emerging Risks
As AI systems increasingly rely on grounding techniques such as RAG, new legal issues are beginning to emerge. Many RAG implementations retrieve information from external sources in real time, which may involve web scraping, application programming interface (API) access, or database queries. These practices raise potential risks that differ from traditional training-data disputes. That distinction drives the broader IP risk profile:
- Terms of Service — RAG systems that query external sources in real time may exceed what a website or API permits.
- Circumvention of access restrictions — retrieving content from paywalled or restricted sources can trigger additional liability beyond copyright (e.g., risks related to computer crime, privacy, or cybersecurity laws).
- Output reproduction — because retrieved text may appear verbatim in model responses, copyright infringement risk arises at the moment of each query, not just during development.
- Contractual limitations on database usage — licensed databases often do not contemplate AI systems incorporating their content into generated outputs, creating potential breach risk.
Organizations deploying RAG-based systems should therefore evaluate how their AI models retrieve and present external information. Practical risk-mitigation steps may include prioritizing vetted and licensed data sources, reviewing website terms before scraping content, and implementing technical safeguards that limit the amount of retrieved material incorporated into model outputs.
Contractual Considerations
Understanding the legal distinctions between training data and grounding data has direct implications for how organizations should structure their AI-related agreements. The two data types raise different contractual concerns, and companies entering into AI development or deployment arrangements should evaluate each category separately.
Training Data Agreements
When training data is sourced from third parties, whether licensed databases, research partners, or content providers, agreements should address several core issues. First, ownership and chain of title should be clearly defined: who owns or controls each component of the dataset, and who owns any derived datasets, curated subsets, or annotation outputs produced during the development process. This is particularly important where multiple parties contribute data or where the dataset is assembled by a third-party curator.
Second, the scope of the license should be carefully defined. Agreements should specify which model versions may be trained on the data, whether use is limited to internal deployment or extends to commercial products, and whether fine-tuned derivatives of the trained model fall within the license. Restricting sublicensing of training data to third parties is also worth addressing explicitly, particularly in multiparty development arrangements.
Third, agreements should address model ownership. Whether the trained model constitutes a derivative work of the training data (and if so, who owns it) is a contested question. Parties should allocate model ownership explicitly rather than leaving it to inference. This can be a significant negotiation point, particularly where a data provider is contributing proprietary content that materially shapes the model’s capabilities.
Finally, training data agreements should include representations and warranties from the data provider confirming that it has sufficient rights to license the dataset and that the licensee’s use of the dataset as permitted will not infringe third-party intellectual property rights. Indemnification provisions covering third-party infringement claims arising from the training data are increasingly standard in well-negotiated AI development agreements. Companies should also consider what happens when a training data license expires or is terminated postdeployment. As discussed, a trained model typically continues to function even without ongoing access to its training data, but audit rights and data deletion obligations may still apply and should be addressed in advance.
Grounding Data Agreements
Grounding data raises a distinct set of contractual issues, driven by the fact that grounding data likely must remain accessible throughout the life of the deployment. Unlike training data, which is consumed during the build phase, grounding data is actively retrieved on each query, making ongoing access a functional dependency rather than a historical one.
License agreements covering grounding data should be drafted to cover runtime retrieval specifically, not just one-time processing or storage. Traditional database licenses often do not contemplate an AI system incorporating retrieved content into generated outputs, a use that is meaningfully different from a human reading a record. Companies should audit their existing data licenses to confirm they extend to AI inference use before deploying RAG-based systems that draw on licensed sources.
Because grounding data may be directly reproduced in AI outputs, agreements should also address output ownership and attribution: whether the data provider retains any rights in AI-generated responses that incorporate its content and whether attribution or citation requirements apply. This is an emerging area, and parties should not assume that silence in a license means no rights are retained.
Where enterprise grounding data contains sensitive business information or trade secrets, confidentiality and data security provisions are essential. Agreements with AI vendors should specify how grounding data is stored and accessed, who within the vendor’s organization can retrieve it, and whether the vendor may use the data to train or improve its own models. This last point is often buried in vendor terms of service and deserves careful review.
Finally, because loss of access to grounding data can immediately impair a live AI system, agreements should include provisions addressing continuity and license termination. This may include uptime and availability service-level agreements for critical data sources, step-in rights if access is revoked, and data portability provisions allowing the organization to migrate to alternative sources without disruption. The operational stakes here are often higher than with training data, where the model continues to function even after the underlying data is no longer accessible.
Key Takeaways for Businesses
- For companies adopting AI technologies, data governance is a critical component of responsible AI deployment.
- Training data raises questions about IP rights, licensing, and model development practices, as well as privacy, regulated data, and cybersecurity-related risks.
- Grounding data affects how AI systems operate in real time and how organizations maintain reliability and control over model outputs and may present similar privacy, regulated data, and cybersecurity risks.
- As AI adoption continues to expand across industries, companies that carefully evaluate both aspects of the AI data pipeline will be better positioned to capture the technology’s benefits while minimizing legal and operational risk.
AI is reshaping drug discovery and development by accelerating research timelines, optimizing clinical strategies, and improving manufacturing efficiency, but adoption brings a complex web of legal considerations that life sciences companies must navigate. This article, published in Drug Discovery World, examines regulatory pathways for AI-assisted drug development, intellectual property ownership challenges, and data protection and privacy obligations arising from AI model training, and outlines practical steps organizations can take to capture the benefits of AI while managing regulatory, IP, and contractual risks.
Despite cautious optimism following an upturn in biotech M&A in mid-2025, development-stage biotech companies continue to face significant financial headwinds including increased layoffs, higher borrowing costs, healthcare pricing reforms, and ongoing market correction following the pandemic-era investment boom. Companies should take proactive steps to build financial resilience: routinely identifying clinical and regulatory inflection points that could threaten liquidity; maintaining robust contingency plans that account for insolvency regimes in all relevant jurisdictions; engaging in fact-finding during periods of financial health to identify potential cash shortfalls; evaluating hypothetical liquidation scenarios early to understand timing and resource requirements; running structured strategic alternative processes (including asset sales, mergers, or licensing deals) well before reaching a crisis point; and budgeting for the time and cost of navigating financial distress, including the reality that dissolution processes can take three or more years to complete.
On July 24, 2025, the California Privacy Protection Agency approved sweeping new regulations covering cybersecurity audits, risk assessments, and automated decisionmaking technologies (ADMT), pending review by California’s Office of Administrative Law. Certain businesses will be required to undergo annual independent cybersecurity audits beginning in 2027, phased in by company revenue, covering 18 components of a cybersecurity program and culminating in executive certification. Businesses must also conduct risk assessments before engaging in activities such as selling personal information, processing sensitive data, or using ADMT for significant decisions, with California uniquely requiring evaluation of “negative impacts” to consumers. Beginning April 1, 2027, businesses using ADMT for significant decisions must provide pre-use notices, access to information about how the ADMT works, and opt-out rights, though the regulations clarify that ADMT excludes technologies where a human retains authority to review and override the output. Additional provisions strengthen opt-out notification requirements and prohibit dark patterns in consent mechanisms, with several of these provisions already in effect as of January 1, 2026.
On April 16, 2026, the Division of Corporation Finance (Division) of the U.S. Securities and Exchange Commission issued an exemptive order (Order), effective immediately, that changes certain rules pertaining to tender offers of securities. The Order covers tender offers for both reporting and nonreporting companies.
The Division’s stated rationale for the Order is threefold: (1) to address market inefficiencies created by the 20-business-day minimum offer period; (2) to reflect technological advancements that enable faster dissemination of, and access to, offer materials; and (3) to reduce offerors’ and security holders’ exposure to unnecessary market fluctuations during the offer period.
Shorter Offer Period for Private Companies
Most notable in the Order, tender offers conducted by private companies, as well as by wholly owned subsidiaries of such issuers for the issuer’s own securities, will now be subject to a 10-business-day minimum offer period.
There are some conditions for this new relief to apply:
- Cash-only, fixed-price consideration. The consideration offered must consist solely of cash at a fixed price.
- Early notice of price or percentage changes. Any change to the percentage of securities sought (beyond the 2% de minimis threshold) or to the amount of cash offered must be communicated to holders no later than 9 a.m. Eastern time on the fifth business day before expiration.
- Notice of other material changes. Any other material change in the terms of the offer must be communicated no later than 9 a.m. Eastern time on the second business day before expiration.
Notably, the Order does not grant any relief to third-party led tender offers, which is expected to result in a clear timing advantage for issuer-led liquidity transactions for private companies.
Shorter Offer Period for Public Companies
For third-party tender offers subject to Regulation 14D, a shortened 10-business-day period is available but only when (i) the offer is made pursuant to the terms of a negotiated merger agreement or similar business combination agreement between the target company and the offeror and (ii) the offer is made for all outstanding securities of the subject class. In addition, the target company must file and disseminate a Schedule 14D-9 no later than 5:30 p.m. Eastern time on the first business day following commencement.
By contrast, for issuer self-tenders subject to Rule 13e-4, the abbreviated period is available when the offer is made for less than all outstanding securities of the subject class.
Conditions Applicable to All Public Company Tender Offers
Regardless of whether the tender offer is a third-party offer or an issuer self-tender, all of the following conditions must be satisfied:
- Cash-only, fixed-price consideration. The consideration offered must consist solely of cash at a fixed price.
- No going-private transactions. The offer must not be subject to Exchange Act Rule 13e-3.
- No cross-border exemptions. The offer must not be made in reliance on the cross-border exemptions under Exchange Act Rule 14d-1(d) or Rule 13e-4(i).
- No competing offer at launch. At the time the offer is publicly announced, the subject securities must not already be the subject of another pending or previously announced tender offer by a different offeror.
- Extension required if a competing offer emerges. If a competing tender offer is publicly announced after commencement, the initial offeror must extend its offer so that it remains open for at least 20 business days from the date it originally commenced.
- Press release with hyperlink at launch. The offer must be announced via a widely disseminated press release or wire service by 10 a.m. Eastern time on the commencement date, including basic terms (identity of offeror, class of securities, consideration, and expiration date) and an active hyperlink to a website where holders can access the tender offer materials.
- Early notice of price or percentage changes. Any increase or decrease in the percentage of securities sought (beyond a 2% de minimis threshold) or any change in the consideration offered must be publicly announced no later than 9 a.m. Eastern time on the fifth business day before expiration.
- Notice of other material changes. Any other material change in the terms of the offer must be publicly announced no later than 9 a.m. Eastern time on the second business day before expiration.
Key Takeaways
The Order offers meaningful practical improvements for liquidity transactions structured as tender offers.
Most significantly, and in light of the increased prevalence of liquidity transactions, including tender offers, in tech among privately held venture capital and private equity-backed companies, parties should now give serious consideration to the meaningful timing advantage that an all-cash issuer-led tender offer would present as compared to other structured liquidity transactions. In addition, for public companies, the Order now offers greater flexibility in aligning tender offer timelines with other typical deadlines that arise in such transactions, including proxy timelines, antitrust, equity compensation, and the Committee on Foreign Investment in the United States.
Of course, the Division expressly noted that all antifraud and antimanipulation provisions of the federal securities laws continue to apply — including Sections 10(b) and 14(e) of the Exchange Act and the rules promulgated thereunder — and that responsibility for compliance with all applicable federal securities laws rests with the offeror.
On May 21, 2026, the New York State Department of Financial Services (“DFS”) issued two coordinated Industry Letters: a letter on Heightened Cybersecurity Risks Associated with Frontier AI models (the “AI Advisory”) and accompanying Guidance on Measures Regulated Entities Should Consider in a Heightened Cybersecurity Threat Environment (the “Guidance,” and together, the “May 2026 Publications”). The AI Advisory builds on DFS’s October 2024 guidance on cybersecurity risks arising from artificial intelligence (AI), but is narrower in focus. Specifically, it addresses frontier models that may materially increase the speed and effectiveness of vulnerability discovery and exploitation.
The May 2026 Publications are not new rulemaking — both Industry Letters explicitly state so — but they are meaningful supervisory guidance: DFS identifies frontier AI Models as a technological development that may materially change the threat environment and instructs covered entities to evaluate whether their existing Part 500 programs remain adequate in light of that changed risk. The publications merit attention from DFS-regulated entities because they identify a specific class of emerging technology that DFS views as material to cybersecurity risk management under Part 500. That attention is warranted not only because the May 2026 Publications identify risks DFS views as material under Part 500, but also because DFS has cited prior Industry Letters in Part 500 consent orders, underscoring that such guidance can have practical supervisory and enforcement significance.
In a US$250 million acquisition, the buyer refused to pay one stockholder his merger proceeds unless he first signed a joinder agreement that included a sweeping release of any claims he might have against the companies. After trial, the Delaware court held that withholding payment on that condition breached the company’s charter. A stockholder cannot be forced to give up legal claims just to collect money he is already owed, unless he receives something extra in exchange for that release. The company eventually conceded the point.
The Delaware Supreme Court recently affirmed that, with respect to limited liability companies (LLCs), courts will not fill gaps with implied duties that parties chose not to include in the LLC’s operating agreement. In Khan et al. v. Warburg Pincus, LLC, the Court found that minority LLC members could not use the implied covenant of good faith and fair dealing to challenge the outcome where the LLC agreement expressly waived fiduciary duties, authorized self-interested conduct by the majority investor, and provided a specific amendment mechanism for differential consideration. The Court refused to import corporate-style fairness and disclosure obligations where parties had negotiated a detailed contractual governance scheme, reinforcing Delaware’s highly contractarian approach to LLCs.
On August 19, the U.S. Federal Trade Commission (FTC or Commission) proposed an “Enforcement Policy Statement Regarding Personalized Pricing.” The statement explains that the FTC will prioritize enforcing its consumer protection mandate to prevent companies from varying prices based on individual consumers’ personal data without certain disclosures. The public — businesses and consumers alike — will have an opportunity to provide feedback on the policy statement. Comments were due by September 25.
As used by the FTC, “personalized pricing” means the practice of setting the price offered to a particular consumer based on that consumer’s personal data or inferences drawn from it. Importantly, the FTC does not treat every individualized or variable price as personalized pricing. It distinguishes dynamic pricing based on market conditions, such as changes in supply and demand that affect everyone in the same market, including highly localized rideshare demand; regional price differences attributable to taxes, regulation, or local market conditions; and prices that inherently depend on a purchaser’s individual characteristics — its examples are insurance and credit, where individualized risk legitimately affects price.
In a Law360 article, Sidley lawyers David Buck, Paul Tyrrell, and Michael Mann examine the Financial Crimes Enforcement Network’s (FinCEN) final rule significantly narrowing beneficial ownership information (BOI) reporting requirements under the Corporate Transparency Act (CTA), the law that had required many small and midsize entities to tell the federal government which individuals ultimately own or control them. The authors explain what the rollback means for U.S. companies and their beneficial owners, foreign companies registered to do business in the United States, and financial institutions subject to customer due diligence requirements, and highlight state-level BOI requirements and future FinCEN rulemaking that companies should continue to monitor.
Federal prosecutors in Manhattan and the Commodity Futures Trading Commission charged a Google software engineer on May 27, 2026, with using confidential internal search data to make money on Polymarket, a platform where people trade contracts tied to whether a specified event will occur. It was the second such case in weeks, following one involving a service member accused of trading on classified information, and it pushed insider trading style theories well beyond stocks and bonds into event contracts.
The charges raise unsettled questions about whether confidential business information is protected in these markets the way it is in securities markets, and how far the CFTC’s enforcement authority reaches. For companies, the immediate concern is that standard insider trading and confidentiality policies were written with company stock in mind and may say nothing about employees trading on outside prediction platforms using nonpublic internal data. Regulators applying familiar fraud theories to a new market is the development to watch.
As prediction markets expand beyond elections and sports to cover corporate, regulatory, and geopolitical events, employees, directors, and other insiders who know something nonpublic may be able to profit from that knowledge without ever touching a share of stock. The government’s position, reflected in the first insider trading case brought over these markets, is that existing insider trading and antifraud principles already apply to event contracts. That leaves a gap for most companies given that standard insider trading policies, confidentiality agreements, and codes of conduct are typically drafted around trading in the company’s own securities and may not reach these platforms at all.
To avoid legal, reputational, and compliance exposure, organizations – whether public or private – should address prediction markets before an incident rather than after, including by: prohibiting misuse of confidential business information, naming prediction markets explicitly in the company’s relevant policies, extending confidentiality obligations to information that could move an event contract, training people on the risk, and adding monitoring and reporting controls.
Incentive stock options (ISOs) have long been a favored form of equity compensation for companies, particularly startups, to attract, incentivize, and retain employees. When properly structured, ISOs offer two key federal tax benefits: (i) ISOs are not taxed as income when granted by the company or exercised by the employee, and (ii) subject to applicable holding periods, any gain on stock acquired from the exercise of an ISO is taxed at a more favorable capital gains rate (however, the spread at exercise may be subject to the alternative minimum tax (AMT)).
But the regulatory framework that gives ISOs potentially advantageous tax treatment comes at the price of their flexibility once granted. What companies may view as a “minor” change to the terms of an ISO may be treated as a “modification” under the tax regulations, which can have significant, unanticipated consequences and, in some cases, cause the ISO to lose its preferential tax treatment altogether, and in the worst-case scenario, become subject to Section 409A and the 20% additional tax thereunder. In such instances, the option no longer qualifies as an ISO and is thereafter treated as a nonqualified stock option (NSO) for tax purposes, meaning that it is taxable upon exercise and any resulting stock is not eligible for favorable capital gains treatment.
Loss of ISO treatment may be frustrating to both companies and their employees, and therefore, it is important to understand the implications of an option amendment before implementation.
Summary of ISO Requirements
In order for an option to qualify as an ISO under Internal Revenue Code § 422, it must satisfy all statutory requirements, including the following, on the date of its original grant:
- Option must be granted to an employee of the company (or its parent or subsidiary)
- Option must be granted under the company’s written equity plan
- Exercise price must be at least equal to the fair market value of the underlying shares (and for employees who are >10% stockholders of the company, the exercise price must be at least 110% of fair market value)
- The term of the option is no longer than 10 years (or no longer than five years for >10% stockholders)
- No more than US$100,000 of shares (based on the fair market value as of the date of grant) may first become exercisable in any calendar year
To the extent an option fails to meet the statutory requirements, or is in excess of the US$100,000 annual limitation, it is treated as an NSO for tax purposes.
Modifications of ISOs
Under applicable tax rules, a “modification” of an outstanding option is generally treated like a newly granted option as of the modification date. “Modification” is broadly defined to include any change that provides additional benefit to the optionholder, regardless of whether the optionholder actually benefits from such changes.
When an option is “modified,” it must re-satisfy all ISO requirements based on and as of the modification date to continue to be treated as an ISO. To the extent that ISO requirements are not met as of the modification date, the option is thereafter an NSO for tax purposes. In most cases, ISO status that is lost due to a modification cannot be restored.
Common Modifications and Their Impact
Companies may contemplate any number of changes to their outstanding options. Most often, companies propose amendments to (i) grant early exercise rights, (ii) accelerate vesting, (iii) extend exercise periods, or (iv) change exercise price.
Grants of Early Exercise Rights
To make option awards more competitive or attractive for its employees, a company may consider granting early exercise rights, which allow employees to exercise outstanding but unvested options, subject to a right of repurchase. Early exercise allows employees to own shares earlier and accordingly start their capital gains holding periods earlier.
While early exercise rights that are added to an option after its original grant date would seem to be a modification because they appear to provide an additional benefit to the optionholder, the ISO regulations specifically provide that this is not a modification of an ISO and can be added without jeopardizing the ISO status.
Acceleration of Vesting
In connection with acquisitions, layoffs, changes in control, or other special scenarios, companies may consider adding single-trigger or double-trigger acceleration terms to outstanding options to allow employees to vest in unvested options upon the occurrence of such events.
As a general matter, accelerating vesting does not itself constitute a modification for ISO purposes. However, acceleration might cause more shares to “first become exercisable” in a single calendar year, potentially causing all or a portion of the option to exceed the US$100,000 ISO limit for that year. Any excess over the limit is treated as an NSO.
Extensions of Exercise Periods
Most employee options are originally granted with a three-month post-termination exercise period (with certain extended periods provided for death or disability and shorter periods for a termination for cause). When an employee departs, a company may consider extending the exercise periods of the employee’s options to allow them additional time to decide whether to exercise them for shares.
Two separate ISO issues arise with respect to extensions: (i) extending the post‑termination exercise window is generally treated as a modification, causing re‑testing of ISO status as of the extension date, and (ii) regardless of any extension, an exercise that occurs more than three months after employment ends (excluding disability or death) cannot receive ISO tax treatment. In other words, if the ISO is in-the-money when the exercise period is extended, it will become an NSO, and even if the option remains an ISO, if it remains outstanding and exercisable after the three-month post‑employment period, it becomes an NSO at the end of such three-month post-employment period.
Adding Exercise Method (such as Promissory Note)
Adding an additional method of exercising an option, such as allowing exercise with a full-recourse promissory note, is typically expected to be treated as a modification, even though this may have been permissible to include when the ISO was granted. If the ISO is in-the-money or otherwise cannot requalify as an ISO at the date of this modification, it would be expected to become an NSO.
Changes to Exercise Price
If the price of a company’s stock decreases over time, a company may consider repricing any underwater options to restore their retentive purpose. Options are “underwater” if the exercise price per share is greater than the current fair market value of the share, meaning that an employee would inherently lose value by exercising their option. To fix this, a company may want to amend underwater options to reduce their exercise price to the current fair market value.
A reduction in exercise price is among the clearest examples of a modification and results in a deemed new grant of the option. Because ISOs must have an exercise price at least equal to the fair market value on the grant date, a repricing to lower that value will generally cause the option to fail the ISO test; however, repriced ISOs generally should be able to re-satisfy all ISO requirements based on and as of the modification date and typically will continue to be treated as an ISO (although if there are changes that make requalification not possible, such as no longer being an employee, the ISO will lose its ISO status in the repricing). Note that repricing can effectively double count prior ISOs, as the repriced grant is treated as a new ISO, such that the award could exceed the US$100,000 limitation when including the prior ISOs as new awards.
Consider the AMT
As a final thought, if the ISO holder would otherwise be subject to the AMT, the loss of ISO status may be less detrimental than for someone not subject to AMT. Losing ISO status would subject the holder to ordinary income tax rates, which may not be dramatically different than the AMT rates (26% or 28%, based on 2026 rates). Additionally, the vast majority of ISOs are not exercised and held for the required ISO holding periods and become NSOs in any event. Accordingly, the loss of ISO status is less impactful than it would otherwise be, although the tax benefits of an ISO when utilized to get long-term capital gain are measurably better where possible.
The last few years have seen a wide proliferation of secondary liquidity programs among VC- and PE-backed technology companies. Late-stage private company VC and growth financings now typically feature a secondary component, and it is not unusual to see secondary-only transactions among revenue-positive technology companies. The wide adoption of these transactions has brought with it a changing landscape of liquidity timeline expectations, valuations, and terms. Additionally, these programs often require careful structuring and a variety of legal and business considerations that are novel even to many experienced executives in technology companies.
Tender Offers vs. Secondary Transactions
When a high-growth company begins thinking about providing liquidity to its shareholders while it is still private, the first question that arises is whether the proposed transaction will be a “Tender Offer” (a legal term that brings with it a number of additional regulatory requirements) or a one-off secondary (a less regulated bilateral agreement between two parties). The determination is often made by legal counsel with reference to the Wellman test, a fairly dated eight-factor legal test that stems from a case called Wellman v. Dickinson. That said, the Wellman test is fairly straightforward and most of the eight prongs are usually met in a “typical” secondary program, in which case the analysis often comes down to the first two prongs, which are determined by reference to the number of potential eligible sellers and what percentage of the overall outstanding company capitalization they represent. The standard is subjective and depends on facts and circumstances – for instance, if an offer is made to hundreds of shareholders representing 10%+ of the company’s outstanding capitalization, you are most likely looking at a Tender Offer.
Tender Offer Rules
Tender Offers implicate U.S. corporate, tax, and securities law, and can equally implicate foreign laws when the eligible sellers are abroad. Private company Tender Offers, however, do offer significantly more flexibility than public company Tender Offers (i.e., no schedules, no SEC review, and more structuring flexibility with respect to the offering terms):
Securities Law
Section 14(e) of the Securities Exchange Act of 1934 (the “Exchange Act”), including the antifraud and antimanipulation provisions contained therein, as well as the extensive rules and regulations promulgated thereunder, including Regulation 14E, must always be considered and consulted when conducting a Tender Offer. Most notably, Tender Offers typically require a disclosure document, a reasonable means to tender the securities, and a minimum open period during which eligible sellers can consider whether or not to participate in the Tender Offer.
It is important to note that, on April 16, 2026, the U.S. Securities and Exchange Commission (SEC) issued an exemptive order that changed some of the rules pertaining to Tender Offers, including the minimum offering period for offers conducted by the company itself rather than directly by a third-party purchaser. An article summarizing these changes is also available on Sidley Catalyst.
In each jurisdiction where an offer is made, including foreign jurisdictions and any relevant U.S. state, local securities laws should also be reviewed.
Corporate Law
Tender Offers conducted by a third-party purchaser implicate corporate law governing transfers of securities and, as is typical for VC-backed technology companies, potential transfer restrictions. Tender Offers may also inadvertently trigger “Deemed Liquidation Event” provisions in the company’s governing documents.
Tender Offers conducted by the company that issued the securities in the first place may implicate rules concerning repurchases or redemptions of securities, impairment of capital, and dividends.
Of course, shareholder protective provisions and other restrictive covenants in equity and debt agreements must be consulted.
Lastly, Tender Offers often implicate interested party and corporate opportunity considerations, as executives and board members are also often eligible to participate, and careful consideration must be given to cleanse any such issues via relevant corporate law provisions.
Tax Law
Tender Offers require extensive tax planning, both with respect to the impact on eligible sellers and on holders of stock options or other employee equity. Section 409A deferred-compensation rules, dividend rules, compensatory versus capital gains treatment, and other tax rules may all be implicated if not carefully structured. It is typically expected that eligible sellers will receive some level of disclosure with respect to potential tax implications of their investment decision.
Structuring Considerations
There are two primary decisions that any company contemplating a Tender Offer must consider at the outset:
- Eligibility Criteria. Who should be eligible to sell their securities in the Tender Offer? A number of factors are typically considered here, including:
- Will the Tender Offer proceeds have a positive or negative impact on employee retention?
- Are there early investors who require returns for their funds?
- Will there be a “consolidation” effect on the cap table? Will some shareholders be happy to sell and separate from the company sooner than others?
- Will there be an expectation of continued liquidity programs?
- Will there be a positive or negative impact on the company’s valuation?
- How will this impact public perception of the company and its shareholders?
- Identity of Purchasers. Will this be a direct third-party purchase by a single purchaser or a group of purchasers, or will it be conducted as a repurchase by the company of its own securities? The differences between the two can impact the following:
- Time period required for the Tender Offer to remain open.
- Primary responsibility for preparing the Tender Offer documents and for the accuracy of those documents.
- Difference in fees and costs associated with the Tender Offer.
- Whether the company has funds to conduct the Tender Offer or whether such funds must be raised from third-party sources.
Less pressing, but nonetheless important, considerations include which party will pay the fees and costs of the Tender Offer, whether the purchaser will require additional investor rights or side letters, whether any third-party portals or paying agents will be used, and how decisions regarding eligibility, extensions, and the like will be made.
Pricing the Tender Offer
The price offered for the company’s securities in a Tender Offer is often the result of negotiation. That said, there are a few considerations that repeatedly come up as the potential purchaser is considering what price to set for the Tender Offer:
- The price paid for the company’s securities in the most recent fundraising round. Law firms, secondary market platforms, banks, and others with significant experience in these transactions now have plenty of statistics to share with their clients regarding typical pricing for Tender Offers vis-à-vis the last round, how much time has passed, any discounts, and so on.
- The likely impact on future fundraising and liquidity opportunities. Tender Offers in companies nearing a liquidity transaction are very common, and pricing in the Tender Offer may indicate the likely valuation the company’s securities will receive in an IPO or M&A transaction. Thus, the pricing serves as a “signal” out to the marketplace as much as to the selling shareholders.
- The likely impact on the shareholder base. If the company’s shareholders have been signaled for years that they are holding very valuable stock, a discounted price in the Tender Offer may lead to disappointed employees and investors, even though the offer may look like a great deal to the purchaser.
- Impact on equity incentives. A highly priced Tender Offer may have an impact on the valuation of the company’s securities, including the exercise price of its stock options and the value of its RSAs and RSUs. Depending on which securities are used for equity incentives at the company, the price paid for securities by a third party may require a change of course after the transaction. Companies may also want to consider an exercise or grant freeze during the Tender Offer period, which may impact the company’s ability to hire or retain talent while the offer is open.
Timing and Disclosures
Finally, any company considering a Tender Offer must do so in the context of potential upcoming major transactions, changes in leadership, launches, or other major events that would be viewed as material to an investment decision and therefore would require disclosure to the eligible sellers. Typically, as well, some level of financial information is provided as part of the Tender Offer disclosures, and companies often think about the publicity and timing implications of this. As such, the likely timing of the offering and how it fits within the company’s and the investors’ broader timelines is an important consideration that should be proactively addressed prior to the launch of any Tender Offer.
Ordinary Delaware law tells a board selling control to get the best price reasonably available; however, by statute, directors of a public benefit corporation must balance stockholders’ financial interests against the interests of other people affected by the business and the company’s stated public mission. In Drakes Landing Associates, L.P. v. Tilden Park Capital Management, L.P., the court held that the Revlon stockholder value maximization standard of conduct does not apply to these directors, though courts may still review their decision-making under an enhanced scrutiny standard. The case was dismissed on a separate ground: the directors were protected by a statutory safe harbor, given that their decision was found to be informed, disinterested, and not one that no sensible person would approve. Here, an independent special committee with its own lawyers and a banker ran a market check before approving emergency financing that heavily diluted existing holders.
When it comes to non-competes, the state of California is not like much of the United States. The state maintains one of the most employee-friendly legal regimes in the country when it comes to post-employment restrictions, and those who fail to appreciate the breadth and force of California’s prohibitions risk not only unenforceability but also significant legal exposure.
California’s legal landscape demands that startups and investors approach restrictive covenants with clear eyes. Noncompetition agreements and customer nonsolicitation clauses are void. Employee nonsolicitation provisions are very likely void. And the increasingly popular strategy of repackaging a restrictive covenant as a trade secret protection, including by prohibiting the “use of proprietary information in order to” compete, solicit, or recruit, should be drafted and enforced narrowly to avoid an argument that they are operating as noncompetes in disguise.
The Foundation: Business and Professions Code Section 16600
California’s hostility toward restrictive covenants is rooted in Business and Professions Code Section 16600, which provides, in relevant part, that “every contract by which anyone is restrained from engaging in a lawful profession, trade, or business of any kind is to that extent void.” Courts have interpreted this provision broadly. Unlike jurisdictions that evaluate noncompetition agreements under a “reasonableness” standard, weighing the employer’s legitimate interests against the burden on the employee, California’s statute operates as a near-categorical prohibition. A contractual provision that prevents a former employee, consultant, or advisor from freely pursuing their livelihood is void on its face, regardless of how narrowly it is drafted, how short its duration, or how limited its geographic scope.1
The California Supreme Court held that the statute prohibits noncompetition agreements except in narrow statutory exceptions such as the sale of a business or the dissolution of a partnership. The court expressly rejected the argument that California should adopt a “narrow restraint” exception permitting noncompetition clauses that impose only limited restrictions on an employee’s future activities. The message was unambiguous: In California, noncompetition agreements with employees are void.
The Legislature also made it unlawful for an employer to enter into or attempt to enforce a noncompete agreement that is void under California law, even if the agreement was entered into outside of California.
Beyond Noncompetes: Employee Nonsolicitation Covenants
Founders and investors often assume that even if noncompetition agreements are off the table in California, employee nonsolicitation provisions, which are clauses that prevent a departing worker from recruiting former colleagues to join a competitor, remain permissible. This assumption is incorrect, or at least highly precarious.
California courts have increasingly treated employee nonsolicitation covenants as restraints on trade that fall within the ambit of Section 16600. The reasoning is straightforward: If a former employee cannot contact or recruit colleagues they previously worked with, their ability to engage in their profession is meaningfully restricted. They cannot freely build a team, they cannot leverage their professional network, and they are placed at a competitive disadvantage relative to others in their field who are not subject to such restrictions. While some practitioners still debate the outer boundaries of the holding (for instance, whether a narrowly drawn “no-raid” provision aimed at preventing the mass departure of an entire team might survive scrutiny), the prevailing trend in California jurisprudence strongly disfavors employee nonsolicitation covenants of any kind.
For startups, this has significant implications. It is common in the technology sector for key engineers, salespeople, or executives to depart and bring colleagues with them to a new venture. While this can be deeply disruptive to a young company, attempting to prevent it through contractual nonsolicitation provisions is unlikely to succeed in a California court and may expose the company to counterclaims.
Customer Nonsolicitation Covenants: An Equally Hostile Landscape
Customer nonsolicitation provisions - clauses that prohibit a former employee from soliciting or doing business with the company’s clients or customers - face a similarly difficult road in California. The California courts have confirmed they are just as much a restraint on mobility as an employee noncompete.
Some California courts have drawn a distinction between clauses that prevent a former employee from soliciting customers and clauses that merely prevent the misuse of trade secret information (such as confidential customer lists) to solicit those customers. This distinction brings us to one of the most important, and most misunderstood, issues in this area of law.
The Trade Secret “Workaround” That Isn’t
Precisely because California’s prohibition on restrictive covenants is so broad, creative drafters have long sought workarounds. One of the most common is to frame a restrictive covenant not as a restriction on competition or solicitation, but as a restriction on the use of the company’s proprietary or confidential information. Under this approach, an agreement might provide that the employee or consultant “shall not use Company proprietary information or trade secrets in order to compete with the Company,” or “shall not use Company confidential information to solicit Company employees or customers.”
The logic behind this formulation is superficially appealing. California law does, after all, protect trade secrets through the California Uniform Trade Secrets Act (CUTSA) and does permit employers to require employees to maintain the confidentiality of genuinely proprietary information. If the clause is framed as a trade secret protection rather than a restraint on competition, the argument goes, it should survive scrutiny under Section 16600.
The critical question is whether the clause, as drafted and as applied, operates as a genuine trade secret protection or as a de facto restrictive covenant dressed in the language of trade secret law.
Consider a clause that states: “Employee shall not use Company proprietary information in order to solicit Company’s customers.” On its face, this appears to be a narrow, information-based restriction. But in practice, a former employee who spent years managing a portfolio of customer relationships will find it nearly impossible to demonstrate, to the satisfaction of a litigious former employer, that their solicitation of a customer was based entirely on publicly available information and not, in any respect, on knowledge acquired during their employment. The clause effectively gives the former employer a veto over any customer solicitation by the departing employee, because the employer can always allege that the solicitation was informed by proprietary knowledge. The practical effect may be difficult to distinguish from a customer nonsolicitation covenant.
The same analysis applies to clauses framed as restrictions on using proprietary information to compete. A provision stating that the employee “shall not use Company trade secrets in order to engage in a competing business” may sound like a reasonable trade secret protection, but if the employee’s general knowledge of the company’s business strategies, product roadmap, or market positioning is broad enough, the clause effectively prevents the employee from working in the same industry. At that point, it is a noncompete in all but name. The important takeaway is that the inclusion of trade secret language does not immunize a clause that functions as a restrictive covenant.
This does not mean that employers cannot protect their trade secrets. They absolutely can, but they must do so through mechanisms that California law actually recognizes. A well-drafted confidentiality and nondisclosure agreement that identifies categories of protected information and prohibits its disclosure or use is generally enforceable. An employer can also bring a claim under CUTSA if a former employee actually misappropriates trade secrets to gain a competitive advantage. What an employer cannot do is use the specter of trade secret protection to achieve what amounts to a blanket prohibition on competition or solicitation.
Practical Implications for Consultants and Advisors
Much of the foregoing discussion has focused on employees, but the same principles apply with equal force to independent contractors, consultants, and advisors - relationships that are ubiquitous in the startup ecosystem. Technology companies frequently engage advisors under advisory agreements that include restrictive covenants, sometimes imported wholesale from templates designed for jurisdictions where such provisions are enforceable. In California, these provisions are no more valid when imposed on a consultant than when imposed on an employee.
Indeed, the case for enforceability may be even weaker with respect to independent contractors and advisors, who by definition maintain their own businesses and serve multiple clients. A nonsolicitation or noncompetition clause imposed on a consultant who advises several companies in the same sector would directly restrict the consultant’s ability to carry on their independent business and be squarely at odds with Section 16600.
All parties should review their advisory agreements, consulting agreements, and independent contractor agreements to ensure that they do not contain provisions that California law would render void. The inclusion of such provisions does not merely result in unenforceability; under the 2024 amendments, it can result in affirmative liability.
A Word About Choice of Law and Forum Selection
Some parties sometimes attempt to circumvent California’s restrictions by including choice-of-law provisions that designate a more permissive jurisdiction, for example, specifying that the agreement will be governed by the laws of Delaware or New York. This strategy is largely ineffective for individuals who work in California. California courts have consistently held that Section 16600 reflects a fundamental public policy of the state, and they will apply California law to restrictive covenants affecting California-based workers, regardless of the contractual choice of law. Furthermore, it is unlawful to enforce a void noncompete in California even if the agreement was signed outside of California.
For investors conducting due diligence on California-based portfolio companies, this is an area of particular concern. A company whose key employee agreements rely on restrictive covenants (whether styled as noncompetes, nonsolicitation clauses, or trade-secret-based activity restrictions) may have a materially weaker competitive moat than its cap table suggests. Diligence should specifically address the enforceability of employee and consultant agreements under California law and should flag any provisions that may expose the company to liability under the current statutory framework.
Many private companies are having to grapple with the realities of lower valuations. When a new Section 409A valuation values the company’s common stock at a lower price than any past Section 409A valuations relied on to grant prior stock options, the company may want to consider repricing the stock options held by its service providers. Where an existing stock option has an exercise price higher than the company’s current valuation, the result is an “underwater option.”
While repricing can restore some of the incentive and retention value of employee equity, it raises a host of valuation, perception, legal, tax, and accounting considerations that a company must manage.
Is a repricing necessary?
If the decreased valuation is a temporary situation that is expected to shift and change in a short period of time, or the long-term value is expected to be significantly greater than the current price, a repricing may not be necessary. This is particularly true if the value that is added to the option as a result of the repricing is not significant from a long-term perspective (i.e., the adjustment in price is relatively small). For example, if an employee held 1,000 company stock options that were currently priced at $2 per share, but that could be repriced to $1 per share, it may feel like making this change would be a significant repricing. However, if, a few years later, the company were to have a liquidity event where the shares were sold at $100 a share, this repricing only added an additional $1,000 to the total sale amount of $99,000, which is an increase of only 1 percent. Contrast that to a situation where the shares are ultimately sold at $3 a share. Repricing the options to $1 a share would still only add $1,000 to the total sale amount, but that would effectively double the holder’s total sale proceeds from $1,000 to $2,000.
While companies may not be able to predict the ultimate sale price, it is useful for a company to look at what a healthy potential exit will look like and how significant this repricing would be in that context, to ensure there is material value being added as a result of the repricing.
Negative Aspects of a Repricing
At first blush, most people would expect employees would be happy to have their options repriced as it gives them additional potential equity value; however, repricing options can introduce worry about the long-term value and prospects of the equity and, as a result, impact employee morale. Repricing can, and often does, have a positive impact on employees, but employees may also interpret it to mean the equity they hold is decreasing in value and that they are less likely to get the hoped-for. This can be particularly true where there are multiple repricings over a period. Repricing can also impact employees’ trust in management, especially if the message coming from management is about how well the company has been doing during that same period. If the future value of the shares is perceived to be weak, it creates jitters among the service providers and can negatively impact retention and hiring. The impact is exacerbated if the company is in an industry where most companies are doing well, as opposed to general market downturns impacting all similar companies. Finally, a company repricing can be a signal to investors that the company does not perceive as much long-term value in the shares and can actually lead to low-ball investment proposals, creating a self-fulfilling prophecy. Companies need to carefully weigh both the long-term and short-term impact of a repricing and its perceptions by service providers and investors.
Repricing Terms & Participation
If the company has decided that a repricing is necessary to properly incentivize its employees, the next consideration is what terms the company should offer in connection with the repricing. While a private company may be tempted to use the repricing as a chance to add vesting or other terms favorable for the company, anything other than a simple repricing (e.g., changing only the price) adds considerable cost and complexity for the repricing and could trigger the tender offer rules as discussed in more detail below.
Generally, only current service providers can participate in a repricing. This is because the repricing is effectively treated as a cancellation of the prior grant and a grant of a new award at the new price. All new awards need to be granted pursuant to a valid securities law exemption; thus, the repricing is generally limited to service providers that satisfy compliance under Rule 701 (discussed more below). If a significant number of former service providers are impacted by underwater stock options, the company should consult with counsel to determine the best path forward.
Tax Considerations
Any time a company wants to do a repricing, it needs to consider Section 409A compliance and Incentive Stock Option (“ISO”) tax issues.
Section 409A Tax Compliance
Section 409A governs deferred compensation, including stock options, and imposes severe tax penalties on options granted with an exercise price below fair market value. Section 409A penalties include an immediate income inclusion plus a 20% extra tax for the option holder. Any option repricing must therefore be done in compliance with Section 409A. In practice, this means the new exercise price cannot be less than the then-current fair market value of the underlying stock as of the repricing date. To ensure this, companies generally obtain an updated Section 409A valuation before repricing options. The board will use this valuation to set the repriced exercise price at or above fair market value, preserving the options’ exemption from 409A. Furthermore, a single repricing is usually not a risk under Section 409A, but successive repricings may be. While market volatility may tempt companies to repeatedly adjust option prices, serial repricings can be seen as the company not having a fixed price for options (e.g., the repeated repricings are seen as chasing a price to the bottom), which could be a Section 409A violation. Each modification should be carefully considered and tied to a material change in value (not minor fluctuations), and any subsequent repricings should be analyzed for their impact under Section 409A.
ISOs
Repricing an ISO is deemed a grant of a new ISO. This means that the regular limit on ISOs ($100,000 per year in which the option first becomes exercisable) must be recalculated, and some holders of repriced options may end up with fewer ISOs and more non-qualified stock options (“NSOs”) as a result of these recalculations. Also, since the repricing of ISOs is deemed a grant of new ISOs, the ISO holding periods (specifically, the prong requiring the ISO be held for two years from date of grant) will restart from the repricing date. Whether these changes are sufficiently material to require the consent of the option holder or a company tender offer should be analyzed by the company in consultation with its counsel under the terms of the plan (such as plan limitations on ISO grants and changes to existing grants) and applicable securities law.
Securities Law Considerations
A repricing raises securities law issues under Rule 701 and could trigger tender offer issues.
Rule 701
Rule 701 of the Securities Act of 1933 is the primary federal exemption that allows private companies to offer stock options and other equity compensation to employees without registering shares with the Securities and Exchange Commission. Repriced options count toward Rule 701 limits and disclosure thresholds. Importantly, as noted above, a repriced stock option is generally treated as issuance of a new security which must qualify for an exemption at the time of repricing. Therefore, the company must ensure that the repriced options, taken together with other equity compensation issued in the same 12-month period, do not exceed Rule 701’s size limits (the greater of $1 million, 15% of assets, or 15% of outstanding securities). Moreover, if the value of the repriced options, taken together with other equity compensation issued in the same 12-month period at the time of repricing, exceeds $10 million, the company must provide the required disclosures under Rule 701 (financial statements, risk factors) to all participants. Companies should keep in mind that, because Rule 701, by its terms, covers offers to current employees, directors, consultants, and advisors, it is generally not available as an exemption for repricing options to former service providers.
Tender Offer
An issuer tender offer under Rule 13e-4 and Regulation 14E of the Securities Exchange Act of 1934 (the “Exchange Act”) encompasses an offer by the company to security holders to exchange securities, which offer is open for a limited time and involves decisions by the holders. Importantly, a “simple” unilateral repricing that changes only the exercise price to the new Section 409A valuation while leaving the other terms the same is generally not thought to rise to the level of a tender offer. However, an option repricing where the option holder’s consent or action is needed may require compliance with tender offer rules, which are triggered because the option holder is making an investment decision over whether to accept the proposed terms of the repriced options. To comply with tender offer rules, the company then must observe a host of requirements under the Exchange Act. Also note, if the option is an ISO, keeping an exchange offer open more than 30 days might affect ISO status, so companies with ISOs will sometimes limit the offer window to 29 days to be safe.
Corporate Governance Considerations
A repricing will also raise a number of corporate governance issues, including approval requirements and fiduciary duties.
Board Approval
In almost all cases, repricing will require approval by the company’s board of directors (or a committee with delegated authority). The board should formally approve the repricing terms (who is eligible, new exercise price, timing, etc.) via a resolution. This is both a governance requirement and a key part of the board fulfilling its fiduciary duty (documenting that it considered the repricing and found it in the company’s interest to retain talent). The board should also be mindful of any conflicts of interest that may arise, particularly if grants to the directors are implicated.
Stockholder Approval
For private companies, stockholder approval of a repricing is typically not required unless the company is contractually obligated pursuant to agreements with investors. It is crucial to review the stock option plan documents, the company’s charter or organizational documents, and any investor agreements (such as an Investor Rights Agreement) before proceeding. Credit agreements or other contracts might also restrict modifications of equity incentives.
Fiduciary Duties and Legal Risk
A company’s decision to reprice options should also be evaluated through the lens of fiduciary duties and fairness to all stockholders. While repricing is aimed at benefiting employees (and, by extension, the company, through improved retention), it does effectively transfer potential economic value from existing stockholders to the option holders. Directors must justify the repricing as a reasonable, informed, and fair decision. To withstand scrutiny, the company’s board should document the business purpose, such as, for instance, maintaining team morale and productivity during a downturn. Additionally, to the extent any holders benefiting from repriced stock options are directors, officers, or controlling stockholders of the company, the company should be mindful of the safe harbor requirements under Section 144 of the Delaware General Corporation Law and obtain the appropriate approvals.
Federal health regulators settled four ransomware investigations on April 23, 2026, with a health provider network, an imaging provider, a third-party benefits administrator, and a self-funded health plan. Together the breaches exposed health and financial data for more than 427,000 people, and the companies agreed to pay a combined US$1,165,000 and to follow corrective plans monitored for two years. The common thread was not how the companies responded after the attacks but what they had failed to do beforehand: none had a complete, current assessment of where sensitive health data lived, how it moved through their systems, and what could go wrong.
For a startup handling health data, or acting as a vendor to one, the practical signal is that regulators are judging security preparation, not just incident response. Expectations include an up-to-date inventory of systems and data flows, encryption, multi-factor login, logging, vulnerability scanning, and training. Pending amendments to the HIPAA Security Rule would make many of these steps mandatory, with roughly 240 days to comply once finalized.
Tokenization has moved past the theoretical stage. Exchanges have been cleared to trade certain securities in tokenized form, blockchain-based transfer agents are registering with regulators, and the SEC is revisiting foundational rules for ownership records maintained on distributed ledgers. For companies, the question is no longer whether a tokenized security is a security. It is how the rules governing ownership records, transfer agents, custody, settlement, and secondary trading apply when the security lives on blockchain infrastructure.
For several years, the debate centered on whether a given token was a security. SEC staff has now answered the question that matters to most operating companies: a security formatted as, or represented by, a crypto asset remains a security, and the format in which ownership is recorded does not change the analysis. The applicable registration, disclosure, and intermediary requirements do not disappear merely because the security is represented on a blockchain. The practical work has therefore moved downstream — to how the instrument is issued, recorded, held, transferred, traded, and settled.
The SEC Begins to Build an Architecture for Tokenized Securities
The SEC’s January 2026 Staff Statement on Tokenized Securities organizes tokenization into four broad models. Issuer-sponsored structures may be integrated, where the token is the security itself and the issuer’s on-chain record is part of its securities infrastructure, or non-integrated, where the token is linked to a security that remains recorded off-chain. Third-party structures may be custodial, where the third party holds the underlying securities that back the token, or synthetic, where it does not hold the underlying and the token represents a separate claim or exposure. These are not merely technical variations. Depending on the model, a holder may own the security itself or a claim against an intermediary. That distinction can mean different rights in an insolvency, different disclosure considerations, and, in some structures, the possibility that the instrument is a security-based swap. The practical takeaway is straightforward: architecture matters. Companies should identify who maintains the authoritative ownership record, what the token legally represents, which party owes the holder what, and what happens when it moves.
Transfer Agency and the Ownership Record Take Center Stage
The SEC has proposed the first substantial overhaul of its transfer agent rules since the late 1970s and early 1980s, aimed squarely at this problem. SEC staff has already recognized that a distributed ledger may constitute all or part of a transfer agent’s official master securityholder file. The Commission’s September 2026 proposal takes the next step, proposing to modernize the transfer-agent rules themselves for an environment in which securities records may be maintained electronically and on blockchain infrastructure. It also asks whether the recordkeeping rules adequately support hybrid systems in which on-chain data, such as wallet addresses and share quantities, is linked to off-chain data, such as holder names and addresses, so that a blockchain transfer produces a corresponding change to the official record. Related proposals would replace certificate-era safeguarding requirements with a risk-management framework covering cybersecurity and business continuity, and would clarify requirements for removing restrictive legends and documenting client agreements. The comment period is open. Whatever the final rules, the direction of travel is clear: the ledger is being treated as potential securities infrastructure, not merely as a wrapper around it.
Tokenization Does Not Make Market-Structure and Custody Rules Disappear
Following staff relief for a clearing agency tokenization pilot, rule changes took effect permitting Nasdaq and NYSE markets to accommodate trading of certain securities in tokenized form, and blockchain-based transfer agents have registered with the Commission. These developments also raise an important issue for public companies: tokenization may increasingly become a feature of market infrastructure rather than an issuer-led initiative. As exchange, clearing, and transfer-agent infrastructure develops, issuers may confront tokenized forms of their securities even where tokenization was not part of the issuer’s original capital-markets strategy. Private companies exploring tokenized capitalization tables, fund interests, or secondary liquidity for employees and early investors now have registered service providers to evaluate — and correspondingly less justification for informal arrangements.
Moving from issuance into actual trading is where familiar questions return in unfamiliar form — and where the seams matter most.
- Classification: Are tokenized and conventional shares the same class for corporate and securities law purposes?
- Best execution: How do order-protection and best-execution requirements operate when the same security trades in two formats?
- Custody: For broker-dealer custody purposes, who has possession and control when the asset sits in a wallet?
- Transfer restrictions: How do negotiated transfer restrictions and legends function against a token that can move peer-to-peer in seconds and across borders?
- Settlement: Where does settlement become final, and who bears the risk before that point? The hardest problems arise at the seams between blockchain systems and traditional market plumbing, not within either one in isolation.
What Companies Should Be Thinking About Now
Companies considering tokenization should resolve five questions early:
- what legal interest the token represents;
- which record constitutes the authoritative ownership record;
- who performs transfer agent and custody functions;
- how on-chain transfers interact with off-chain records; and
- how the asset will actually trade and settle. These architectural decisions are not implementation details — they drive the regulatory consequences of the structure.
On April 15, 2026, the European Data Protection Board (EDPB) published its long-awaited draft Guidelines 1/2026 on the processing of personal data for scientific research purposes (the Guidelines), marking the most comprehensive regulatory statement to date on how the GDPR applies to scientific research activities.
For organizations in the life sciences sector, the Guidelines address long-standing areas of uncertainty — particularly around secondary use of data, broad consent, and transparency obligations — while signaling a clear shift toward stricter expectations on governance, purpose limitation, and accountability. The EDPB’s objective is clear: to promote a more consistent and workable framework across the EU, while maintaining robust safeguards. The public consultation closed on June 25, 2026, and the Guidelines remain in draft pending adoption of a final version.
Hong Kong’s securities regulator is taking a harder line on claims that documents are shielded by legal professional privilege. Speaking in late August 2026, the Securities and Futures Commission’s head of enforcement said the agency is prepared to push back against over-broad privilege claims, echoing a recent court ruling. In that case, a broker hired outside lawyers after concerns arose about the handling of confidential information around a block trade, and the resulting internal investigation report was given to the SFC under a limited waiver. When a hedge fund manager sought the report, interview notes, and underlying communications, the broker claimed privilege and lost. The court applied the dominant purpose test: a document is privileged only if it was created mainly to obtain legal advice or for litigation, and here the main purpose was satisfying regulatory reporting obligations. Involving a lawyer or labeling a document does not by itself create privilege, although genuine privilege survives a limited waiver.
Against a backdrop of executive orders targeting diversity, equity, and inclusion (DEI) programs, anti-DEI shareholder proposals, and the post-SFFA v. Harvard legal landscape, companies face growing pressure to reassess their DEI initiatives. To navigate this environment, companies should assess their risk tolerance relative to peers and consider a comprehensive audit of existing DEI policies with counsel. They should also tie their programs to demonstrable business rationale, understand the perspectives of key stakeholders through surveys and listening sessions, maintain a consistent tone at the top, and establish a response team for potential public scrutiny, while monitoring evolving regulatory guidance.
South Carolina’s new Age-Appropriate Design Code Act is shaping up to be one of the most demanding privacy laws in the country for companies whose products can be reached by people under 18. It pairs prescriptive “privacy by design” requirements, meaning child-safety and data-minimization choices have to be built into the product itself rather than bolted on later, with limits on targeted advertising to minors. It also requires parental tools that let a parent manage a minor’s account settings, restrict purchases, see time spent, and set time limits.
Two features stand out for small teams. First, covered services must obtain an annual review by an independent outside auditor and file that report with the South Carolina Attorney General, and those reports are posted publicly. Second, penalties are unusually aggressive and can reach individual officers and employees personally where violations are willful and wanton.
IP will be a core focus for a biotech company and its investors through its entire lifecycle. While the company’s IP strategy can and should evolve over time, there are certain steps that an early-stage company can take at the outset to establish a strong foundation. This article identifies several key principles that, in addition to an intelligently crafted IP portfolio, will help set an emerging company up for future success.
Document Ownership
Too many deals — licenses, acquisitions, or otherwise — stumble due to questions about ownership of a company’s core inventions. Fortunately, a few simple documents can avoid most issues. Founders and other employees should have straightforward agreements assigning (using “present tense” assignment language) relevant inventions to the company. Companies should also understand whether key personnel have parallel or prior obligations to academic institutions, and be able to clearly explain those obligations, and ensure that CROs, consultants, and other service providers also appropriately assign IP generated for the company.
Document these arrangements when relationships begin — not several years later when an investor or potential acquirer asks for the paperwork and it may be logistically difficult or expensive to reconstruct a chain of title for IP.
License for the Long-Term
When a company is in its very early stages, there can often be a lot of time pressure to secure any third-party IP rights, such as a foundational IP license from a university. It is also important, however, to keep in mind that licenses are long-term instruments and the same document may be scrutinized several years later in a due diligence process when the company’s situation is very different. While perfection can often be the enemy of good, foresight does not have to be the enemy of speed. Negotiating the material license or collaboration with an eye towards future-proofing in a few key areas can even increase the value of the agreement to the company.
Patent then Publish
Once out of stealth, scientific publications, conference presentations, and other disclosures can be integral to a young biotech company’s success. They can also have irreversible consequences for patent protection if not timed properly — i.e., a publication prior to patent filing can preclude the issuance of the patent.
Early training for employees and a simple process can go a long way in mitigating this risk. A one- or two-hour IP 101 training from counsel can be very effective, and can also roll out a straightforward process to ensure that both technical and other personnel know to check with patent counsel before submitting a manuscript for publication or disclosing proprietary information in a pitch without a confidentiality agreement in place.
The rule of thumb is simple: when potentially patentable technology is about to leave the building, determine whether to file a patent application first.
Joint Ownership Does Not Simplify
Negotiating a transformative IP agreement can sometimes take considerably longer than initially thought, and it can often be tempting to take the negotiation path of least resistance. When it comes to IP ownership, this path equates to “joint ownership” of inventions. On its face, joint ownership sounds like a great solution. It is fair, equitable, and does not require a complex analysis of each party’s contributions to the invention. It is jointly owned, no matter what. The problem lies in operationalizing the joint ownership.
The rules governing jointly owned IP vary by jurisdiction and can create complications around licensing, patent prosecution, enforcement, and commercialization. Joint ownership can also become particularly cumbersome in future transactions — e.g., an acquirer is a competitor of a joint owner. While it may take a little extra negotiation, there are many ways to allocate ownership of IP other than just inventorship that can suit both parties, including ownership based on relation to background IP, subject matter, or type of IP.
Data Is a Key Asset
A biotech’s most valuable assets increasingly extend beyond patents and traditional know-how. Preclinical results, clinical data, biomarker datasets, manufacturing data, and datasets used to develop or validate computational tools may all have substantial strategic value. Data rights and restrictions should be given the same level of focus as the development of an IP strategy. Particular attention should be paid to distinctions among raw data, processed data, derived data, and analytical outputs — and to privacy, consent, or contractual restrictions that may constrain future uses.
Dodiya v. Franklin tested the limits of the safe harbors added in 2025 to Section 144 of the Delaware General Corporation Law. Those amendments can preclude equitable relief and eliminate damages claims in certain conflicted transactions that may involve insiders or a controlling stockholder by having it approved either by disinterested directors acting in good faith and without gross negligence, or by an informed vote of disinterested stockholders. In Dodiya v. Franklin, a company’s CEO leaked confidential valuation and process information to his father’s investment firm, which bought stock cheaply and then took the company private. The board continued to give the CEO access to deal materials and allowed him to attend a board meeting about the deal even after he recused himself, and despite the board’s knowledge of the leak. Despite this, the proxy statement stated he had not participated in the sale process after his recusal. In August 2026, the Delaware Court of Chancery found that the board acted with “reckless indifference” and that it was reasonably conceivable that the merger proxy statement contained a material misstatement, making both safe harbors unavailable. The safe harbor protection is real, but its availability depends on the board’s process and the accuracy of its disclosures.
Generative artificial intelligence (GenAI) tools are becoming increasingly utilized by employees in the workplace to enhance productivity. However, employees are frequently leveraging these tools without formal approval or oversight. While the benefits of GenAI tools may be substantial, use of GenAI may pose significant risks to organizations, including legal liabilities, data breaches, and reputational damage. This article explores certain key concerns associated with employee use of GenAI tools and essential components of an AI use policy.
Understanding the Risks
Data Privacy and Security
One of the most significant risks with the use of GenAI is that information entered into prompts or uploaded to common GenAI platforms may reveal to the AI tool sensitive or confidential company information or information about clients or customers, including information the company may have contractually agreed to keep confidential. Similar risks exist with inputs of personally identifiable information, such as email addresses or other identifiers. Typically, on publicly-available versions of such tools, data that is entered is used to train the AI or may otherwise be stored or used by the AI tool developer.
To mitigate risks of exposing potentially sensitive company data or potentially breaching customer confidentiality agreements, companies may want to consider purchasing enterprise versions of GenAI tools that operate in a closed-loop system, meaning the developer is not permitted to use or store inputs for purposes other than to provide the GenAI tool. Companies may also want to have an approved list of AI tools, which might include enterprise versions of common GenAI tools. Also helpful in mitigating risks is employee training and raising awareness of these risks.
Another significant and emerging risk is that GenAI tools are increasingly being used as a tool for cybercriminals, including through the orchestration of complex injection attacks that exploit the fact that these tools do not think, but rather, simply follow instructions. For example, attackers can embed instructions in publicly available links that, when uploaded to the GenAI tool, tell the tool to maliciously attack the host system and override instructions. Alternatively, the embedded instructions in public links could produce PDFs or other outputs that themselves contain malicious code. Companies should consult with their security team about the risks unique to their business and implement recommended controls if applicable. In addition, companies may want to consider working with external cybersecurity training providers to ensure their materials include coverage of AI tool injection attacks in employee training modules.
Intellectual Property Concerns
Companies should also seriously consider the significant intellectual property (IP) risks posed by employees’ use of GenAI tools. These IP risks arise from two factors: (1) the material used as “input” to train the AI models; and (2) the material generated by the AI model as “output”. AI models are frequently trained on vast datasets which include copyrighted material used without the author’s permission. Furthermore, use of such copyrighted material may cause the GenAI tool to generate outputs that replicate or closely resemble the copyrighted material, further exposing the user to potential copyright infringement claims.
Another IP risk associated with employees’ use of GenAI tools is the lack of IP protection for works and innovations created using GenAI. In the United States, works and innovations created solely by AI without human contribution are not eligible for copyright or patent protection. Without such protections, a company’s competitive advantage may fall into the public domain, where anyone can use it for free.
Use of GenAI may also compromise trade secret protection of a company’s proprietary information. If an employee inputs confidential proprietary information into GenAI tools without proper contractual protections, such information may be used to train the underlying AI models. As noted above, GenAI tools may generate outputs that replicate or closely resemble the inputs, in this case, the proprietary information, potentially exposing the trade secret to other users and compromising the company’s trade secret protection of the information.
Hallucinations and Bias
AI systems, particularly generative models, can produce outputs that appear plausible but are factually incorrect or nonsensical, a phenomenon known as “hallucinations.” These inaccuracies can lead to misguided business decisions, flawed reports, and erosion of trust in AI tools. For instance, an AI-generated report might cite non-existent studies or fabricate data, potentially leading to compliance issues or reputational damage.
Shadow AI Usage
Employees may use unauthorized AI tools (sometimes referred to as “shadow AI”) without the knowledge or approval of IT departments. This practice can result in data security breaches, compliance violations, and loss of control over sensitive information. For example, inputting confidential company data into unvetted AI platforms could inadvertently expose proprietary information. Companies should implement strict policies around shadow AI use and consider limiting access to popular AI tools on workplace computers.
Regulatory Compliance Challenges
The rapidly evolving landscape of AI regulations, such as the European Union’s AI Act, presents compliance challenges for organizations. Failure to adhere to these regulations can result in legal penalties and hindered innovation. Organizations must stay informed about regulatory changes and implement robust governance frameworks to ensure compliance.
DO’S & DON’TS:
Legal Compliance & Policy Design
DO:
- Establish a clear, tailored AI usage policy in collaboration with legal, IT, and compliance teams.
- Define “AI” in plain language, and specify which tools are approved.
- Include a mission or purpose statement to ground the policy in transparency, fairness, and innovation.
- Update the policy regularly to reflect evolving laws (e.g., EU AI Act, state legislation like Colorado’s).
DON’T:
- Don’t use one-size-fits-all policy templates. Each policy should reflect specific business risks and use cases.
- Don’t treat the AI policy as a one-time exercise. Legal exposure grows without active maintenance.
Data Security & Confidentiality
DO:
- Prohibit inputting sensitive, proprietary, or customer data into public AI tools unless specifically authorized.
- Include clear confidentiality provisions related to AI use in employee and vendor contracts.
- Conduct vendor due diligence to confirm AI platforms’ compliance with privacy laws and data handling standards.
- Consider using enterprise versions of AI tools to keep data inputs confidential.
DON’T:
- Don’t assume that AI tools won’t retain user input; review each tool’s terms of service and retention practices.
- Don’t allow shadow IT (e.g., unauthorized browser plugins, personal-use tools) without approval or audit trails.
Intellectual Property & Ownership
DO:
- Review AI vendor agreements to ensure the vendor has proper rights to use training data and provides adequate protections if infringement claims arise.
- Implement human review processes for AI-generated materials to identify potentially infringing content.
- Document human contributions in connection with the development of AI-assisted works and innovations.
DON’T:
- Don’t allow employees to generate customer-facing or public materials without review for potentially infringing content.
- Don’t use AI models trained on unlicensed data without understanding the risk of potential IP infringement claims.
- Don’t allow employees to input confidential proprietary information into AI tools without proper confidentiality and use restrictions.
Training, Governance, & Oversight
DO:
- Require regular employee training on the capabilities, limits, and risks of AI tools.
- Designate responsible roles (e.g., AI Compliance Lead, Tool Vetting Committee) to oversee implementation and approvals.
- Monitor AI tool usage, audit outputs periodically, and solicit user feedback to improve policies.
DON’T:
- Don’t deploy AI tools enterprise-wide without pilot testing, user education, and risk assessment.
- Don’t assume all departments or roles should have equal access to AI tools — access should be role-specific.
Ethical Use & Bias Prevention
DO:
- Embed fairness, transparency, and accountability principles into the company’s AI governance framework.
- Monitor AI systems for evidence of bias, particularly in HR, marketing, or customer interaction tools.
- Require disclosures when AI is used to create or assist in work product — internally or externally.
DON’T:
- Don’t use generative AI content without fact-checking — misleading outputs could carry reputational or legal costs.
- Don’t let AI output go unlabeled in sensitive contexts (e.g., client deliverables, compliance filings).
Qualified Small Business Stock (QSBS) has become an increasingly central focus for founders and investors, as awareness of its potential tax benefits continues to grow. If stock qualifies as QSBS, a holder may be eligible to exclude up to 100% of federal capital gains on disposition subject to a cap equal to the greater of (a) $10 million, or $15 million for post-2025 issuances, and (b) 10 times the taxpayer’s initial basis in the shares. Further, with careful structuring and planning, founders and investors can maximize the QSBS exclusion.
In practice, founders, investors, and senior executives often seek confirmation, typically in the form of a company-level analysis or determination letter, that the corporation’s stock satisfies the applicable requirements at issuance. As QSBS planning has become more sophisticated, both the importance of this analysis and the consequences of getting it wrong have increased materially.
Background
Before 2010, the Internal Revenue Code Section 1202 generally provided individual taxpayers with what was, in most cases, a very small tax rate reduction for gains recognized from sales of QSBS that had been held for more than five years.
That all changed significantly following the 2008 financial crisis. In the wake of the crisis, Congress passed the Small Business Jobs Act of 2010 to encourage individual taxpayers to make additional equity investments in startup corporations during the remainder of calendar year 2010. The Small Business Jobs Act of 2010 included an amendment to Section 1202 that, for the first time, provided for a complete U.S. federal income tax exemption (with no application of the alternative minimum tax) for specific gains recognized by non-corporate investors on the sale of QSBS held for more than five years but only if the stock was purchased at original issue in the limited window after September 27, 2010 and before January 1, 2011.
Although initially intended as a tax incentive for stock issued during a limited period, the 0% rate for gains on QSBS became so popular that Congress began expanding it. Congress repeatedly extended the applicable window for issuance of the 0%-eligible QSBS in successive one-to-two-year tranches. In 2015, the Protecting Americans from Tax Hikes Act of 2015 made the 0% rate for specific gains from sales of QSBS a permanent tax benefit. The tax benefits of QSBS have significantly increased in both value and accessibility. In 2025, the One Big Beautiful Bill Act (“OBBBA”), which applies to issuances after July 4, 2025, raised the “cap” on tax-free gains and introduced more flexible holding periods for new investments. The following table highlights key differences between the pre-OBBBA rules and the new rules:
Several requirements must be satisfied before those benefits can be realized and, even if those requirements are met, there are important limitations on the amount of gain that can qualify for the 0% rate. These requirements and limitations are further discussed below.
General Requirements
The general requirements for qualifying for the 0% federal tax rate on gains from the sale of QSBS include the following:
- Original Issue. The taxpayer must still be a non-corporate entity (individual, trust, or estate) and acquire the stock directly from a U.S. domestic C corporation.
- Tiered Holding Periods. For stock issued after July 4, 2025, a taxpayer can now receive a partial exclusion earlier: 50% after three years, 75% after four years, and the full 100% after five years. Pre-OBBBA stock still requires a strict five-year hold to receive any benefit.
- Gross Assets Test. For stock issued after July 4, 2025, the corporation’s aggregate gross assets cannot exceed $75 million (up from $50 million) at the time of issuance. Importantly, the amount of a corporation’s assets at any given time is generally measured by the corporation’s adjusted tax basis in those assets, except when any property is “contributed” to the corporation. In that case, for this purpose the property must be taken into account based on its fair market value at the time of the contribution.
- Active Business Test. During substantially all of the taxpayer’s holding period of the stock, at least 80% of the issuing corporation’s assets must be used by the corporation in the active conduct of one or more qualified trades or businesses. This includes assets used in furtherance of a prospective active business, i.e., startup activities, research and experimentation, and in-house research. It also includes working capital, investments expected to finance research and experimentation or increased working capital within two years, and computer software rights that produce active business royalties. However, after the corporation has existed for two years, no more than half of its assets can be working capital or investments held for future research or working capital. Although many types of trade or business should qualify for this purpose, the following are specifically excluded: any trade or business involving the performance of services in the fields of health, law, engineering, architecture, accounting, actuarial science, performing arts, consulting, athletics, financial services, and brokerage services. Also specifically excluded is any trade or business for which the principal asset is the reputation or skill of any of its employees.
- No Significant Redemptions. The issuer of the stock must not have engaged in specific levels of buybacks (redemptions) of its own stock during specified periods before or after the date of issuance of the stock to the taxpayer.
Exclusion, Limitations, and the Rise of Structured Planning
A non-corporate taxpayer who recognizes gain from the sale of stock meeting the above requirements can thus generally qualify for a 0% federal income tax rate. However, the amount of gain eligible for this 0% rate is subject to a cap. Section 1202(b)(1) states that the aggregate amount of gain for any taxpayer regarding an investment in any single issuer that may qualify for these benefits is generally limited to the greater of (a) $15 million (Post-OBBBA), or (b) 10 times the taxpayer’s adjusted tax basis in the stock. For a taxpayer who invests cash in the QSBS, the basis would generally be equal to the cash purchase price. However, there is a special rule for when a taxpayer instead purchases the QSBS for in‑kind property (that is, other than cash). In those cases, the taxpayer’s basis in the QSBS, solely for purposes of these Section 1202 rules, is deemed to be an amount not less than the fair market value of the property transferred for that QSBS as of the date of such transfer (often referred to as the basis-is-not-less-than-value rule). The general purpose of the basis-is-not-less-than-value rule is to ensure that inherent built-in gain for any property contributed to a corporation in exchange for QSBS does not qualify for the Section 1202 benefits. Only the gains from the sale of QSBS that are attributable to appreciation in value of the QSBS occurring after the date of issuance are potentially eligible for the Section 1202 benefits.
These new rules now theoretically allow for exclusions of up to $750 million for certain large-scale investments and certain other circumstances. As a result, taxpayers increasingly employ planning strategies, such as “stacking” QSBS across multiple taxpayers (e.g., trusts), and “packing” assets into QSBS-eligible entities. These strategies can be effective but require careful implementation and are subject to scrutiny. In May 2026, the Treasury Department signaled that it will be issuing guidance addressing what it sees as abuse of the QSBS “stacking” strategy.
The IRS has shown growing interest in QSBS claims, particularly in large exit transactions. Areas of focus include active business qualification, asset valuation (especially for contributed property), and related-party and restructuring transactions. QSBS remains one of the most compelling tax incentives available to founders and investors, but its benefits are not automatic. As the regime has matured, so have the expectations around compliance, documentation, and planning. For those who get it right, the rewards can be substantial. For those who do not, the cost of missed qualification can be equally significant.
State Conformity
While federal benefits are permanent, state treatment varies wildly. As of 2026, many states, including New Jersey and New York, now align with federal Section 1202 rules, while Alabama, California, Mississippi, and Pennsylvania continue to tax QSBS gains at full state rates. Residents in certain states, including Texas, can achieve a true 0% effective tax rate on QSBS gains by combining the federal exclusion with a lack of state income tax.
Rollover of Gain
A taxpayer other than a corporation (i.e., individuals, partnerships, S corporations, estates, and trusts) may elect to roll over capital gain from the sale of QSBS held for more than six months if QSBS is purchased by the taxpayer during the 60-day period beginning on the date of sale. Accordingly, gain is recognized only to the extent that the amount realized on the sale exceeds the cost of the replacement QSBS purchased during the 60-day period, as reduced by the portion of such cost, if any, previously taken into account. To the extent that capital gain is not recognized, that amount will be applied to reduce the basis of the replacement QSBS. The basis adjustment is applied to the replacement stock in the order in which the replacement stock is acquired.
Treatment for Pass-Through Entities
Gain on qualified stock held by a partnership, S corporation, regulated investment company, or common trust fund is excludable if the entity held it for the required holding period and if the partner, stockholder, or participant to whom the gain passes through held an interest in the entity when the entity acquired the stock and at all times thereafter. However, the partner, stockholder, or participant cannot exclude the gain to the extent that his or her share in the entity’s gain is greater than what it was when the entity acquired the qualified stock.
The Bottom Line
QSBS has evolved from a niche tax benefit into a central component of early-stage investment planning, particularly in light of recent expansions under the OBBBA regime. The increased exclusion caps, more flexible holding periods, and expanded asset thresholds have made QSBS more valuable, and more widely accessible, than ever before. At the same time, these enhancements have accelerated the use of structured planning strategies and heightened IRS scrutiny, raising the stakes for both companies and investors. In this environment, QSBS should be viewed not as a passive benefit but as a strategic framework that requires thoughtful implementation from formation through exit. With proper planning, documentation, and coordination, taxpayers can unlock substantial tax efficiencies; without such planning, the opportunity may be irretrievably lost.
With sweeping cuts to federal research funding driving academic scientists in the life sciences toward entrepreneurship, there are practical steps for navigating this transition: adopting an entrepreneurial mindset that embraces risk and redefines success; leveraging university incubators, tech transfer offices, and alumni networks; broadening professional networks through industry events and mentorship; validating ideas through market research and minimum viable products; understanding regulatory pathways and engaging FDA-specialized counsel early; learning intellectual property fundamentals and working with IP attorneys to build a competitive strategy; developing a comprehensive business plan with milestones and financial projections; securing a diverse mix of funding from grants, angel investors, and venture capital; assembling a multidisciplinary team with complementary expertise; and launching pilot projects to demonstrate feasibility and build credibility with investors and partners.
In June 2025, the U.S. Supreme Court upheld a Texas law requiring websites where more than one-third of content is sexually explicit to verify users’ ages before granting access. The critical legal question was which First Amendment standard to apply. The Court chose the more lenient intermediate scrutiny rather than the strict scrutiny used to strike down similar federal laws in the early 2000s, reasoning that the law targets distribution of obscene content to minors and only incidentally burdens adults’ access to protected speech. The three-justice dissent argued strict scrutiny should apply and warned of a chilling effect on lawful speech. The ruling’s reach extends beyond traditional adult content sites to any platform (including social media) if one-third or more of the platform’s content could be deemed harmful to minors. With nearly half of U.S. states having already enacted similar laws, the decision is expected to accelerate that legislative trend. Privacy advocates have separately warned that mandatory age verification forces users to submit sensitive personal identification, raising data breach risks and potentially threatening the First Amendment right to browse the internet anonymously.
Texas overhauled its business organizations code last year through Senate Bill 29, part of a broader effort to make the state a more attractive home for companies looking beyond Delaware. One of the changes lets certain corporations, including publicly traded ones and other opt-in companies with more than 500 shareholders, adopt a bylaw requiring a shareholder to hold at least 3% of the company’s stock before bringing a lawsuit on the company’s behalf against its own directors or officers.
A federal court has now applied that provision, dismissing a derivative case against Southwest Airlines’ board because the plaintiff held far too little stock to clear the company’s 3% bylaw. The court also rejected the argument that a pre-suit demand letter sent before the new rules took effect counted as starting the proceeding. For companies weighing where to incorporate, the case is an early signal that Texas courts are giving the state’s new corporate litigation protections real effect.
Texas Governor Abbott signed House Bill 40, significantly expanding and refining the Texas Business Court just two years after its creation. Key changes include lowering the amount-in-controversy threshold from US$10 million to US$5 million across all case types, expanding substantive jurisdiction to cover intellectual property, trade secrets, and arbitration enforcement cases, clarifying that only business, commercial, or investment contracts may elect business court jurisdiction by agreement, authorizing transfer of pre-September 2024 cases by agreed motion, and tasking the Texas Supreme Court with establishing a jurisdictional framework and rulemaking procedures. The legislature also eliminated the sunset provision for unfunded court divisions, signaling the business court is a permanent fixture in the Texas legal system.
Texas Governor Greg Abbott signed Senate Bill 29, a sweeping overhaul of the Texas Business Organizations Code aimed at making Texas the “corporate law capital of America.” Key changes include codifying the business judgment rule for publicly traded corporations, creating a statutory framework for controlling shareholder transactions with special committee pre-approval procedures, allowing entities to waive jury trials in governing documents, narrowing books and records demands to exclude emails and text messages, imposing up to 3% ownership thresholds for derivative suits, eliminating mootness fees for disclosure-only supplements, and permitting alternative entities to fully eliminate fiduciary duties in their governing agreements.
Following an industry challenge to Texas Senate Bill 140’s new text marketing registration requirements, the Texas Attorney General submitted a detailed interpretation of the law agreeing that the registration requirements were not intended to apply to businesses that obtain prior consumer consent before sending marketing text messages. As part of a subsequent settlement, the Texas Secretary of State posted guidance on its website confirming that consent-based text senders are not required to complete the telemarketing registration process and agreed to formally request a published AG opinion reinforcing this interpretation. While this clarification significantly reduces the registration risk for businesses with proper consent practices, some litigation risk remains. Plaintiffs’ attorneys may still attempt to assert the law’s private right of action and other requirements of the law will continue to apply, such as quiet hours restrictions.
Texas amended its telephone solicitation and telemarketing law (known as the “mini-TCPA”) through Senate Bill 140, effective September 1, 2025, to require businesses sending marketing text messages to Texans to annually register with the Secretary of State, pay a registration fee, post a $10,000 security deposit, and make detailed disclosures about their business and planned solicitations. The law expands the definition of “telephone solicitation” to include text messages and creates de facto violations of the Texas Deceptive Trade Practices Act (which carries significant penalties including treble damages and a private right of action) for violations of existing text messaging consent and no-call list requirements. Several exemptions may limit applicability for established businesses, including carveouts for publicly traded companies, supervised financial institutions, nonprofits, and entities that have operated under the same name for at least two years and are messaging current or former customers, though the scope of the customer exemption is somewhat ambiguous.
Although AI-related patent filings have surged dramatically over the past two decades, patent litigation involving AI technologies has not yet kept pace, a trend the article suggests may mirror the delayed wave of smartphone patent litigation that followed the technology’s commercial growth. In this piece for Bloomberg Law, Sidley partner Alexis Cohen argues that AI companies should begin preparing now for increased future litigation by evaluating and strengthening their intellectual property protections, including patents and trade secrets, while also improving documentation, ownership records, employee agreements, and internal processes.
Reproduced with permission. Published May 21, 2026. Copyright 2026 Bloomberg Industry Group 800-372-1033. For further use, please visit: Bloomberg Industry Group copyright and usage guidelines.
Successful founders often find themselves stock rich and cash poor, with most of their net worth held in illiquid shares. The usual path to early liquidity is a secondary sale, in which a founder sells a portion of existing shares to investors in connection with a financing. FF preferred stock (also called founders preferred stock or Series FF) is a class of stock adopted at formation to make that future secondary sale cleaner and more streamlined. Despite the name, it generally functions as common stock: it carries no dividend or liquidation preference, and it is distinct from the super-voting share classes sometimes used to concentrate founder control.
How It Works
FF preferred stock has a single distinguishing feature: when sold to investors in connection with a future preferred stock financing, it converts into the series of preferred stock being sold in that round. The investor receives preferred stock rather than common stock, and the founder typically receives the preferred price for the shares. The precise mechanics vary by form. Some versions convert automatically upon the sale, some convert at the holder’s option if the buyer pays the same per share price as the new round, and some require board approval; typical forms also permit conversion into common stock at any time and convert automatically into common stock in a qualified IPO.
Three practical rules follow from the tax analysis. FF preferred stock is generally adopted at formation, when founder shares are first issued; adding the class later can carry tax consequences. It is often, but not always, issued fully vested, because shares subject to forfeiture or repurchase may raise additional tax issues; as a result, any vesting sits on the founder’s common shares. And it typically covers only a modest portion of a founder’s holdings, most often 10 to 25 percent, with the balance in common stock.
Why It Exists
The structure responds to two problems with selling common stock at a preferred stock price. The first is tax. A founder who sells common stock for more than its fair market value (which ordinarily sits well below the preferred price) risks having the excess treated as compensatory ordinary income rather than capital gain, and the risk increases if the company facilitates the sale by converting the founder’s common stock into preferred stock at closing. Since FF preferred stock converts by its terms when sold, no corporate action is required at the time of sale, which is generally viewed as more characteristically the type of transaction that should result in capital gain treatment. However, that treatment is not assured and depends on a variety of factors specific to the underlying transaction; the nature of the security sold is merely one such factor. The second is valuation. A founder sale of common stock at or near the preferred price can put upward pressure on the fair market value of the common stock and, with it, the strike price of future option grants. Alternatively, a sale of FF preferred stock that converts into preferred stock mitigates the repricing effect on the common stock. Note that market practice has evolved on this point: secondary sales of common stock at no or a small discount to the latest preferred round have become customary, and selling parties have found ways to work through the issues that FF preferred stock addresses in its absence. Nonetheless, founders often view the implementation of FF preferred stock as a “just in case” move to improve their chances of a successful secondary transaction in the future.
What to Weigh
FF preferred stock is not the norm. It adds drafting complexity and cost to the certificate of incorporation for a benefit that materializes only if investors are someday willing to buy founder shares, which as a practical matter requires a strong company, an oversubscribed round, and a supportive board. Some investors also read the class as a signal that the founders expect early liquidity, and, when the shares are issued fully vested, the company gives up repurchase rights over that portion of a departing founder’s equity. However, when a secondary sale does happen, the structure may have real advantages: the founder can sell at the preferred price rather than at a discount, the company avoids facilitating a sale of common stock above its appraised value, and an oversubscribed round can be accommodated with less dilution because investors buy existing shares. Additionally, the potential tax consequences of such conversion should be addressed on a case-by-case basis.
In almost all cases, one typical feature of FF preferred stock is that it can convert to common stock at the election of its holder at any time, so founders can always elect to eliminate FF preferred stock at a later time if they find its utility no longer of value. Thus, including FF preferred stock at incorporation gives founders flexibility down the road.
Texas has rapidly emerged as one of the nation’s most aggressive data privacy regulators, surpassing California and New York in the breadth and enforcement intensity of its privacy regime. Over the past two years, the state has enacted a comprehensive suite of laws covering consumer and children’s data privacy, artificial intelligence, and data brokers, and its attorney general has secured multi-billion-dollar settlements against major technology companies for alleged violations. While the federal government and many other states have taken a lighter touch on privacy and AI regulation, Texas is leading the charge with active enforcement that companies operating in the state or collecting data from Texas residents cannot afford to ignore.
On July 23, 2025, the Trump administration released its AI Action Plan, aimed at ensuring U.S. global dominance in artificial intelligence, outlining 90 federal policy positions across three pillars: Accelerating Innovation, Building American AI Infrastructure, and Leading in International Diplomacy and Security. The plan calls for streamlining regulatory pathways, expanding public-private partnerships, increasing federal AI research investment, and promoting open-source AI models as potential global standards, while simultaneously encouraging export of the full “American AI Technology Stack” to allied nations as a geopolitical strategy. Three accompanying executive orders promote export of American AI technology, streamline federal data center permitting, and mandate adoption of ideologically neutral “Unbiased AI Principles” in federal procurement. The Action Plan emphasizes deregulation at the federal level and conditions federal discretionary funding on states’ AI regulatory environments, reflecting growing tension between the administration’s national AI framework and state-level regulatory efforts.
England’s High Court has issued the UK’s first ruling in a copyright fight against an AI developer with an outcome that favors the AI industry. In Getty Images v. Stability AI, Getty (which licenses photos and video) alleged that Stability scraped millions of its images to train the Stable Diffusion image generator. During trial Getty dropped its main copyright claim because it could not show the training actually happened in the UK. Copyright is territorial, so no act in the UK means no UK infringement.
That left a narrower question: whether importing the already-trained model into the UK made it an “infringing copy” under the Copyright, Designs and Patents Act 1988. The court said no. A model’s weights are just numbers derived from statistics; they do not store or contain the underlying images, so supplying the model is not secondary infringement. Getty won only on a historic and limited trademark point about its marks appearing in outputs. The decision settles little about whether UK-based training would infringe, and Getty may appeal.
A stockholder of a Delaware e-commerce company sent a formal demand to inspect company books and records while the company was being acquired. The company objected, claiming the demand was too broad and lacked a proper purpose, but offered to negotiate a narrower production. The stockholder did not respond. The merger closed a week later, cancelling the stockholder’s shares, and the stockholder filed suit to enforce her demand 12 days after that. The Delaware court dismissed the case: under the state’s books-and-records statute, often called Section 220, you must actually be a stockholder on the day you file the lawsuit, not merely on the day you send the demand. Once the merger wiped out her shares, she no longer qualified.
The court also refused to excuse the delay on fairness grounds, noting the company had never agreed to produce anything nor promised a schedule, so nothing it did invited her to wait. The court left open, without deciding, whether a fairness exception could ever apply, and cautioned companies that stringing a stockholder along before closing could weaken that defense.
The UK’s Medicines and Healthcare products Regulatory Agency moved on several fronts in the first half of 2026, with the intention of developing a more innovation-friendly and AI-aware regime. The developments include a landmark program deepening regulatory cooperation between the UK and the United States, a regulatory “sandbox” for AI used as a medical device, meaning a supervised space where companies can test products with the regulator before full authorization, an evidence-gathering exercise on how AI in healthcare should be regulated, a consultation on a draft Rare Disease Therapies Regulatory Framework, and the largest package of UK clinical trial reforms in more than twenty years. For a founder building AI-enabled diagnostics, software, or therapeutics, this changes both the route to market and its timing: earlier regulator engagement is becoming possible, trial rules are being streamlined, and closer UK-US alignment may reduce duplicated work across the two markets.
Attorney-client privilege is a cornerstone of effective legal risk management, but its application is nuanced — especially for in-house counsel. The privilege protects confidential communications between an attorney and a client made for the purpose of obtaining or providing legal advice. However, courts scrutinize claims of privilege, particularly when in-house counsel are involved or when communications comprise of both legal and business advice. The law governing privilege can vary significantly by jurisdiction; thus, it is important to seek the advice of counsel prior to any communications.
Key Considerations for In-House Counsel:
To maximize protection and avoid inadvertent waiver, legal teams and senior executives should keep the following in mind:
In-house counsel face extra scrutiny
Courts recognize that in-house counsel often wear multiple hats. Privilege will apply only where the primary purpose of the communication was to obtain or provide legal — not business — advice.
Privilege applies only to legal — not business — advice
Privilege attaches only to communications where the predominant purpose is legal advice, such as internal investigations to assess whether employees breached a contractual obligation, reviewing marketing materials for compliance with applicable law, or drafting and analyzing contractual language. Clearly distinguish legal analysis from business discussions, particularly in writing.
Confidentiality underpins privilege
Limit distribution of privileged communications to those who “need to know” and avoid including third parties unless necessary and protected by a recognized exception. This is especially important to keep in mind when discussing privileged information while working remotely. There are no exceptions for spouses, family, roommates, or neighbors.
Common-Interest Exception
For example, in California, generally the common-interest exception extends the privilege to communications between parties and their counsel relating to potential civil litigation provided that:
- The parties have some common litigation interest (a purely personal or business-oriented interest is insufficient); and
- The communications are made to further that shared legal interest.
This exception may also apply where parties maintain separate counsel but coordinate through a joint defense or litigation strategy.
Where it applies, the common-interest exception typically only protects communications involving counsel.
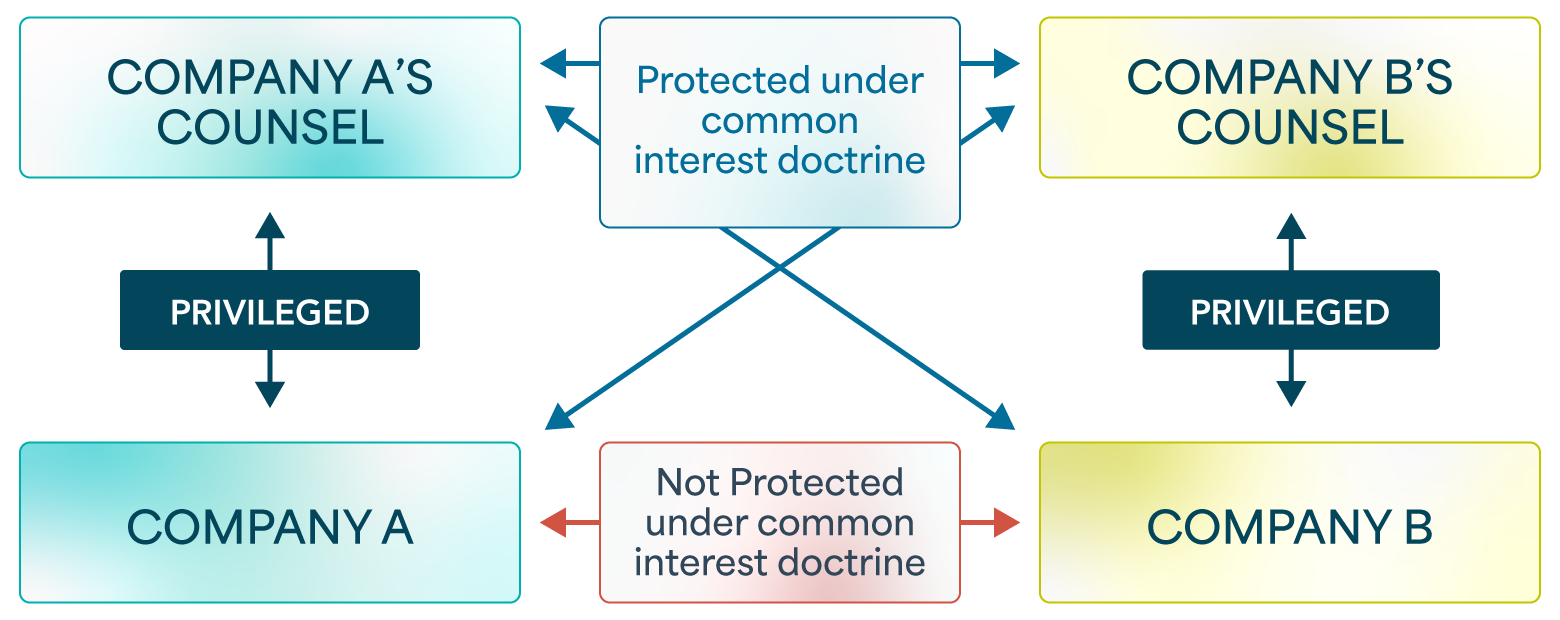
Do not assume privilege exists
Even if you believe a communication is privileged, write with the expectation that it could be reviewed by a court. Privilege does not necessarily extend automatically to subsidiaries or affiliates. Ensure formal retention and clear documentation when representing multiple entities or working with advisors. Additionally, the law governing privilege can vary significantly by jurisdiction; thus, it is important to seek the advice of counsel prior to any communications.
Labels help but don’t control
Mark emails or memos as “Attorney-Client Privileged” and “Confidential,” but remember: substance, not form, determines privilege. Where possible, clearly reference the legal advice sought or provided.
Be explicit in requests for legal advice
Directly address in-house or outside counsel, specify the legal issue, and avoid copying attorneys merely to shield a document.
Separate legal from business content
When communications blend legal and business matters, separate them or document the legal purpose clearly.
By proactively managing privilege, in-house counsel and executives can strengthen the protection of sensitive communications, preserve confidentiality, and reduce litigation risk.
President Trump’s December 11, 2025 Executive Order aims to protect American AI innovation from what it characterizes as overly burdensome state AI laws by creating a Department of Justice AI Litigation Task Force to identify and challenge problematic state regulations, conditioning federal Broadband Equity, Access, and Deployment (BEAD) Program funding on state AI policy alignment, directing the Federal Communications Commission (FCC) to consider preemptive federal AI reporting standards, and instructing the Federal Trade Commission (FTC) to clarify how Section 5 of the FTC Act applies to AI in ways that could preempt conflicting state laws. The Executive Order stops short of imposing the broad 10-year moratorium on state AI laws that was previously proposed in legislation, instead taking a more targeted approach that carves out state authority over child safety, AI infrastructure, and government AI procurement. The Executive Order also calls on Congress to enact a uniform federal AI framework.
Under Texas law, informal fiduciary relationships (which can theoretically arise from any personal or business relationship of special trust and confidence) are frequently claimed in litigation but almost never succeed. Two recent decisions illustrate the doctrine’s narrowing scope: in Pitts v. Rivas, the Texas Supreme Court rejected an informal fiduciary claim despite a decade-long personal friendship between an accountant and client, with a notable concurrence from Justice Huddle (joined by three justices) formally calling for the doctrine to be abandoned altogether. The Texas Business Court reached a similar conclusion in Tall v. Vanderhoef, dismissing an LLC minority member’s informal fiduciary claim because no special relationship of trust existed prior to and apart from the parties’ governing agreements. While the doctrine technically remains good law in Texas, courts continue to apply it with significant skepticism and practitioners should treat informal fiduciary claims as a high-risk, rarely successful avenue in business disputes
On July 7, 2026, the European Data Protection Board published draft guidelines on web scraping for generative AI, aimed at giving practical guidance on how EU data protection law applies when personal information is pulled from the open internet to train models. The guidelines cover both organizations that do the scraping themselves, directly or through a contractor, and organizations that license or reuse datasets someone else already scraped. For any company buying a generative AI system trained on internet-sourced data, the guidelines, as drafted, do not shift the data protection responsibility away from the buyer. The EDPB’s public consultation on the draft remains open until October 30, 2026, so the text can still change before it is finalized.
A greenshoe, which is also referred to as an overallotment option, is a provision in an underwriting agreement that allows the investment banks underwriting a public offering to sell more shares than originally planned to help stabilize the stock price after the offering. The term “greenshoe” comes from Green Shoe Manufacturing Company (now Stride Rite), which was the first company to use this mechanism.
Greenshoes are typically 15% of the potential base offering. If demand for an offering is much greater, a company would increase the base deal size. The window to exercise the greenshoe is almost always 30 days. Most typically, greenshoes are additional shares issued by the company but the greenshoe can be comprised of shares held by a selling stockholder.
A greenshoe can exist in both an “initial public offering” (IPO) and a follow-on public offering. Greenshoes are not used in “registered direct offerings” (RDOs) or deals referred to as “underwritten RDOs”.
Here is a simple example of a greenshoe:
- The company plans to sell 10 million shares of its common stock, which are referred to as the base shares, in its IPO.
- The greenshoe would be 1.5 million shares, or 15% of the base shares.
- If the underwriters elect to exercise the greenshoe, they may sell up to 11.5 million shares to investors, which is the sum of the base shares plus the greenshoe.
Why does a greenshoe exist?
The greenshoe helps:
- stabilize the stock price after a public offering;
- meet excess demand if investors want more shares; and
- protect underwriters from losses during the first trading days.
In practice, underwriters use the greenshoe to stabilize the stock price during the first 30 days after a public offering. The mechanics revolve around short-selling and covering that short position depending on where the price trades.
For example, using the example above of a 10 million share base offering, with a 1.5 million share greenshoe, and a public offering price of US$10.00:
- The underwriters will sell 11.5 million shares to investors, even though only 10 million shares are initially issued by the company to the underwriters.
- They do this by borrowing 1.5 million shares from the issuer or selling syndicate and creating a short position of 1.5 million shares.
- As a result, immediately after the offering, investors hold 11.5 million shares, only 10 million of which are actually issued, and the underwriters are short 1.5 million shares.
This short position is the key tool for stabilization. If the stock price falls below the offering price — for example, if the price falls to US$8.00 — the underwriters will buy shares in the open market at US$8.00 and use those shares to cover their 1.5 million shares short position. That open market-buying demand supports the stock price, and the underwriters profit (sold at US$10.00 and bought back at US$8.00). In this case, the greenshoe would not be exercised, the total shares issued in the offering is 10 million, and the company will have raised US$100 million in gross proceeds.
If the stock price rises above the offering price — for example, if it trades to US$15.00 — buying shares in the open market would be expensive for the underwriters. Instead, underwriters exercise the greenshoe and buy 1.5 million shares from the company at US$10.00. They then deliver those shares to cover their short position. In this case, the greenshoe is exercised, the total shares issued in the offering is 11.5 million, and the company will have raised US$115 million in gross proceeds.
Occasionally, the stock price is volatile and, during the greenshoe period, may trade above and below the offering price, which could result in a partial exercise of the greenshoe to cover the portion of the short position that resulted while the stock price was higher than the offering price. Generally, the greenshoe cannot be exercised in an amount that exceeds the net short position at the time of exercise.
In an article for Life Science Leader, partners Sally Wagner Partin, Sharon Flanagan, and Torrey Cope examine how artificial intelligence is reshaping life sciences M&A by changing the pace and economics of drug development. They explore how AI’s growing role in target identification, clinical development, and regulatory decision-making is influencing valuation, due diligence, milestone structures, transaction timing, and risk allocation, and outline key considerations for dealmakers as AI continues to transform the life sciences industry.
A founder-chief executive officer (CEO) whom the board no longer trusts may still hold a board seat, meaningful equity, and a dual-class voting block. A chief operating officer’s departure may activate a key-person provision in a venture debt facility before the company has aligned on a successor or a message. For later-stage private companies, an executive transition is rarely just an employment event: it can become a governance contest, a financing issue, an investigation, a cap-table negotiation, and a litigation risk at the same time. Below is a brief summary of some (but not all) key decisions and steps to consider when leadership changes hands and how to approach such change from inside the impacted organization.
Setting the Stage: Why the Nature of the Departure Drives Everything
Start by deciding what kind of event the company is actually managing: planned succession, negotiated exit, resignation, termination without cause, termination for cause, or an asserted resignation for good reason. These are not labels reserved for the separation agreement or the press statement. The characterization can control acceleration triggers, severance eligibility, notice and cure rights, release leverage, restrictive-covenant arguments, lender or investor notifications, and what the company can say to employees, investors, customers, and the market. An orderly succession may permit a staged handoff; an abrupt exit may require immediate access controls and a parallel fact investigation. Before anyone communicates, align the board, Human Resources (HR), finance, legal, and operations teams on the factual record and decision rights. Confirm the employment agreement, equity plan and award agreements, incentive arrangements, change-in-control terms, key-person provisions, and applicable policies. Labor-law compliance remains the baseline: assess discrimination, retaliation, whistleblower, wage-and-hour, final-pay, accrued-leave, benefits-continuation, and notice requirements, as well as any works-council or collective-bargaining obligations. Honor contractual payment and notice terms, and document the legitimate business rationale and decision process.
Governance and Board Dynamics: Beyond Simple Recusal
When a founder-CEO is also a director, holds protective provisions, or controls a dual-class voting block, removing the executive from an operating role does not necessarily change board composition or voting control. Separate the board’s power to remove an officer from the stockholders’ or, where permitted by applicable law and the governing documents, the board’s power to remove a director. Confirm who can call the meeting, what quorum and voting thresholds apply, whether an investor designation or protective provision is implicated, and whether a voting agreement, charter provision, or side letter constrains the path. A clean termination process can still fail if the company treats a governance problem as an HR action.
When the departure is tied to an internal investigation, run three tracks deliberately: protect facts and privilege; decide whether interim controls or termination for cause are warranted; and assess whether a negotiated separation creates value without compromising the investigation. Use an independent committee or outside counsel when the board’s independence is in question, define the client and privilege purpose at the outset, and keep business, HR, and communications teams on a need-to-know basis.
Investor and Stakeholder Dynamics: When a Departure Becomes a Capital-Structure Event
Credit agreements, venture debt facilities, preferred-stock documents, investor side letters, and material commercial arrangements may contain key-person provisions that require notice, consent, a replacement plan, or a cure period, and may turn silence into a default. The same analysis should cover customer, regulatory, and financing diligence processes already underway.
A departing stockholder-executive may retain board-observer status, inspection or information rights, rights under a voting agreement, or a contractual right to receive notices even after system access is revoked.
Investor relations should be sequenced, not improvised. Decide which directors, lead investors, lenders, and major stakeholders need a direct call, who will make it, and what they need to know about interim leadership, business continuity, financing impact, and customer coverage. Communicate early enough to avoid surprise but only after authority, facts, and the core message are aligned. A single factual narrative is more valuable than a detailed explanation of disputed allegations; document what is being said and to whom, and avoid allowing a departing executive or an investor to define the story through a leak.
Bring the director and officer (D&O) broker and carrier into the analysis early. Confirm notice obligations, extended-reporting or tail coverage, indemnification and advancement rights, and whether the facts could trigger a conduct exclusion or a coverage dispute. An allegation of misconduct can affect both the company’s and the departing executive’s coverage, especially if the company makes admissions or settles before giving the carrier a meaningful opportunity to respond. Separation documents should preserve applicable indemnification and cooperation arrangements, allocate responsibility for notices, and avoid language that unintentionally prejudices coverage.
Negotiation Strategy: Beyond the Severance Check
Map the executive’s priorities – equity treatment, exercise window, health coverage, title or reference, timing, transition, advisory role, indemnification, and departure message – then package concessions rather than negotiating one item at a time. At the same time, separate contractual entitlements from discretionary consideration and validate every term against the employment agreement, equity documents, plan rules, wage laws, benefits rules, and tax constraints.
Departure messaging is another bargaining instrument: agree who speaks, when the statement is issued, how the role is described, what reference is provided, and whether mutual non-disparagement is conditioned on performance. If the parties cannot align, have a short, factual unilateral message ready rather than letting the dispute write it.
Acceleration disputes usually turn on whether the termination was “without cause,” whether the executive established “good reason” and satisfied notice-and-cure requirements, and who had authority to make the decision. That characterization can cascade into vesting, exercise deadlines, repurchase price, dilution, withholding, and the executive’s leverage in a release. Also ask how separation interacts with drag-along, tag-along, transfer restrictions, voting agreements, and investor-consent rights. A departing executive who remains a significant stockholder may still be able to block, participate in, or complicate a sale. Coordinate any repurchase or recovery with wage laws and the governing documents; do not assume the company can simply withhold amounts otherwise owed.
Litigation Risk and Enforcement Strategy: Preserve Optionality Before You Escalate
Test the company’s legitimate protectable interest, the likelihood of irreparable harm, the evidence of competitive risk, and whether enforcement would accelerate disclosure or make the former executive a sympathetic witness. A targeted confidentiality, customer non-solicitation, intellectual-property, or trade-secret remedy – or carefully structured garden leave – may preserve more value than an overbroad non-compete.
A measured demand letter can identify continuing obligations, request return or deletion of information, preserve the company’s position, and invite a controlled resolution. A tolling agreement can protect limitations periods while the parties investigate, and targeted forensic imaging can preserve devices, cloud records, access logs, and transfer history before evidence disappears. Use legal holds, a defensible collection protocol, and an appropriate forensic vendor; overcollection, careless accusations, or an unlawful review of personal data can create the next dispute.
Before finalizing the departure, stress-test whistleblower and retaliation theories. Build a chronology of complaints, investigations, performance actions, protected disclosures, and decision-maker involvement; confirm that the stated rationale is supported by contemporaneous evidence and would have produced the same result absent protected activity. Keep the investigation independent where necessary, avoid labeling allegations as established fact, and ensure the separation agreement and communications do not restrict legally protected reporting. The goal is not merely to win the severance negotiation; it is to prevent the departure from being recharacterized as retaliation after the executive leaves.
Sequencing the Transition: Order of Operations Matters
First, preserve authority, facts, and business continuity: confirm the board action, legal hold, key-person notices, interim coverage, and immediate safety or access needs before the executive is told, where the risk profile permits. In parallel, build two calendars, one for the contested legal and negotiation track and one for the operating track, covering notice, severance and equity modeling, communications, customer and investor outreach, access changes, successor coverage, and knowledge transfer. After notice, execute access changes, device preservation, written reminders, and a controlled handoff in a coordinated sequence. Nonessential courtesy items, such as a reference format or advisory title, can wait until core rights and preservation steps are secured.
Identify mission-critical relationships, approvals, systems, customer commitments, product decisions, financial processes, and pending disputes; assign an owner and a deadline for each item. Use supervised sessions, written inventories, clean-room access, and time-boxed cooperation rather than giving a departing executive broader access simply to make the handoff easier. Decide whether a successor starts before the final day, whether an interim leader fills the gap, which board, customer, investor, and employee communications happen, and who signs off on completion. Document board resolutions, the termination or separation agreement, intellectual-property assignments, release, repayment or repurchase terms, cooperation obligations, successor agreements, authority matrices, and restrictive-covenant terms. Treat the paperwork as an operating control: it must match the actual sequence and must not promise rights the board has not approved.
Trade Secrets and Confidential Information: A Strategic Approach
When facts permit, conduct forensic triage before the departure conversation. Under an appropriate legal hold and applicable privacy and employment rules, identify high-value repositories, privileged files, source code, customer lists, pricing, financing materials, personal-device connections, and access logs; preserve targeted images and logs rather than taking an indiscriminate data grab. Build a trade-secret inventory and identify what makes each item secret: limited access, labeling, contractual controls, training, or technical safeguards. If the contract and applicable law permit, garden leave can serve as a cooling-off tool: maintain pay and benefits while suspending operational access and competitor contact instead of forcing an immediate binary choice between active access and termination.
Remind the executive in writing of confidentiality, intellectual-property, cooperation, non-solicitation, and other post-employment obligations, while preserving applicable indemnification and privilege boundaries. If the executive retains an advisory role or stockholder or observer rights, use segregated, time-limited access and a designated channel rather than blanket credentials. For a competitor departure, conduct a documented risk assessment, monitor only where lawful and disclosed, and escalate suspicious transfers; account for personal data, cross-border rules, and bring your own device (BYOD) before collecting or reviewing content.
A federal judge in Manhattan ruled in May 2026 that the government could not blame ChatGPT for its own decision to terminate more than 1,400 federal grants that the tool had flagged as related to diversity, equity, and inclusion. Staff fed short grant descriptions into the model and asked whether each one related to DEI, then acted on the answers without reading the underlying applications, without defining what DEI meant, and without a single instance of a reviewer disagreeing with the tool. The Court treated the prompts and outputs as discoverable evidence, noting that a decision-maker who chooses a tool cannot escape responsibility by blaming it.
For any company building generative or agentic AI into core business functions, the practical points are about governance: who is allowed to write prompts, whether reviewers have the expertise and authority to override an output, and whether the process is documented. AI-generated records can later surface in litigation or regulatory review, accurate or not.
On June 22, 2026, the White House issued two executive orders on quantum technology: “Ushering in the Next Frontier of Quantum Innovation” and “Securing the Nation Against Advanced Cryptographic Attacks.” Quantum computers can solve certain problems far faster than ordinary computers, which opens up new commercial possibilities but also threatens the encryption that protects most online communication and stored data today. The orders push federal agencies past pure research toward deployment, commercialization, workforce building, and national security uses.
By the time a venture-backed company reaches its mid to late stages, its board is usually built out of overlapping interests. Directors are affiliated with the funds that led earlier rounds, a founder may hold a large voting block, and executives and investors alike see a steady stream of opportunities, some of which look a lot like the company’s own roadmap. Generally, Delaware corporate law treats these relationships not as misconduct but as a process question. Most recently, Delaware corporate law received meaningful codified updates to its conflicted transaction rules and the key in evaluating such transactions remains to ensure that process follows the most recent developments in the law.
Loyalty Sets the Baseline
Directors and officers of a Delaware corporation owe fiduciary duties of care and loyalty to the corporation. The duty of loyalty bars a fiduciary from using a position of trust to advance personal interests at the corporation’s expense, and it is the source of both bodies of law discussed here. A conflict of interest does not by itself make a transaction wrongful; what it changes is the standard of judicial review if the transaction is later challenged. A conflicted transaction that has not been properly cleansed risks review for entire fairness, the most demanding standard under Delaware law, while a transaction that satisfies the statutory safe harbors described below is insulated from fiduciary duty damages and equitable relief.
Conflicted Transactions Under Section 144
DGCL Section 144 gives boards a set of alternative cleansing paths. An act or transaction involving a conflicted director or officer qualifies for the safe harbor if any one of the following is true: the material facts of the interest and the transaction are disclosed or known to the board or a committee, and a majority of the disinterested directors approve it in good faith and without gross negligence; the transaction is approved or ratified by an informed, uncoerced, affirmative vote of a majority of the votes cast by the disinterested stockholders; or the transaction is fair to the corporation and its stockholders. However, if a majority of the board is conflicted, the director-approval route must run through a committee of at least two disinterested directors.
Controlling stockholder transactions have their own rules, and the statute defines who is a controller: a person who owns or controls a majority of the voting power, has the right to cause the election of a majority of the board, or holds at least one third of the voting power together with the power to exercise managerial authority over the corporation’s business and affairs. On a maturing cap table, that can describe a founder with high-vote stock or, in some circumstances, a lead investor, and stockholders acting together under an agreement or understanding can constitute a control group. A controlling stockholder transaction (other than a going private transaction) qualifies for the safe harbor if it is approved or recommended by a committee of at least two disinterested directors with express authority to negotiate and to reject the transaction, or if it is conditioned on and receives an informed, uncoerced majority-of-the-minority vote. Only a going private transaction requires both protections, a deliberate departure from prior case law, under which both were generally required for a controller transaction to earn business judgment review.
The statute also defines disinterestedness. A disinterested director is one who is not a party to the transaction and has no material interest in it or material relationship with a person who does, with materiality keyed to whether the director’s objectivity would reasonably be expected to be impaired. Directors of exchange-listed companies also receive a heightened presumption of disinterestedness if the board has determined they are independent under exchange rules, a provision that becomes relevant after an IPO.
The Corporate Opportunity Doctrine
The corporate opportunity doctrine answers a different loyalty question: when a business opportunity belongs to the corporation rather than to the fiduciary who learned of it. A director or officer of a Delaware corporation may not take an opportunity for personal benefit if the corporation is financially able to undertake it, the opportunity falls within the corporation’s line of business and would be of practical advantage to it, the corporation has an interest or reasonable expectancy in it, and taking it would place the fiduciary’s self-interest in conflict with the fiduciary’s duties. The Delaware Supreme Court has emphasized that the factors are weighed together and that no single factor is dispositive.
In the venture ecosystem, fund-affiliated directors see deal flow across an entire portfolio, and founders and executives routinely encounter ideas adjacent to the corporation’s business. A fiduciary who takes an opportunity that a court later decides belonged to the corporation faces disgorgement of the opportunity or its proceeds. However, a fiduciary who presents the opportunity to the board and obtains a rejection from disinterested directors gains the benefit of a safe harbor, mitigating the risk of an after-the-fact judicial determination that the opportunity was usurped. Presentation is not legally required, but it creates a clean contemporaneous record, and the rejection should be clearly documented in the minutes.
Advance Waivers Under Section 122(17)
Delaware also permits much of this to be resolved in advance. Section 122(17) of the DGCL authorizes a corporation to renounce, in its certificate of incorporation or by action of its board, any interest or expectancy in specified business opportunities or specified classes or categories of business opportunities, whether presented to the corporation or to one or more of its officers, directors, or stockholders. Waivers of this kind are common in venture capital investments, where a firm and its designees may hold positions and board seats across a sector, and it is recommended to build them into the certificate of incorporation at the time of investment (which is consistent with the NVCA model certificate of incorporation). Note that such a waiver addresses only the corporate opportunity doctrine, not confidentiality. Accordingly, funds holding positions in competing companies should maintain information screens and avoid seating the same designee on the boards of competitors.
That said, advance waivers may not be an absolute shield to all issues arising out of potential corporate opportunities. Although details are scant as of the time of writing, and we expect to publish more detailed analysis once information becomes available, in August of 2026 the U.S. Department of Justice has been investigating certain venture capital firms with partners serving on boards of competing companies, potentially raising antitrust concerns, separate from the corporate law concepts of corporate opportunity.
DO’S & DON’TS:
Board Process for Conflicted Transactions
DO: Surface conflicts early and choose the cleansing path before approval. Disclose all material facts about the fiduciary’s interest and involvement, obtain approval from a majority of the disinterested directors acting in good faith and without gross negligence, and use a committee of at least two board-determined disinterested directors whenever a majority of the board is conflicted.
DON’T: Treat a conflicted deal as either automatically prohibited or automatically safe because the terms feel like market. Without disinterested director approval, a qualifying disinterested stockholder vote, or provable fairness, the transaction and the fiduciaries remain exposed.
Controlling Stockholders and Investor Directors
DO: Test whether a founder, investor, or group acting together is a controlling stockholder or control group under Section 144(e) before structuring any related party transaction. For controller transactions, use a fully empowered committee of at least two disinterested directors or a conditioned majority-of-the-minority vote, and use both for a going private transaction.
DON’T: Assume control requires majority ownership; one third of the voting power plus managerial authority can suffice. And do not rely on a stockholder vote to cleanse a controller transaction unless the deal was conditioned on disinterested stockholder approval by its terms when submitted for the vote.
Corporate Opportunities
DO: Adopt a simple protocol: fiduciaries promptly disclose opportunities arguably within the corporation’s line of business, the board or its disinterested members decide whether the corporation will pursue them, and any rejection is documented in the minutes before the fiduciary proceeds.
DON’T: Let a director or officer pursue such an opportunity quietly, or with the corporation’s resources, personnel, or information. Informal assurances from management are not a substitute for board-level disclosure and a documented rejection.
Waivers and Information Hygiene
DO: Consider a Section 122(17) waiver in the certificate of incorporation tailored to fund-affiliated directors and stockholders, revisit its scope at each financing, and pair it with confidentiality screens where investors hold competing positions.
DON’T: Seat the same designee on the boards of competing portfolio companies or treat a waiver as permission to share the corporation’s confidential information.
A Delaware Court of Chancery post-trial opinion in Holzbaur v. Trolley Square Hospitality, LLC serves as a cautionary tale about imprecise LLC agreement drafting. The plaintiff believed he was a “cash contributing member” with irremovable status, but contradictory language in the agreement led the court to rely on extrinsic evidence (including emails, pre-formation conversations, and drafting history) to find he was actually a “sweat equity” member subject to removal at will. The case underscores that the flexibility of the LLC form carries drafting responsibility: internal inconsistencies open the door to costly litigation and invasive discovery, and ambiguities will be resolved based on the parties’ actual intent, not favorable contract language.
In Fortis Advisors, LLC v. Stillfront Midco AB, the Delaware Supreme Court strictly enforced an arbitration clause in a merger agreement, finding that a seller’s bad faith claims regarding earnout manipulation fell within the alternative dispute resolution (ADR) provision’s scope because they were fundamentally a dispute about the calculation of the earnout. The court looked at the substance of the claims, concluding that “why” the earnout calculation was wrong cannot be severed from an arbitration clause covering calculation disputes. The decision is a strong reminder to dealmakers to precisely delineate which disputes are reserved for courts versus arbitration, and to draft ADR provisions with enough specificity to avoid costly threshold litigation over arbitrability.